Chart Color Schemes
This analysis uses Suburbs and Localities (SAL) boundaries, which can materially differ from Statistical Areas (SA2) even when sharing the same name.
SAL boundaries are defined by Australia Post and the Australian Bureau of Statistics to represent commonly-known suburb names used in postal addresses.
Statistical Areas (SA2) are designed for census data collection and may combine multiple suburbs or use different geographic boundaries. For comprehensive analysis, consider reviewing both boundary types if available.
est. as @ -- *
2021 Census | -- people


Curious about local property values? Filter the chart to assess the volume and appreciation (including resales) trends and regional comparisons, or scroll to the map below view this information at an individual property level.
Find a Recent Sale

Sales Detail
Dallas has an estimated 6,824 residents, up from 6,762 at the 2021 Census. That puts 2,808 residents on each square kilometre. Population is estimated from ABS Estimated Resident Population releases and GNAF address data, re-based from the 2021 Census and updated annually.
Detail
According to AreaSearch's evaluation of broader regional ABS demographic releases alongside 37 validated new addresses identified following the Census, the resident count for the suburb of Dallas stands at roughly 6,824 as of Aug 2026. This represents a gain of 62 people (0.9%) compared to the 6,762 people recorded in the 2021 Census. These findings stem from an estimated resident population (ERP) figure of 6,810 established by AreaSearch using the June 2025 ABS release. Such numbers translate to a population density of 2,808 persons per square kilometer, positioning the suburb of Dallas in the top quartile of all assessed Australian localities.
Recent demographic expansion has been driven mostly by net overseas migration, which made up approximately 77.0% of total gains. Population forecasts incorporate ABS and Geoscience Australia projections published in 2024 (using 2022 as baseline data) across SA2 areas, supplemented where necessary by the 2023 VIC State Government LGA projections adapted via weighted aggregation to SA2 boundaries. Projected age-cohort growth from these models is also applied across the years 2032 to 2041. Over the longer horizon, the suburb of Dallas is anticipated to experience substantial demographic growth in the highest quartile nationally, expanding by 2,180 persons to 2041 under aggregated SA2 modeling, which equates to an overall 31.7% increase across 16 years.
Frequently Asked Questions - Population
23 new dwellings have been approved in Dallas over the past five years, an average of 4 a year. That is 0.5 approvals per 1,000 residents. Approvals are currently running at an annualised 7, running ahead of that longer-run average. Figures come from ABS building approvals aggregated to this Suburb (SAL) boundary and are updated monthly as the ABS releases them.
Detail
Analysis of ABS residential building approvals aggregated by AreaSearch indicates that Dallas has averaged approximately 4 new dwellings approved annually, totaling 23 homes across the past 5 financial years. During FY-25 to date, 7 building permits have been granted. Despite past local population contraction, this level of construction supply has remained reasonably balanced for incoming purchasers, with average expected construction costs running at $433,000 per dwelling in alignment with broader regional benchmarks. Furthermore, $5.7 million in non-residential commercial approvals has been registered this financial year, underscoring the area's predominantly residential character.
Residential building output in Dallas remains substantially below the wider Greater Melbourne benchmark. While this constrained construction pipeline supports asset values and buyer demand for existing properties, local approval volumes have picked up across recent periods. This subdued activity relative to national levels points to a mature urban footprint and potential land constraints. Current building permits are split evenly between standalone houses at 50.0% and medium-to-high density apartments or townhouses at 50.0%. This emphasis on higher-density building provides accessible entry price points for downsizers, first-home purchasers, and investors. It also marks a structural shift away from the prevailing built environment (where separate houses represent 84.0%), reflecting tighter infill capacity and changing living preferences. Currently, the suburb registers around 1139 people per dwelling approval, typical of an established market. Looking forward, Dallas is projected to add 2,166 residents through to 2041 based on the most recent AreaSearch quarterly release. Should residential building proceed at prevailing rates, construction volume could lag behind expanding demand, likely intensifying buyer competition and placing upward pressure on property values.
Frequently Asked Questions - Development
Development applications around Dallas
SOURCE: Planning portals and council registers, compiled by AreaSearch. Distance & bearing measured from the suburb midpoint.
AreaSearch tracks one current infrastructure or development project inside Dallas, worth an estimated $600 million. A further 76 sit in the immediately surrounding suburbs, taking the tracked pipeline within reach of the area to $172.7 billion. 13 are already under construction and 23 are due for completion within three years. The pipeline spans residential development, sports & recreation and transport & logistics. Records are compiled from Infrastructure Australia, state agencies, council planning portals and public announcements, reviewed and updated daily, then ranked by proximity, construction stage, completion horizon and project scale.
Detail
Infrastructure upgrades, major planning schemes, and regional investments serve as crucial catalysts for local performance. AreaSearch has pinpointed 4 major developments poised to influence the district. Prominent projects comprise the Time & Place Campbellfield Industrial Development, the Upfield Line Duplication and Extension to Roxburgh Park, Assembly Broadmeadows, and Parkview Broadmeadows, with subsequent summaries highlighting key details.
Professional plan users can use the search below to filter and access additional projects.
INFRASTRUCTURE SEARCH
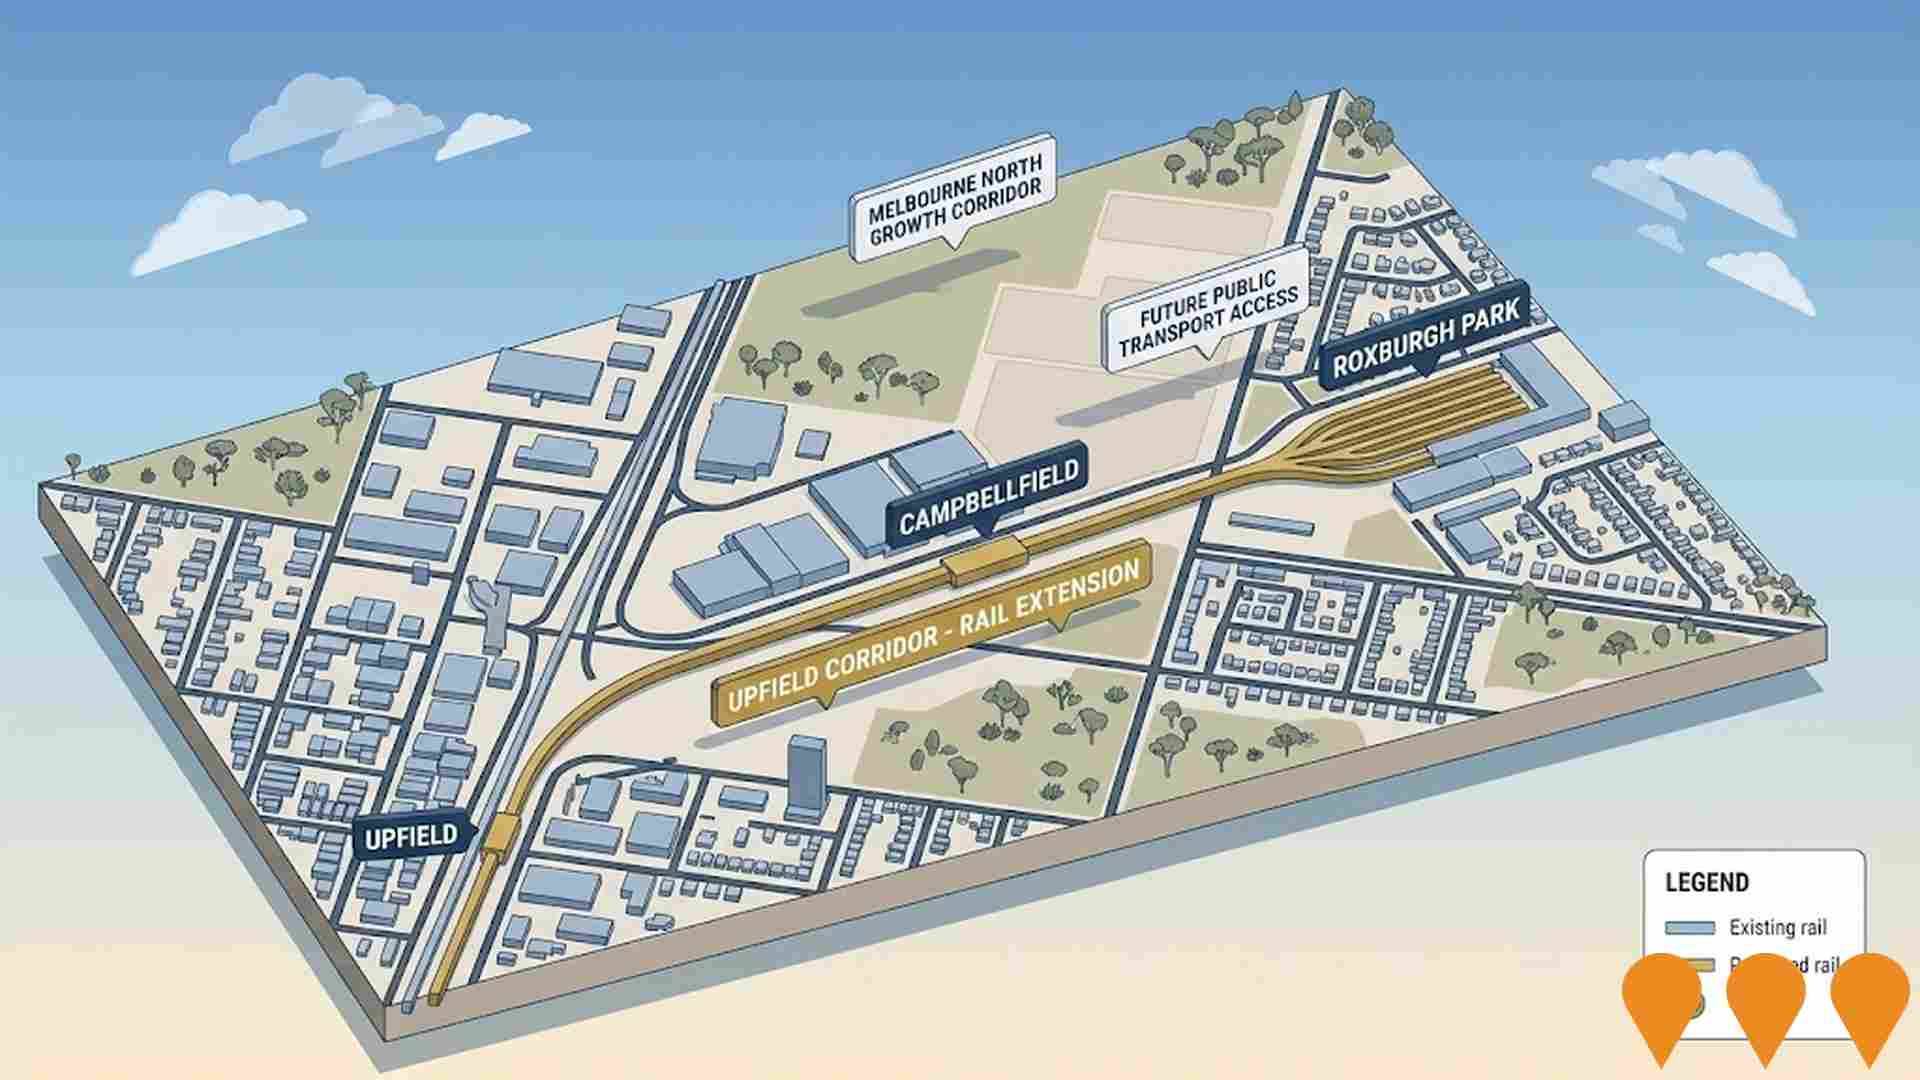
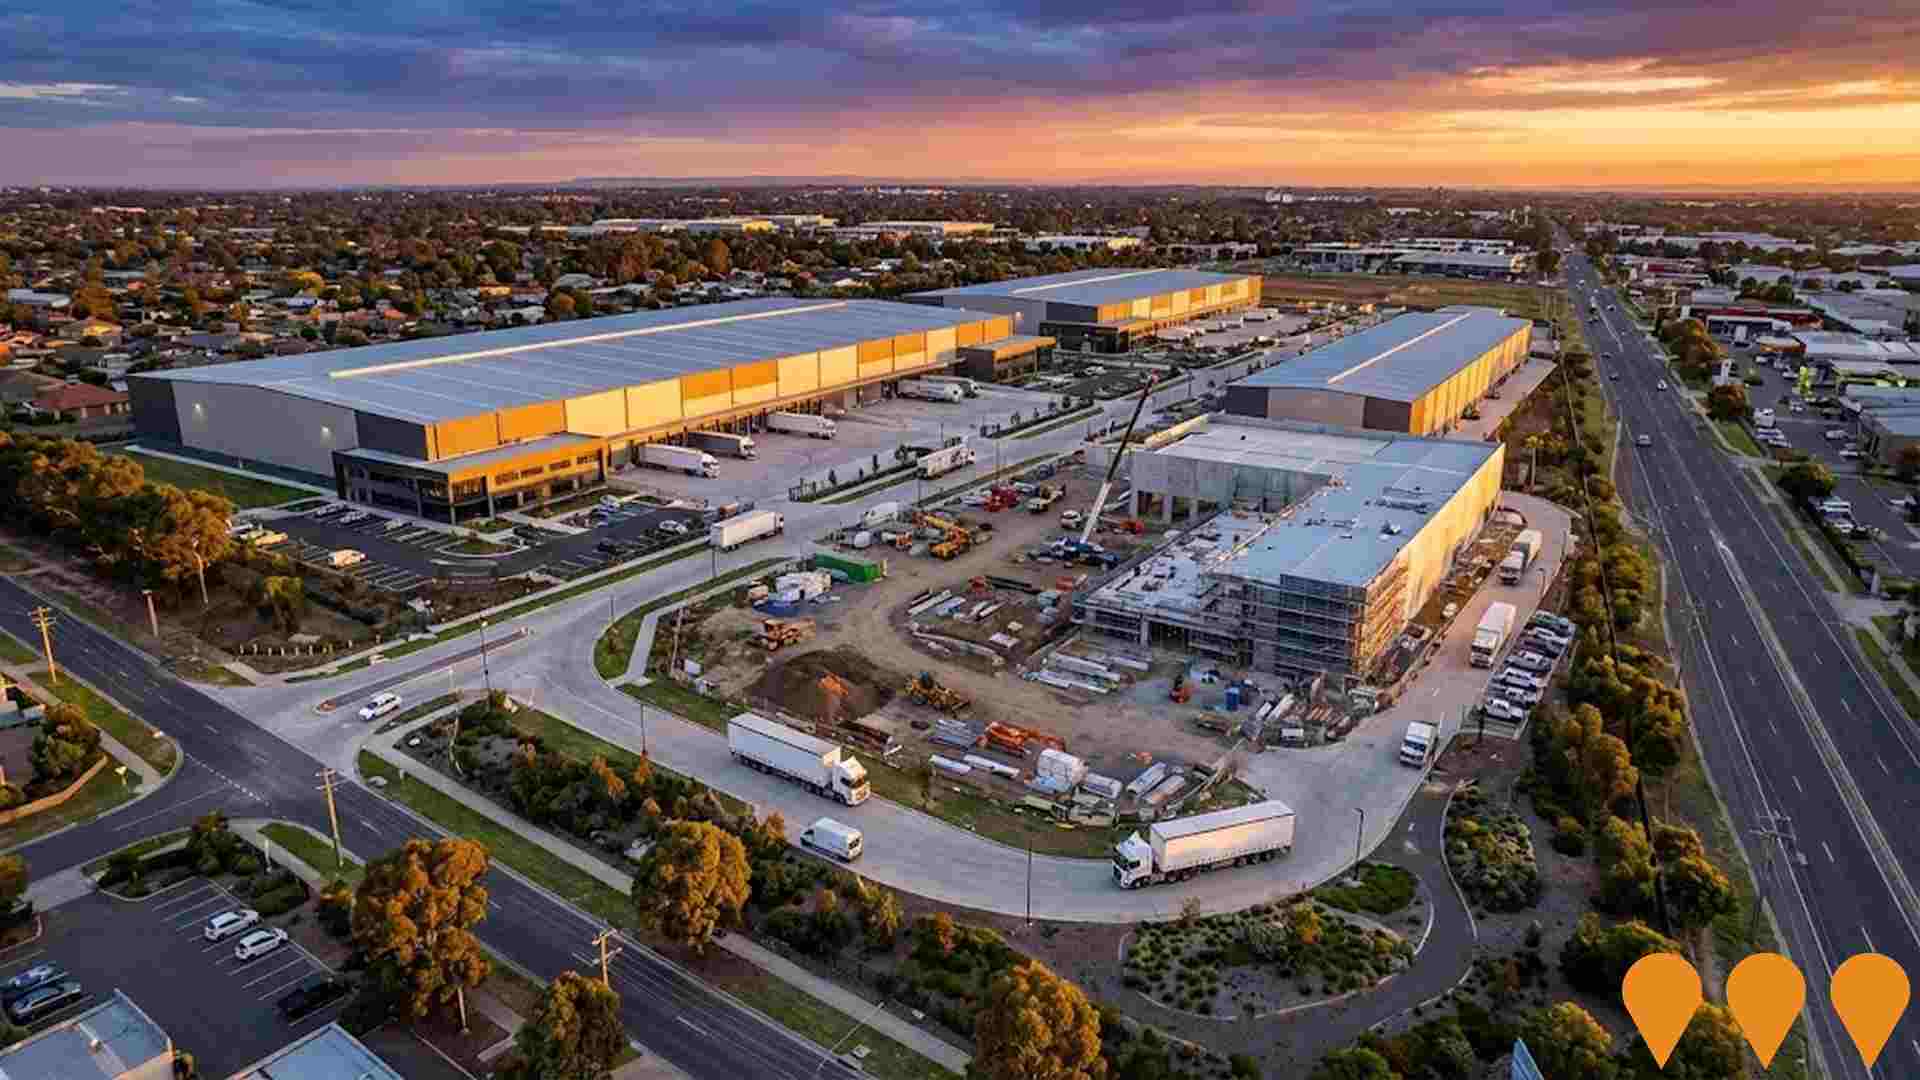
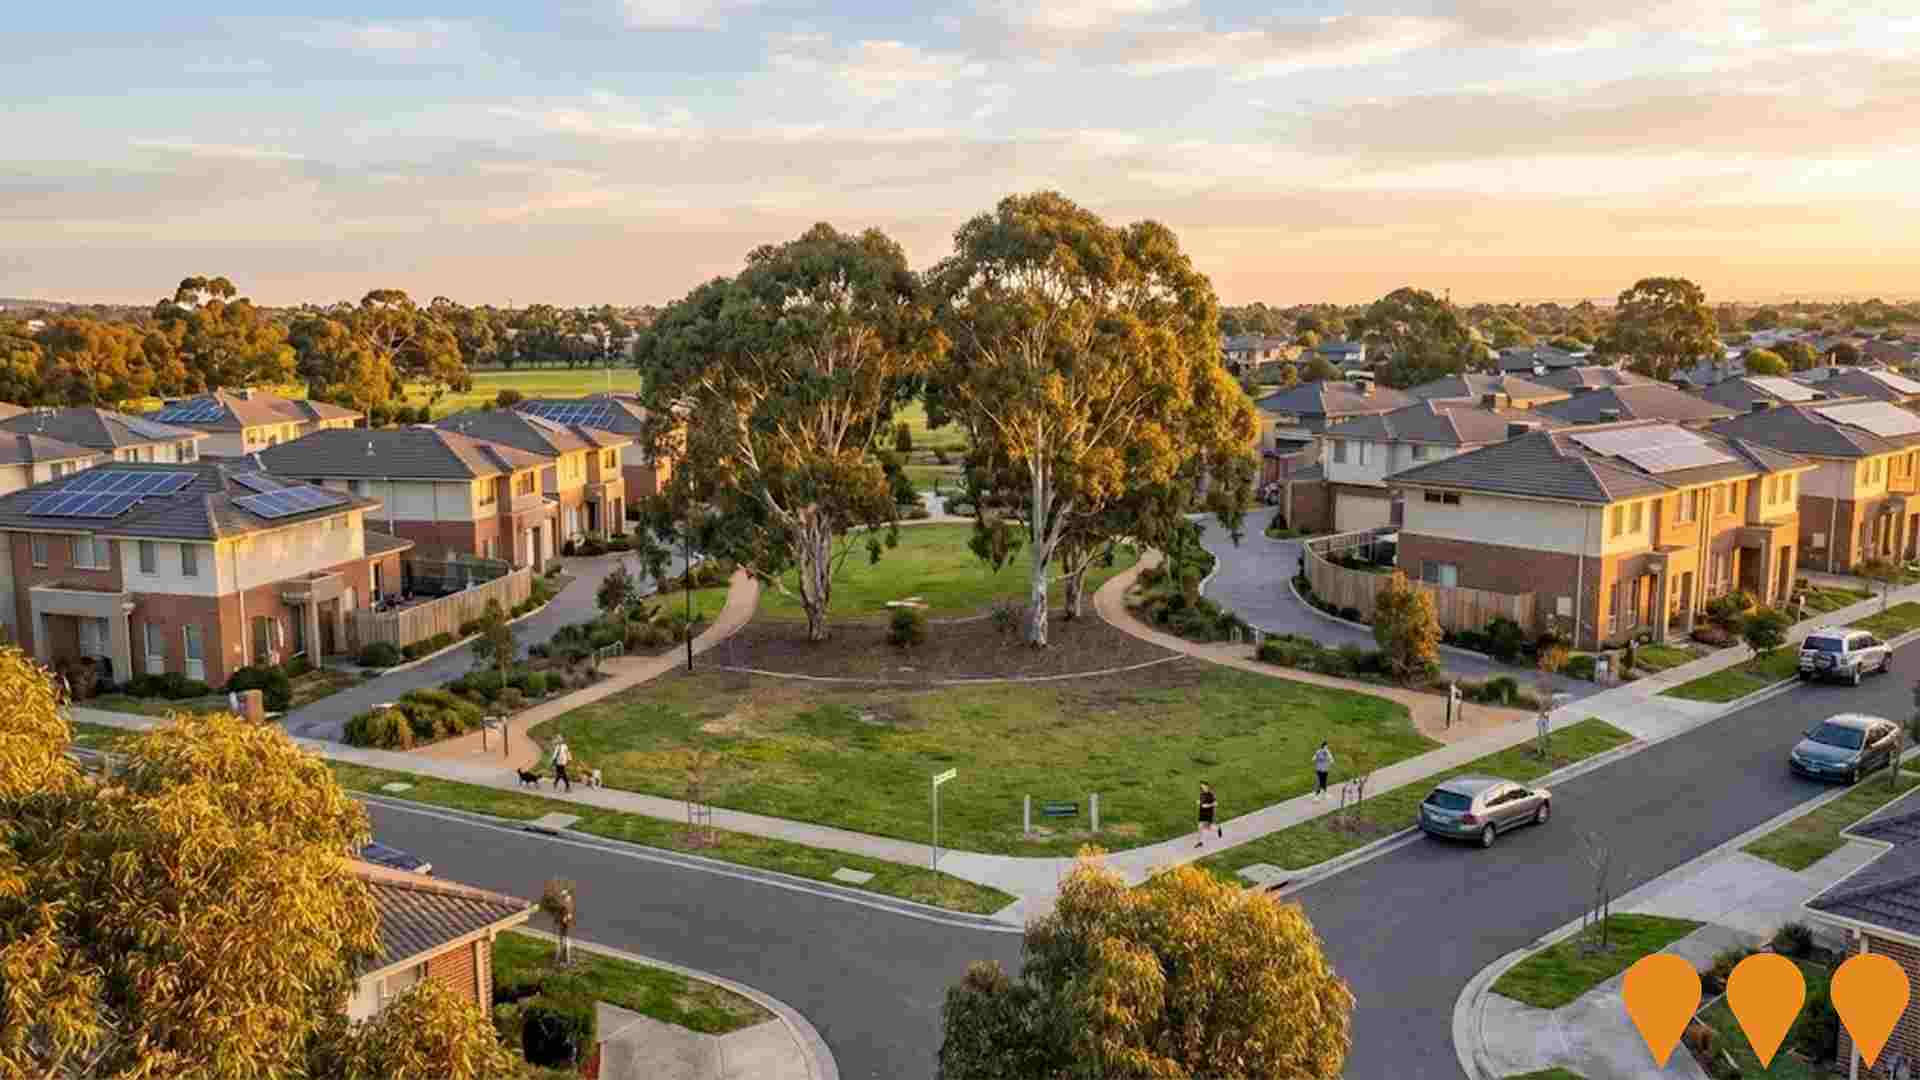
 Denotes AI-based impression for illustrative purposes only, not to be taken as definitive under any circumstances. Please follow links and conduct other investigations from the project's source for actual imagery. Developers and project owners wishing us to use original imagery please Contact Us and we will do so.
Frequently Asked Questions - Infrastructure
Upfield Line Duplication and Extension to Roxburgh Park
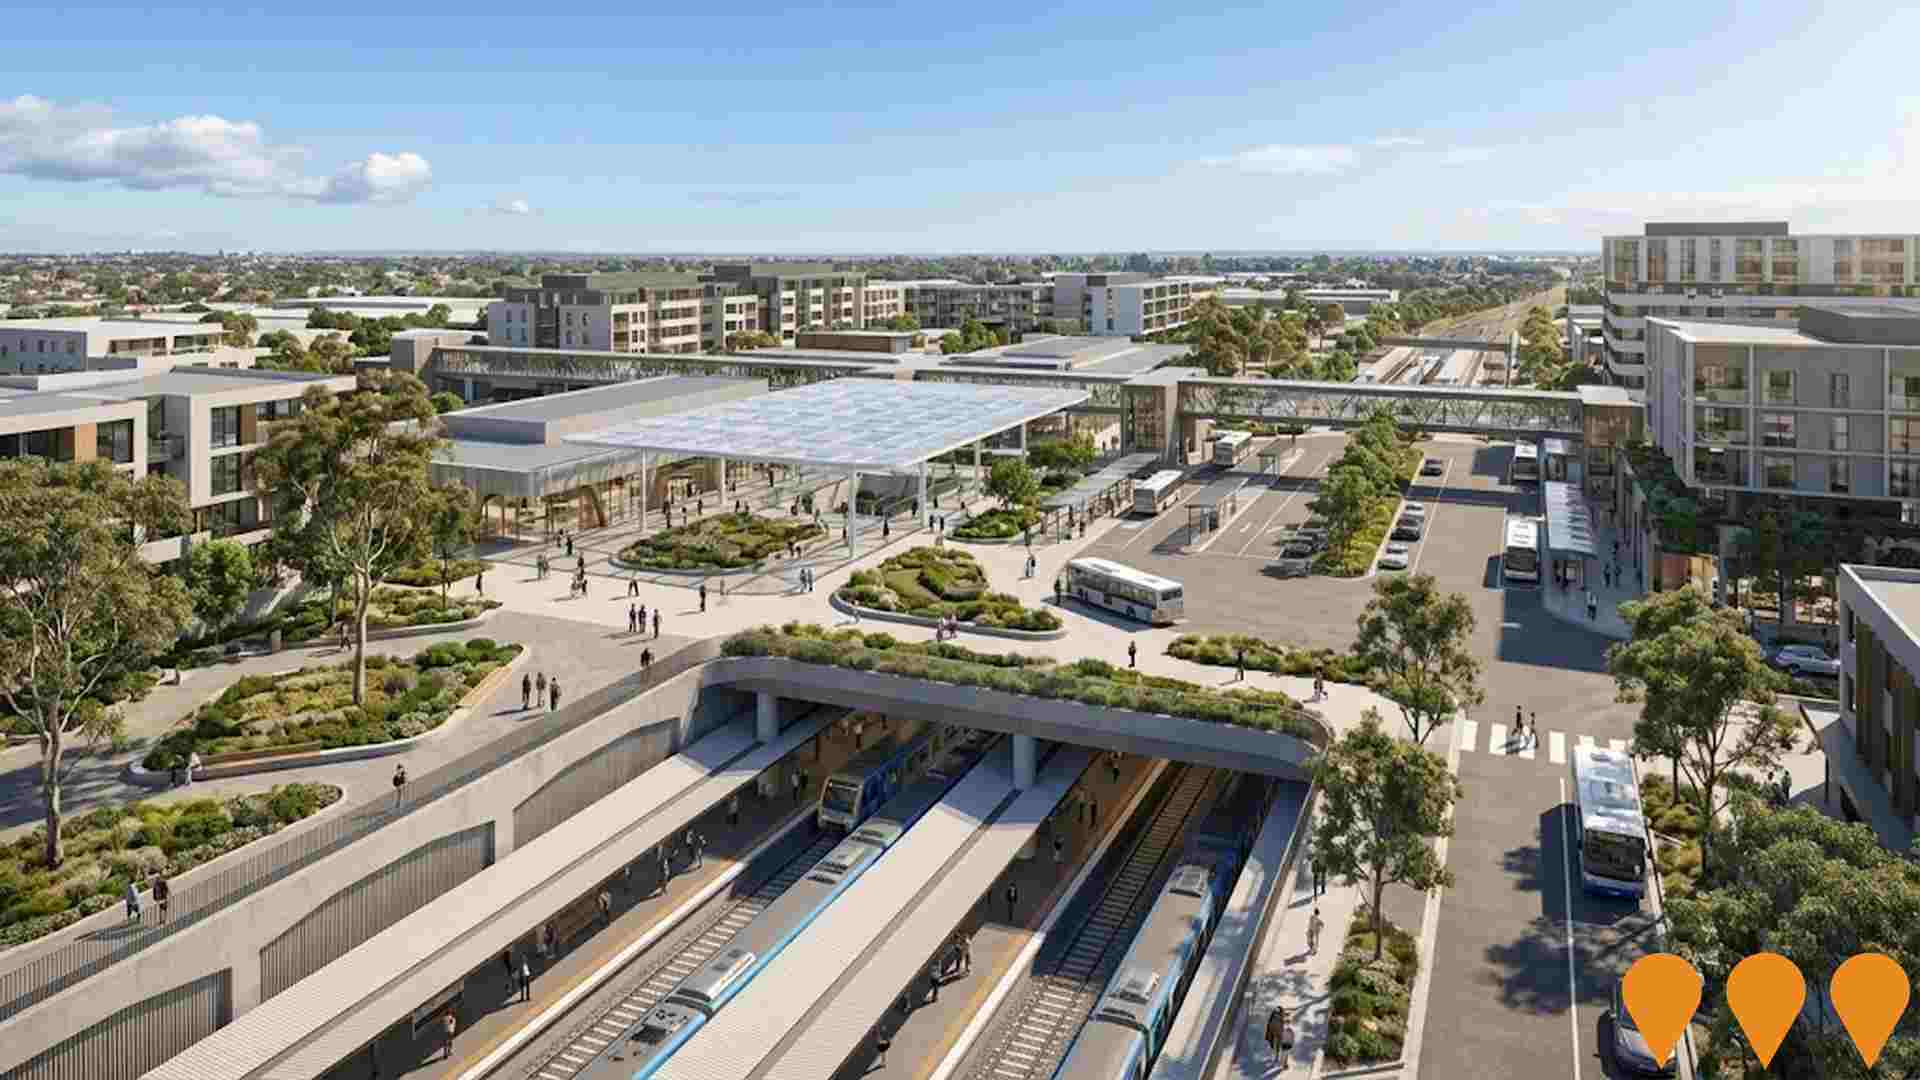
A staged proposal to duplicate, extend and electrify the Upfield rail line in Melbourne's northern suburbs. Stage one duplicates the single-track section between Gowrie and Upfield stations to lift service frequency and reliability. Stage two reopens, duplicates and electrifies the existing freight corridor from Upfield through to Roxburgh Park, including a grade-separated junction beneath the standard gauge interstate line and the Craigieburn line near Somerton Road. Future stages would extend electrified suburban services through to Craigieburn and Wallan, with new stations proposed at Beveridge and Cloverton to serve the rapidly growing Northern Growth Corridor.In February 2025 the Federal Government committed 7.05 million dollars towards a business case for upgrades on the Craigieburn, Upfield and Northern Growth Corridor lines, with the Federal Coalition separately pledging 2 million dollars for a scoping study. The 2025-26 Victorian State Budget did not allocate funding to the project. Advocacy is led by the Northern Councils Alliance, comprising Mitchell Shire, Banyule, Darebin, Hume, Merri-bek, Nillumbik and Whittlesea councils.
Assembly Broadmeadows
Assembly Broadmeadows is a 60-hectare master-planned redevelopment of the former Ford Australia Broadmeadows plant at 1727-1787 Sydney Road, Campbellfield, developed by Pelligra and Qualitas. Planned uses include high-tech manufacturing, logistics and warehousing, a retail convenience hub, childcare and a 100-room hotel. Construction is reported to have started in March 2026 with a 44-hectare first-stage industrial subdivision, but this has not been confirmed by an independent source. As at October 2026 the project website returned a 404 error.
Parkview Broadmeadows
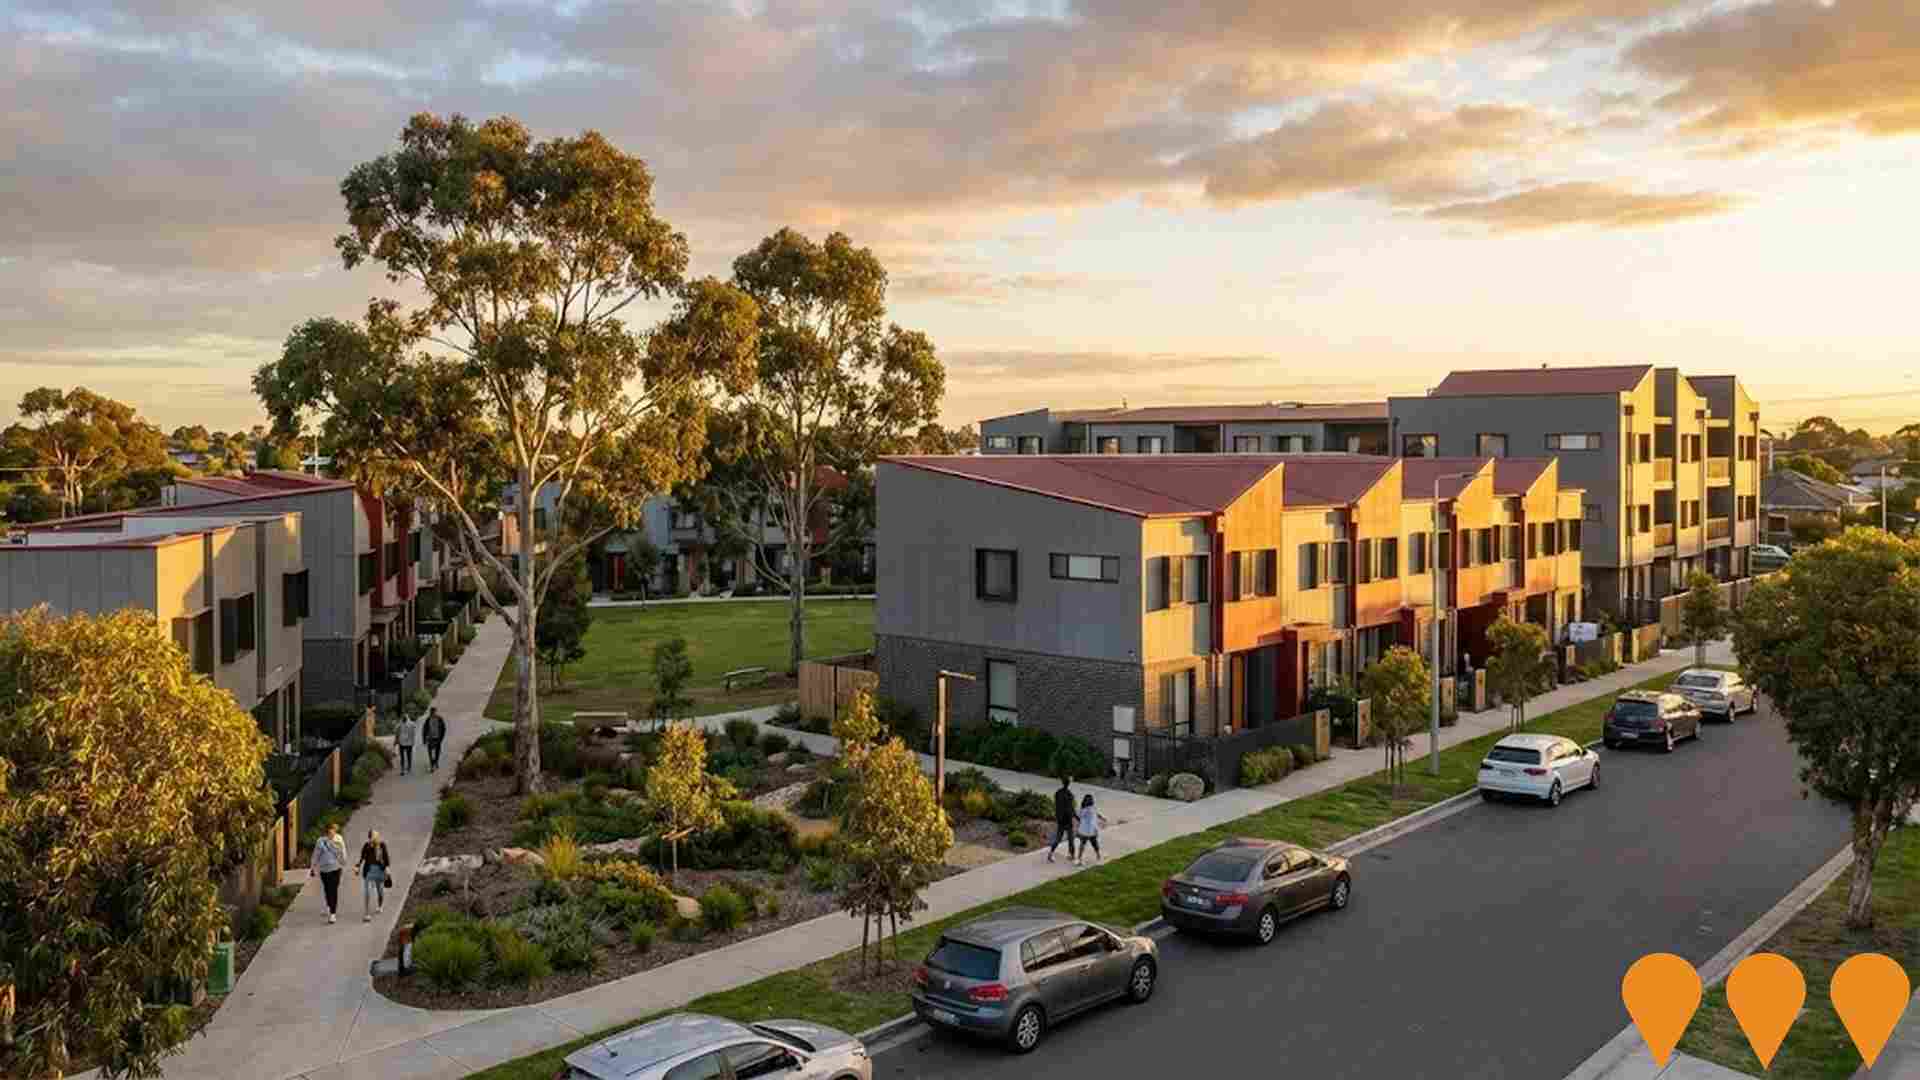
Townhouse community of approx. 65 architect designed 2, 3 and 4 bedroom homes by Met Communities / Moment Group, arranged around a centrally located park of about 7,500 sqm with walking and bike connections to Meadowlink Reserve. Sales underway with civil works commenced, delivering a mix including a small portion for an affordable housing provider under the Inclusionary Housing Pilot.
Meadow Heights Shopping Centre Redevelopment
Redevelopment of the existing Meadow Heights Shopping Centre, an IGA-anchored neighbourhood centre on a large 32,000 square metre site in Melbourne's north. The proposal includes a new childcare centre (around 132 places), an indoor and a restricted recreation facility, an extension to the existing retail space and updated signage. Hume City Council advertised the planning application (reference P23242) in early 2021 and the project remains in approved stage with no construction start confirmed. The wider site retains significant value-add development capacity including additional pad sites and an adjacent separately titled Commercial 1 zoned land parcel.
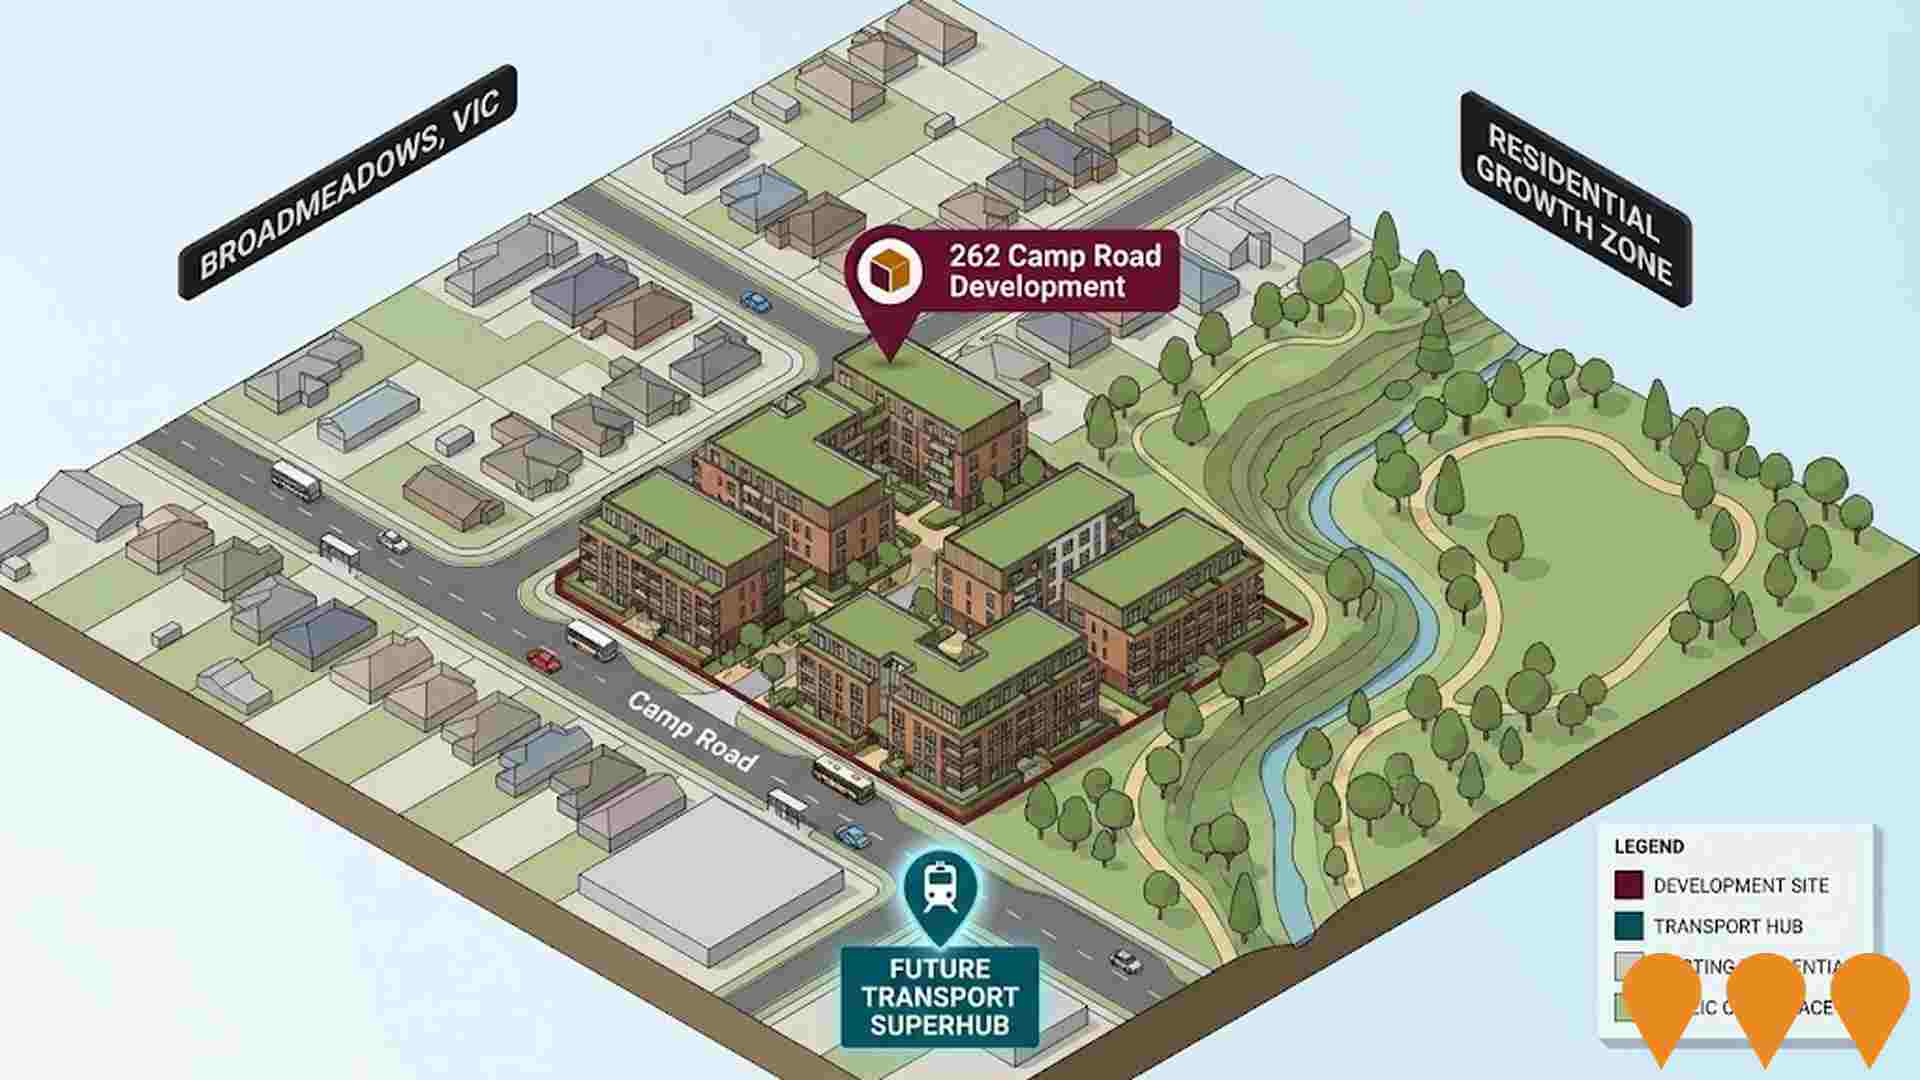
262 Camp Road Broadmeadows Development
Residential development project on Camp Road in Broadmeadows, strategically located near the future Broadmeadows transport superhub. Part of Activity Centre growth supporting increased density around transport. Listed on Urban.com.au as new off-the-plan development.
Canadian Court Reserve Playspace Improvements
Improvement works delivered by Hume City Council at Canadian Court Reserve to renew the playspace and play equipment. The project scope includes a multi-purpose looped walking and 'learn-to-ride' track, improved entry points, and a new shared use path connecting directly to Pascoe Vale Road and Coolaroo Station.
Time & Place Campbellfield Industrial Development
Redevelopment of a 15.9-hectare historic Ford distribution centre at 1777-1787 Sydney Road, Campbellfield, into a modern industrial precinct. Time & Place acquired the site from Ford Motor Company of Australia for approximately $80 million in early 2025 and lodged a planning application in Q1 2025. The project will target industrial, logistics, and warehousing tenants, with three existing warehouses (56,819 square metres) to be reworked or replaced. Ford retains a tenancy in one building for service engineering operations under a multi-year lease.Estimated end value of $250 million on completion by 2028, supporting Melbourne's tightly held northern industrial corridor.
Banksia Gardens Social Housing Development
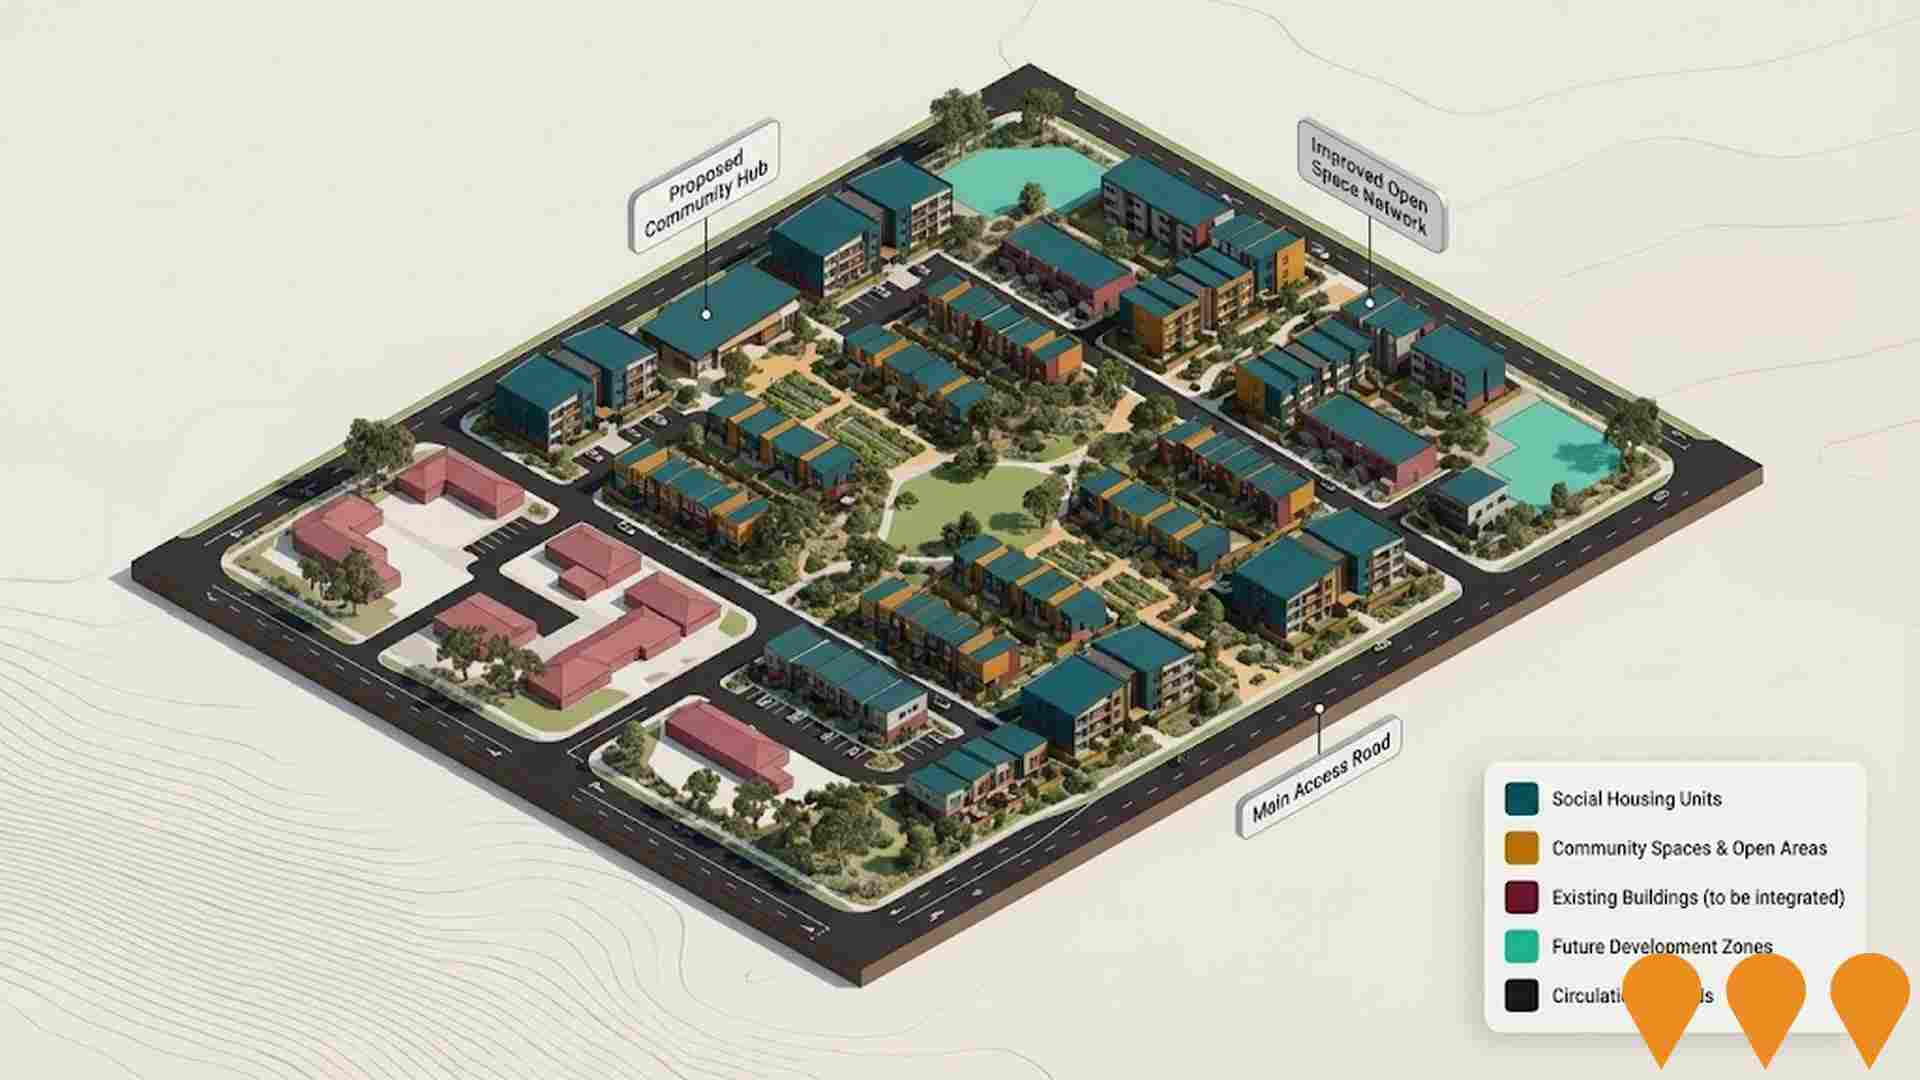
Delivery of approximately 120 new social homes on vacant land at Coleraine Street in the Banksia Gardens estate, Broadmeadows. Jointly funded by the Australian Government Social Housing Accelerator and the Victorian Government Big Housing Build at a combined investment of over $80 million. The development comprises a mix of one-, two- and three-bedroom homes across medium-rise buildings, with at least 5% designed to meet accessibility standards. Ground floor spaces include community facilities and non-residential areas.A new shared pedestrian and cycle path connects the estate to Coleraine Street and a nearby education precinct. Construction commenced October 2024 with LU Simon as head contractor; tower cranes left the site in early 2026 and internal and external fitout is underway. Homes are expected to be complete mid-2026 and will be managed by a not-for-profit community housing organisation.
2,045 residents of Dallas are employed, from a labour force of 2,425. Unemployment sits at 15.7%, with participation at 46.0%. Weighted for its industry mix, the area's sectors are forecast to grow about 5.8% nationally over five years. That reflects industry composition only and makes no allowance for local population growth. Unemployment and labour force come from ABS Small Area Labour Markets, updated quarterly; the industry and occupation profile is from the 2021 Census.
Detail
Dallas maintains a capable workforce featuring strong concentration across building and trade occupations, an overall jobless rate of 15.7%, and an estimated 3.7% annual rise in employed persons according to AreaSearch statistical modeling. As of March 2026, 2,045 local residents are employed. However, the local unemployment rate sits 10.9% higher than the Greater Melbourne benchmark of 4.8%, and the local labour participation rate of 46.0% trails the metropolitan figure of 70.1% substantially. Census records indicate that only 11.3% of workers operated from home, though pandemic-era restrictions during that survey period should be noted.
Resident employment is primarily anchored by manufacturing, health care & social assistance, and construction. Representation in transport, postal & warehousing is particularly prominent, tracking at 2.0 times the wider metropolitan average. In contrast, professional & technical roles account for only 3.2% of the local workforce compared to 10.1% across the region. The comparison between local job counts and resident worker tallies illustrates that this predominantly residential district provides limited employment within its own borders. AreaSearch analysis of ABS and SALM figures indicates that in the twelve months leading to March 2026, local employment grew by 3.7% while the labour force contracted by 1.9%, leading to a 4.6 percentage point decrease in the unemployment rate. Over the identical timeframe, Greater Melbourne experienced a 2.1% increase in employment, a 2.3% expansion in the labour pool, and a 0.2 percentage point uptick in unemployment. National outlooks from Jobs and Skills Australia as of Mar-26 provide further context on expected workforce trajectories; across the country, employment is anticipated to grow by 6.6% over five years and 13.7% over ten years. Mapping these industry projections onto the local occupational profile suggests Dallas could see employment gains of 5.8% over five years and 12.3% over ten years (representing an indicative weighted baseline that excludes localized demographic projections).
Frequently Asked Questions - Employment
Median household income in Dallas is $1,088 a week (about $57,000 a year), with median personal income at $427 a week. ATO records put median taxable income at $38,433 a year against an average of $46,534. Household income is from the 2021 Census; taxable income is from ATO Taxation Statistics for the latest financial year available, indexed forward using the ABS Wage Price Index.
Detail
ATO taxpayer records for financial year 2023 compiled by AreaSearch indicate that the suburb of Dallas registered a median taxable income of $38,433 and an average of $46,534. These figures sit below the Australian benchmarks as well as Greater Melbourne's medians and averages of $57,688 and $75,164. Factoring in cumulative Wage Price Index growth of 9.62% since financial year 2023, updated estimates reach approximately $42,130 for median income and $51,011 for average income as of March 2026. At the 2021 Census, individual, family, and household earnings all tracked between the 1st and 6th percentiles nationally.
Income distribution shows 30.6% of residents (2,088 individuals) earning within the $800 - 1,499 weekly bracket, contrasting with the regional trend where the $1,500 - 2,999 band forms the largest group at 32.8%. Severe mortgage and rent pressures leave residents with 80.0% of income remaining, placing the area at the 6th percentile.
Frequently Asked Questions - Income
Dallas had 1,982 occupied dwellings at the 2021 Census, 84% detached houses and 14% apartments. 34% are owned with a mortgage, 34% rented and 33% owned outright. At that Census the median rent was $323 a week and the median mortgage repayment $1,408 a month. Rent absorbs 29.7% of household income here and mortgage repayments 29.9%. Dwelling stock, tenure and housing costs are 2021 Census measures — the only source that counts dwellings at this boundary size.
Detail
The local housing landscape at the latest Census was composed of 83.9% standalone houses and 16.1% attached, semi-detached, apartment, or other dwelling formats, whereas Melbourne metro recorded 67.9% houses and 32.1% attached or multi-unit dwellings. Outright homeownership in Dallas reached 32.8%, surpassing the metropolitan standard, with 33.5% of residences held under a mortgage and 33.7% occupied by tenants. Median monthly mortgage obligations were notably lower than the Melbourne metro average at $1,408 versus $2,000, while median weekly rent was $323 compared to $390 metro-wide. Relative to national figures, local mortgage costs sit well below the Australian average of $1,863, and weekly rents track considerably under the national median of $375.
Frequently Asked Questions - Housing
Dallas counted 1,982 households at the 2021 Census, averaging 3.1 people each. 40% are couples with children, more than in 79% of areas nationally, against 15% couples without children. 21% of households are people living alone, and families average 2.0 children. Household and family composition is measured only by the Census, so these are 2021 figures.
Detail
Family units constitute the vast majority of local living arrangements at 75.4%, including 40.1% couples with children, 18.3% single parent families, and 15.0% couples without children. Non-family residences make up the remaining 24.6%, consisting of 21.0% single-person households and 3.5% group living setups. The typical household size stands at 3.1 people, exceeding the Greater Melbourne standard of 2.6.
Frequently Asked Questions - Households
18.6% of adults in Dallas hold a university qualification, including 12.2% with a bachelor degree and 5.0% with postgraduate qualifications, lower than 75% of areas nationally. A further 16.4% hold a vocational qualification. 7 schools serve the area, with 3,742 enrolment places and an average ICSEA of 939 against a national benchmark of 1,000. Qualifications come from the 2021 Census; school enrolments, ICSEA and results come from ACARA's current release.
Detail
Educational profiles across Dallas reflect lower tertiary completion rates, with 18.6% of residents holding higher education degrees compared to 37.0% across Greater Melbourne. Among tertiary graduates, bachelor degrees account for 12.2%, postgraduate qualifications represent 5.0%, and graduate diplomas comprise 1.4%. Meanwhile, technical and vocational qualifications are well established, with 26.2% of residents aged 15+ possessing vocational credentials, including 16.4% holding certificates and 9.8% with advanced diplomas. Current academic participation is pronounced throughout the community, with 38.5% of the population enrolled in an educational course. Broken down by stage, 13.9% attend primary schools, 9.9% are in secondary education, and 5.5% are undertaking tertiary studies.
Frequently Asked Questions - Education
Schools Detail
Public transport in Dallas reaches 20 stops on 2 routes, timetabled for about 1,600 services a week. The typical home sits about 320 m from its nearest stop. Buses carry the largest share of public transport commuters. Households keep an average of 1.3 vehicles. Stop and service counts are built from operators' published GTFS timetables and refresh with each timetable release; vehicle ownership is from the 2021 Census.
Detail
An evaluation of local public transport infrastructure identifies 20 active bus stops operating across Dallas. These stations are connected by 2 bus routes that generate 1,568 weekly transit trips. Access to the network is convenient, with residents residing an average of 323 meters from the closest stop. Given the suburban residential profile, outbound commuting is widespread: private motor vehicles account for 84% of work journeys, followed by 9% utilizing rail services. Household vehicle ownership averages 1.3 per dwelling. In addition, 11.3% of workers worked from home according to the 2021 Census, reflecting prevailing pandemic circumstances.
Across all servicing routes, schedule frequency averages 224 trips per day, providing approximately 78 weekly services per individual stop.
Frequently Asked Questions - Transport
Transport Stops Detail
71.9% of residents in Dallas report no long-term health condition, a less healthy profile than 79% of areas nationally. 10.3% need daily assistance with core activities, and 45.4% hold private health cover. The standardised death rate runs at 6.3 per 1,000 residents. Health conditions, assistance needs and insurance are 2021 Census measures; the death rate comes from current ABS releases.
Detail
Health and wellness metrics compiled by AreaSearch highlight significant local challenges, with higher mortality rates and an elevated prevalence of chronic illnesses, particularly among older demographics. Furthermore, private health insurance coverage is notably restricted, encompassing approximately 45% of the population (~3,094 people). This sits well behind the Greater Melbourne level of 56.7% and the national rate of 55.7%. Asthma and arthritis represent the two most prevalent diagnosed conditions locally, affecting 7.6% and 7.4% of the population respectively, while 71.9% of residents report having no chronic medical conditions compared to 72.6% across Greater Melbourne.
General health indicators across working-age cohorts are relatively standard. Residents aged 65 and over make up 13.6% of the population (928 people), lower than the 15.1% metropolitan benchmark, with senior health indicators presenting certain challenges despite ranking lower nationally than the overall community profile.
Frequently Asked Questions - Health
49.8% of Dallas residents were born overseas and 74.6% speak a language other than English at home, more culturally diverse than 95% of areas nationally. The largest reported ancestries are Australian (12.9%) and English (9.6%). Ancestry, language and country of birth are counted only by the Census, so these are 2021 figures.
Detail
Dallas demonstrates immense cultural diversity on a national scale, with 49.8% of residents born overseas and 74.6% using a non-English language at home. In terms of religious affiliation, Islam is the most widespread faith, practiced by 61.5% of local inhabitants, compared with 5.6% across Greater Melbourne. Regarding ancestral background based on parental birthplace, the largest segment in Dallas falls under Other at 48.6%, substantially exceeding the regional proportion of 14.6%. Australian ancestry accounts for 12.9% (below the 18.4% regional average) and English ancestry comprises 9.6% (compared to 20.1% regionally). Specific ethnic backgrounds display significant variation from metropolitan trends: Lebanese ancestry represents 9.4% in Dallas against 0.8% regionally, Vietnamese comprises 2.1% compared to 1.9%, and Samoan represents 1.5% versus 0.3%.
Frequently Asked Questions - Diversity
The median resident of Dallas is 32, younger than 90% of areas nationally. 29.9% of residents are aged 15 to 34. Age cohorts are not raw Census counts: the Census split is re-based to the latest ABS population estimates and state projections.
Detail
Dallas exhibits a comparatively youthful population structure relative to Greater Melbourne. AreaSearch estimates for August 2026 indicate that 38.4% of residents are aged 0 - 24, above the metropolitan level of 30.5%, while the 25 - 44 age cohort represents 27.0% locally against 32.1% across Greater Melbourne. The median age is estimated at 32 as at August 2026, mirroring the 2021 Census baseline, which sits 5 years younger than the Greater Melbourne median of 37 and below the national median of 38 recorded at that Census. Since the Census, the proportion of residents aged 65+ has increased from 12.6% to an estimated 13.6%.
Looking to 2041, the largest numerical gain is forecast in the 45 - 64 age bracket, adding 653 residents (45%) to reach 2,107, while the 65+ cohort is anticipated to expand most rapidly in proportional terms, growing 62% to 1,507 residents.
Frequently Asked Questions - Age
Data & MethodBoundaries, Sources & Method for Dallas
9 of 14 data sections on this page were updated within the last 12 months — the newest current to Oct 2026.
Everything is aggregated to the Suburb (SAL) boundary shown above, on a 2021 Census baseline. Only 3 sections — housing, households and cultural diversity — still wait on the 2026 Census.
The ledger — source, cycle and currency by section
| Section | Source & update cycle | Currency |
|---|---|---|
| Updated within the last 12 months 9 sections | ||
| Population | ABS, GNAF, Geoscience Australia Annual (ABS ERP) | Aug 2026 2 months ago headline measures · 2021 Census baseline |
| Re-based to the ABS Estimated Resident Population (June 2025 release) and updated with new dwellings from GNAF address data. Current to Aug 2026, with the 2021 Census supplying the small-area baseline. | ||
| Age profile | ABS, Geoscience Australia, State governments Annual | Aug 2026 2 months ago headline measures · 2021 Census baseline |
| Age cohorts are re-based to the latest ABS population estimates and state projections, current to Aug 2026. Each cohort is held as a Census baseline and a current estimate. | ||
| Development & approvals | ABS, GNAF Monthly (ABS approvals) | Aug 2026 2 months ago headline measures · Jul 2026 baseline |
| Property sales & rents | Valuer General, Rental Board, ABS Weekly sales, quarterly rents | Oct 2026 this month headline measures · Sep 2026 baseline |
| Sales from the state Valuer General register, refreshed weekly, and rents from quarterly rental bond lodgements. Both are read live each time this page loads, current to Oct 2026. | ||
| Infrastructure projects | Infrastructure Australia, State agencies, Local governments Daily | May 2026 5 months ago all 1 projects tracked here |
| Project pipeline maintained continuously from Infrastructure Australia, state agencies, local government and public announcements. Records are added and revised daily; this area was last updated May 2026. | ||
| Employment | ABS, DEWR, JSA Quarterly (ABS SALM) | Mar 2026 7 months ago headline measures · 2021 Census baseline |
| Unemployment and labour force from ABS Small Area Labour Markets, current to Mar 2026. The growth outlook applies Department of Employment (now Jobs and Skills Australia) forecasts for all 19 industry divisions to the local industry mix, so it measures sector composition rather than local expansion and makes no allowance for population growth. Job demand comes from the same agency via its Internet Vacancy Index; industry and occupation structure from the 2021 Census. | ||
| Education | ABS, ACARA Annual (ACARA) | Sep 2026 last month headline measures · 2021 Census baseline |
| Transport | ABS, State Transport Departments Each timetable release | Jul 2026 3 months ago headline measures · 2021 Census baseline |
| Services & amenities | Provider directories, ACECQA Continuous | Sep 2026 last month all 14 measures |
| Annual and financial-year sources 2 sections | ||
| Income | ABS, ATO Annual (ATO) | FY 2023 3 years ago headline measures · 2021 Census baseline |
| ATO taxable income statistics for FY 2023, indexed forward using the Wage Price Index. Census household income provides the distribution detail. | ||
| Health | ABS, ATO Annual | 2024 2 years ago headline measures · 2021 Census baseline |
| Census-measured — next update: 2026 Census 3 sections No more current small-area source exists for these, so they are labelled as Census-measured rather than implied to be current. | ||
| Housing | ABS 5-yearly (Census) | 2021 Census next update 2026 all 30 measures |
| Households | ABS 5-yearly (Census) | 2021 Census next update 2026 all 18 measures |
| Cultural diversity | ABS, Geoscience Australia 5-yearly (Census) | 2021 Census next update 2026 all 44 measures |
"Currency" is the most recent release feeding that section. Where the Census supplies the structural baseline underneath a current headline figure, the row says so.
How the numbers are built
Population
The Census provides the small-area baseline, aggregated from mesh blocks to this boundary. It is then re-based to the ABS Estimated Resident Population (June 2025 release), and new dwellings built since Census night are counted from address data — 37 validated new addresses here. The headline figure is therefore a current estimate for Aug 2026, not a 2021 count (6,762 at the 2021 Census → 6,824 now). Annual growth rates are compound (CAGR), not simple averages.
Age profile
Cohort shares are not raw Census counts. Every cohort is held as a pair — the Census baseline and a current estimate — and the split is re-based using ERP and state population projections, current to Aug 2026. Median age is the Census median plus modelled change since. Charts that show both are labelled "2021 Census vs Current Estimate".
Property sales
Sourced from the state valuation authority's sales register — current, not Census, and refreshed weekly. Medians are calculated from settled transactions in the period shown; periods with very low transaction counts are flagged or suppressed, because a handful of sales can move a median substantially.
Rents
Derived from state rental bond lodgement data, by dwelling type and bedroom count. Bonds are lodged at the start of a new tenancy, so this reflects new lettings, not the whole rented stock.
Development & infrastructure
Building approvals come from current ABS releases; development applications are collected from council and state planning portals; the infrastructure pipeline is compiled from Infrastructure Australia and local government sources. Applications are matched to this boundary by address or coordinates, so very recent lodgements may not yet appear.
Employment & income
Industry and occupation structure comes from the Census, but the headline labour-market indicators do not. Unemployment and labour force are derived from ABS Small Area Labour Markets (quarterly). The employment outlook applies Department of Employment forecasts for all 19 industry divisions to this area's own industry mix (the agency is now Jobs and Skills Australia), as does the Internet Vacancy Index used for job demand. Because it is weighted on industry composition alone, that outlook carries no allowance for local population growth — in fast-growing areas the real rise in local jobs will typically be higher. Income combines Census household income with ATO taxable-income statistics for FY 2023, indexed forward using the Wage Price Index.
Education, transport & amenities
School enrolments, ICSEA and performance come from ACARA's current release, not the Census. Public transport stops and service frequency are derived from GTFS timetable feeds published by state transport departments. Services and amenities are proximity and count scores built from provider directories, refreshed on their own cycle. The Census contributes only the travel-to-work and qualification measures.
Rankings and benchmarks. Where we rank this area, the comparison set is every area of the same boundary type — suburbs against suburbs, SA2s against SA2s. Benchmarks compare this area against its greater capital city region and the national figure for the same measure and period.
Limits worth knowing. Small areas carry larger error margins, and the ABS introduces small random adjustments to Census counts to protect confidentiality — so totals may not sum exactly. Estimates re-based from regional data describe the area's expected trajectory, not a direct count of it. Figures are indicative for research and are not financial, planning or valuation advice.
Cross-check us. The Census baseline for this boundary is at ABS 2021 Census QuickStats (SAL20702). QuickStats reports 2021 only — the figures on this page are more current wherever the ledger shows a later date.