Chart Color Schemes
This analysis uses Suburbs and Localities (SAL) boundaries, which can materially differ from Statistical Areas (SA2) even when sharing the same name.
SAL boundaries are defined by Australia Post and the Australian Bureau of Statistics to represent commonly-known suburb names used in postal addresses.
Statistical Areas (SA2) are designed for census data collection and may combine multiple suburbs or use different geographic boundaries. For comprehensive analysis, consider reviewing both boundary types if available.
est. as @ -- *
2021 Census | -- people


The median house price in St Clair (Penrith - NSW) is $1.22m, with units at $1.01m. House values have moved 7.5% a year compounded over five years.
Curious about local property values? Filter the chart to assess the volume and appreciation (including resales) trends and regional comparisons, or scroll to the map below view this information at an individual property level.
Find a Recent Sale

Sales Detail
St Clair (Penrith - NSW) has an estimated 20,556 residents, up from 19,942 at the 2021 Census — a change of 614 people, or 3.1%. That puts 2,855 residents on each square kilometre. Population is estimated from ABS Estimated Resident Population releases and GNAF address data, re-based from the 2021 Census and updated annually.
Detail
According to AreaSearch evaluations combining regional ABS population releases with 34 validated new addresses recorded since the Census, the suburb of St Clair (Penrith - NSW) has an estimated population of approximately 20,556 as of Aug 2026. This represents an addition of 614 residents (3.1%) compared to the 2021 Census count of 19,942 people. These figures stem from an estimated resident population (ERP) of 20,529 established through the ABS June 2025 data update alongside the subsequent address additions. Demographically, this yields a population density of 2,855 persons per square kilometer, placing St Clair in the top quartile of locations evaluated across Australia.
The suburb's post-census increase of 3.1% trails the wider SA3 area's 5.4% expansion by only 2.3 percentage points, highlighting steady growth dynamics. Recent population gains were predominantly underpinned by natural increase, which accounted for roughly 61.0% of net additions. Population modelling for the suburb of St Clair (Penrith - NSW) utilizes 2024 ABS/Geoscience Australia SA2 projections with a 2022 base year, complemented by 2022 NSW State Government SA2 series (2021 base) where required, alongside age-bracket growth trajectories applied from 2032 to 2041. Under these projections, the suburb is expected to experience a mild contraction in overall numbers, decreasing by 171 persons by 2041. In contrast to this overall trend, particular age segments will expand, most notably the 75 to 84 cohort with a projected gain of 614 people.
Frequently Asked Questions - Population
234 new dwellings have been approved in St Clair (Penrith - NSW) over the past five years, an average of 46 a year. That is 2.7 approvals per 1,000 residents. Of the 54 dwellings approved in the latest reporting year, 80% were detached houses and the rest townhouses or apartments. Approvals are currently running at an annualised 79, running ahead of that longer-run average. Figures come from ABS building approvals aggregated to this Suburb (SAL) boundary and are updated monthly as the ABS releases them.
Detail
Analysis of ABS building approvals by AreaSearch indicates that St Clair averages approximately 46 approved dwellings each year, totaling 234 residential approvals over the preceding 5 financial years (between FY-21 and FY-25), with 79 recorded to date in FY-25. Because only an average of 1 people moved into the suburb per newly constructed dwelling over the past 5 financial years (between FY-21 and FY-25), local residential construction has kept pace with or exceeded demographic demand, expanding options for purchasers while creating headroom for above-forecast population expansion. Furthermore, the mean construction value for new dwellings is $319,000, sitting beneath regional benchmarks to offer relatively attainable price points.
Non-residential activity remains subdued, with commercial approvals totaling $2.3 million across the current financial year. St Clair generates roughly 57% of Greater Sydney's per capita building approval volume and sits at the 45th percentile nationally, a level indicative of an established market with fewer new-build alternatives that helps support demand for existing housing stock. These below-average national figures highlight the suburb's mature urban footprint and potential planning constraints. Compositionally, recent approvals consist of 80.0% detached houses and 20.0% attached dwellings, maintaining a family-friendly, low-density environment for space-seeking buyers. While detached homes still comprise 98.0% of existing stock, this 20.0% attached component shows an evolving response to land availability constraints and shifting lifestyle preferences. The ratio of residents to dwelling approvals stands at approximately 338 people per dwelling approval. With demographic forecasts pointing toward stable or slightly contracting numbers, St Clair is poised to experience diminished pressure on its residential stock, providing favorable buying conditions.
Frequently Asked Questions - Development
Development applications around St Clair (Penrith - NSW)
Loading development applications…
| Lodged | Address | Description | Type | Distance | Status |
|---|
SOURCE: Planning portals and council registers, compiled by AreaSearch. Distance & bearing measured from the suburb midpoint.
AreaSearch tracks 4 current infrastructure and development projects inside St Clair (Penrith - NSW), worth an estimated $2.51 billion. A further 66 sit in the immediately surrounding suburbs, taking the tracked pipeline within reach of the area to $73 billion. 19 are already under construction and 29 are due for completion within three years. The pipeline spans residential development, transport & logistics and communities, precincts & urban renewal. Records are compiled from Infrastructure Australia, state agencies, council planning portals and public announcements, reviewed and updated daily, then ranked by proximity, construction stage, completion horizon and project scale.
Detail
Local growth and property performance are heavily shaped by strategic infrastructure delivery and major capital works. AreaSearch has identified 8 key initiatives influencing the surrounding district, prominent among which are the Erskine Park Employment Area (EPEA) Expansion, the M12 Motorway, Western Sydney Aerotropolis Infrastructure and Development, and the Stage 1 Mamre Road Upgrade from the M4 to Erskine Park Road.
Professional plan users can use the search below to filter and access additional projects.
INFRASTRUCTURE SEARCH
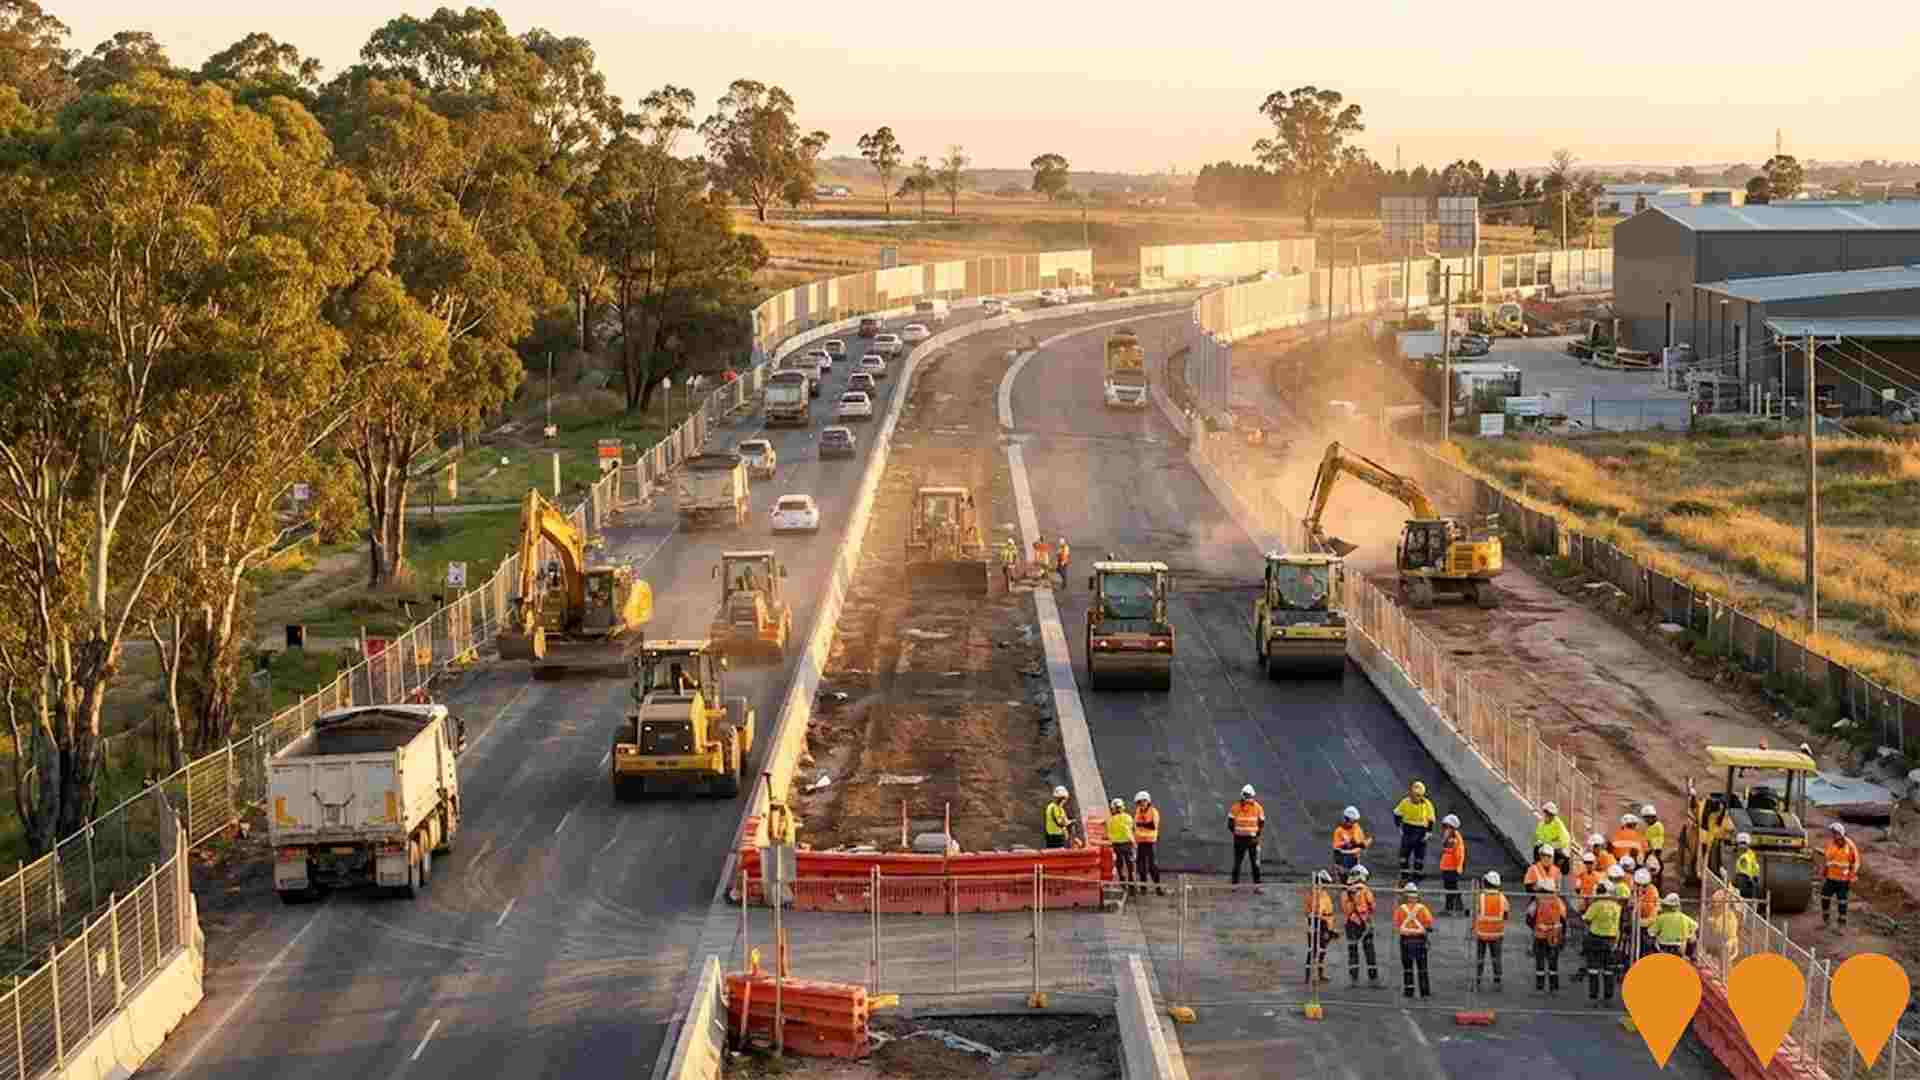
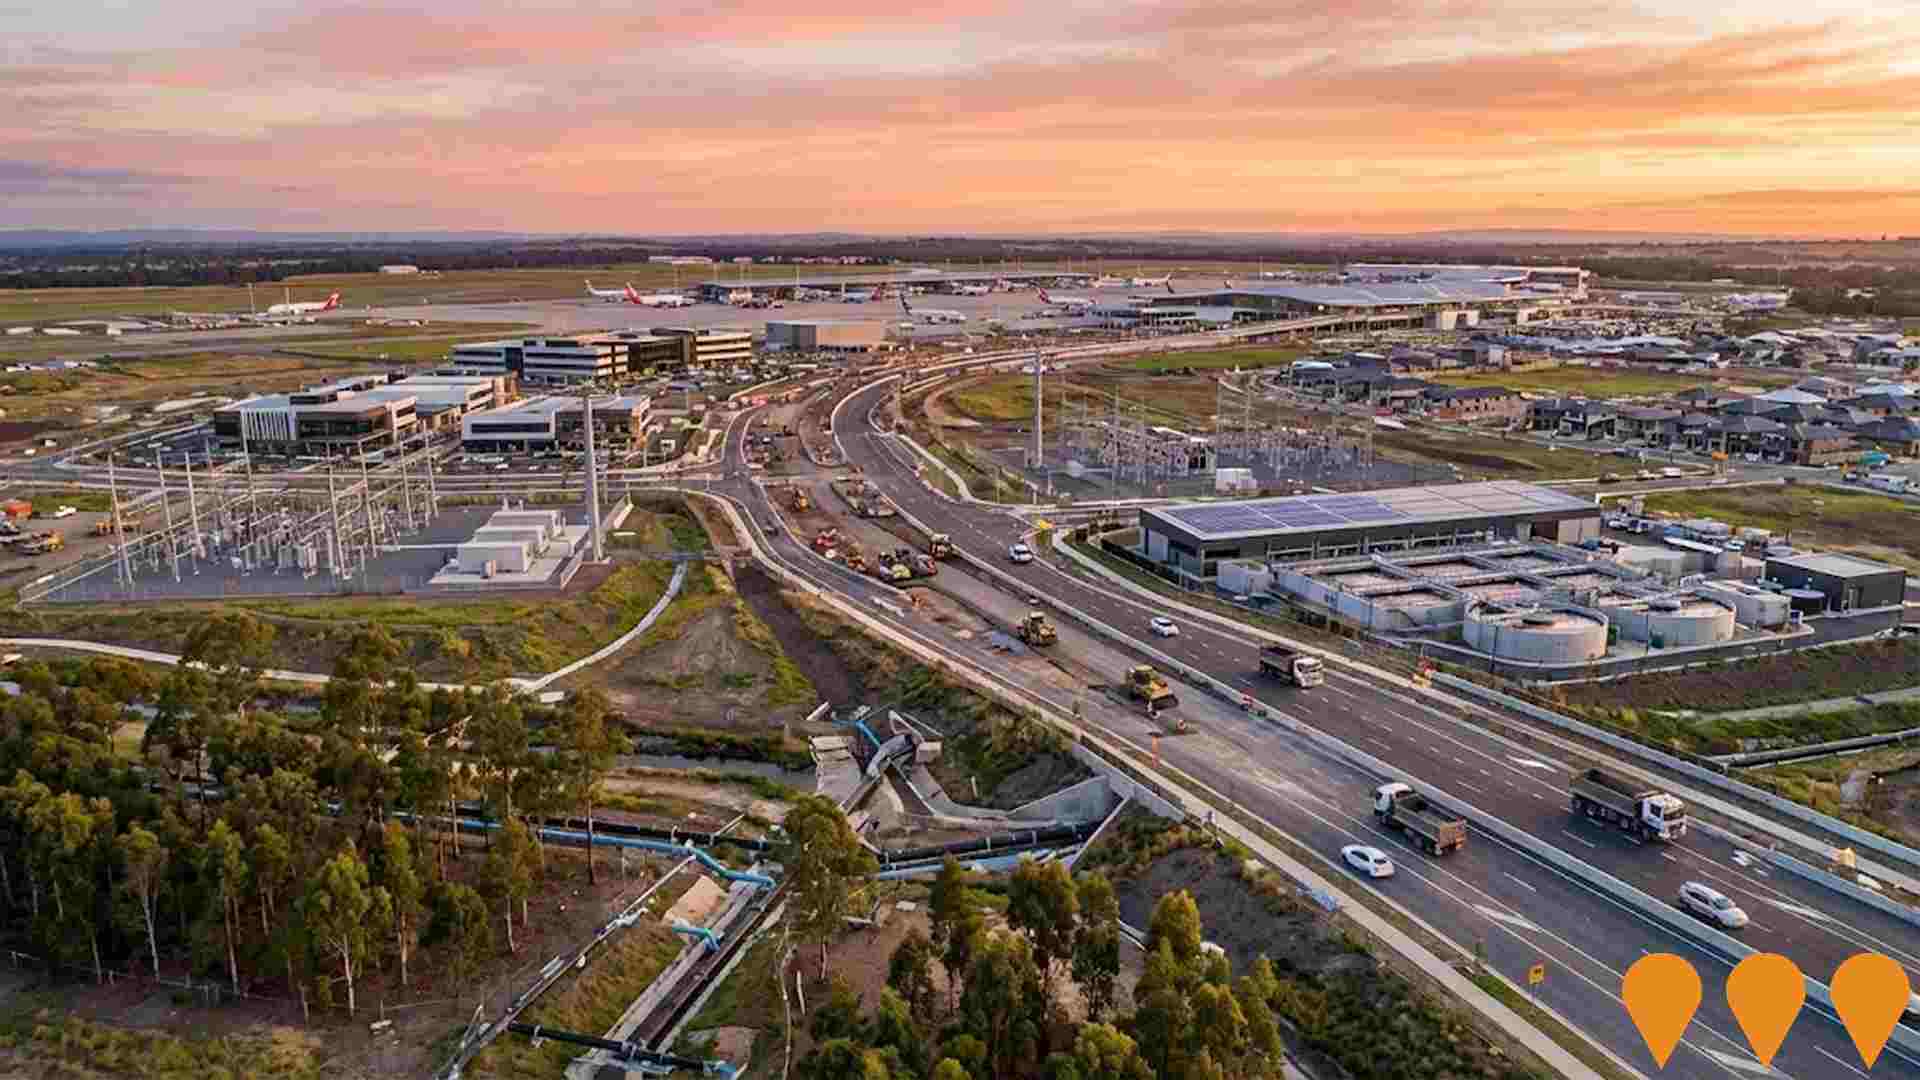
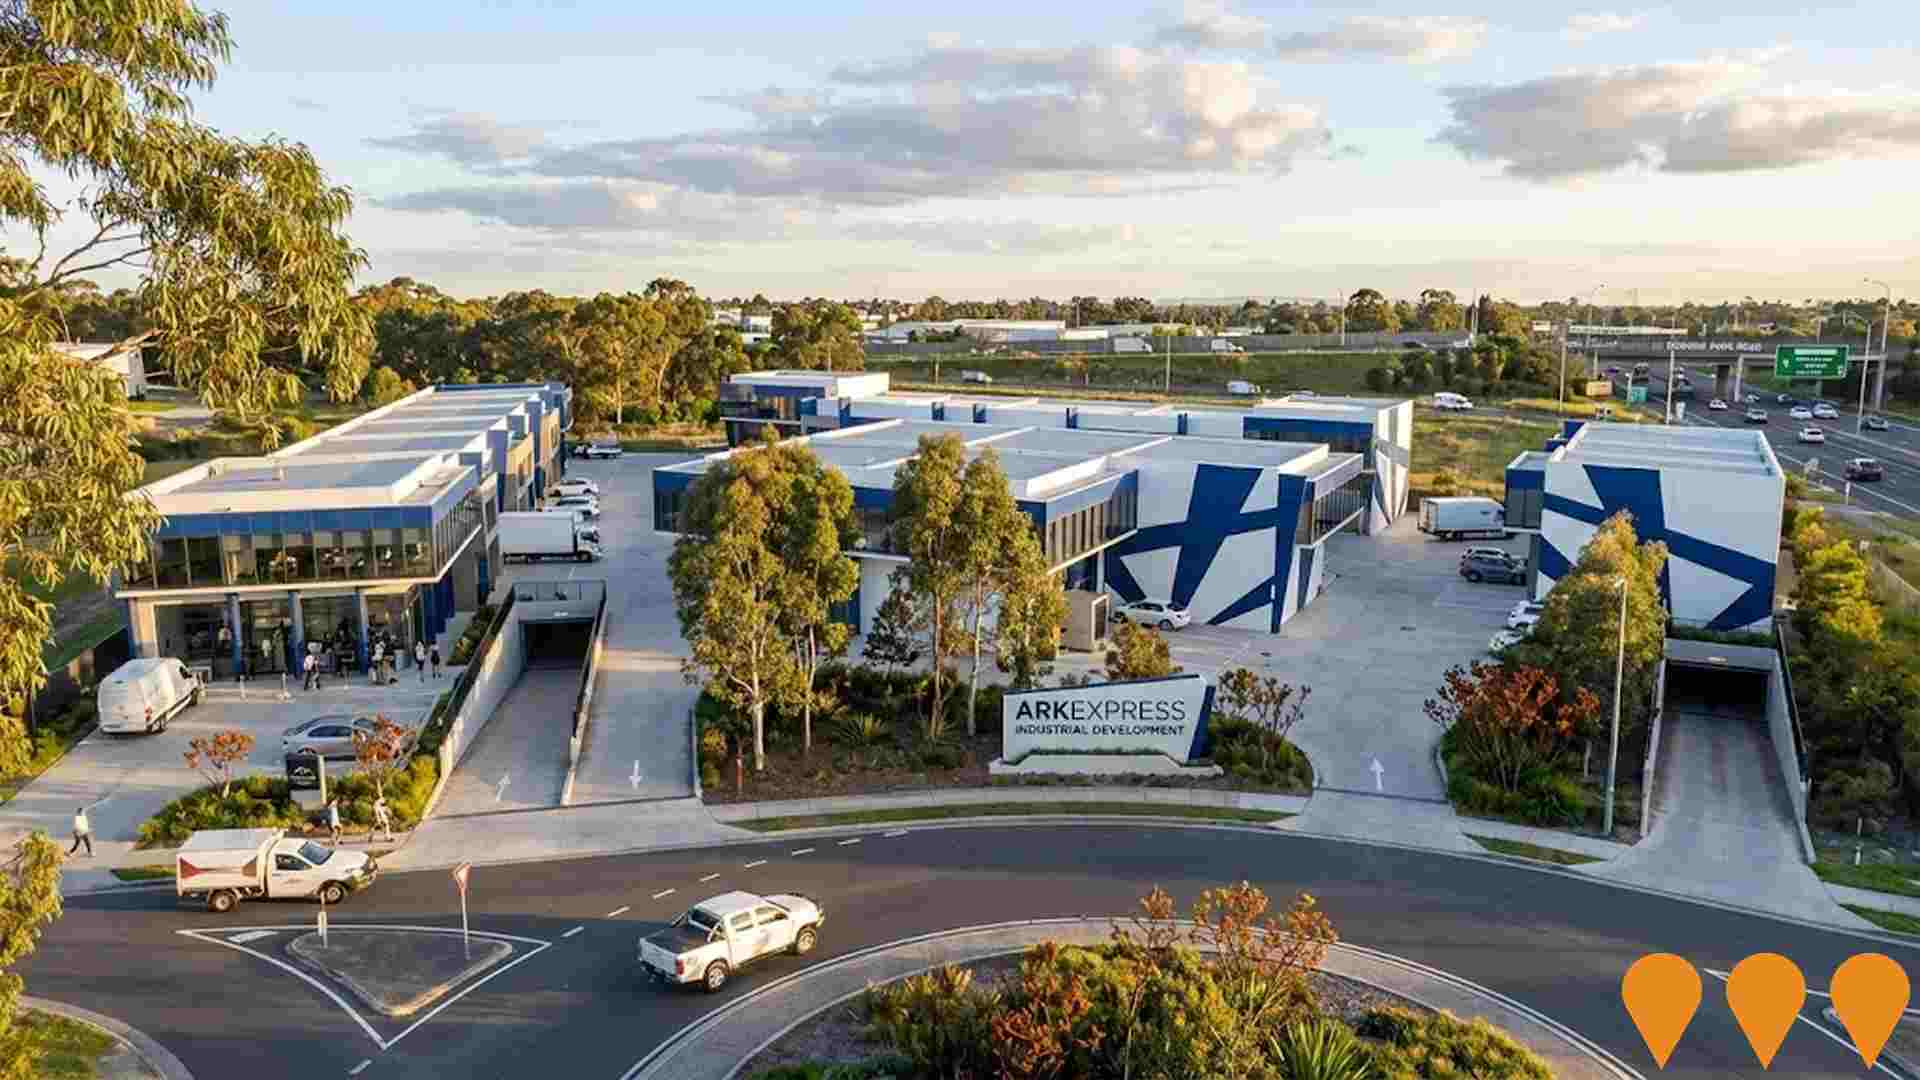
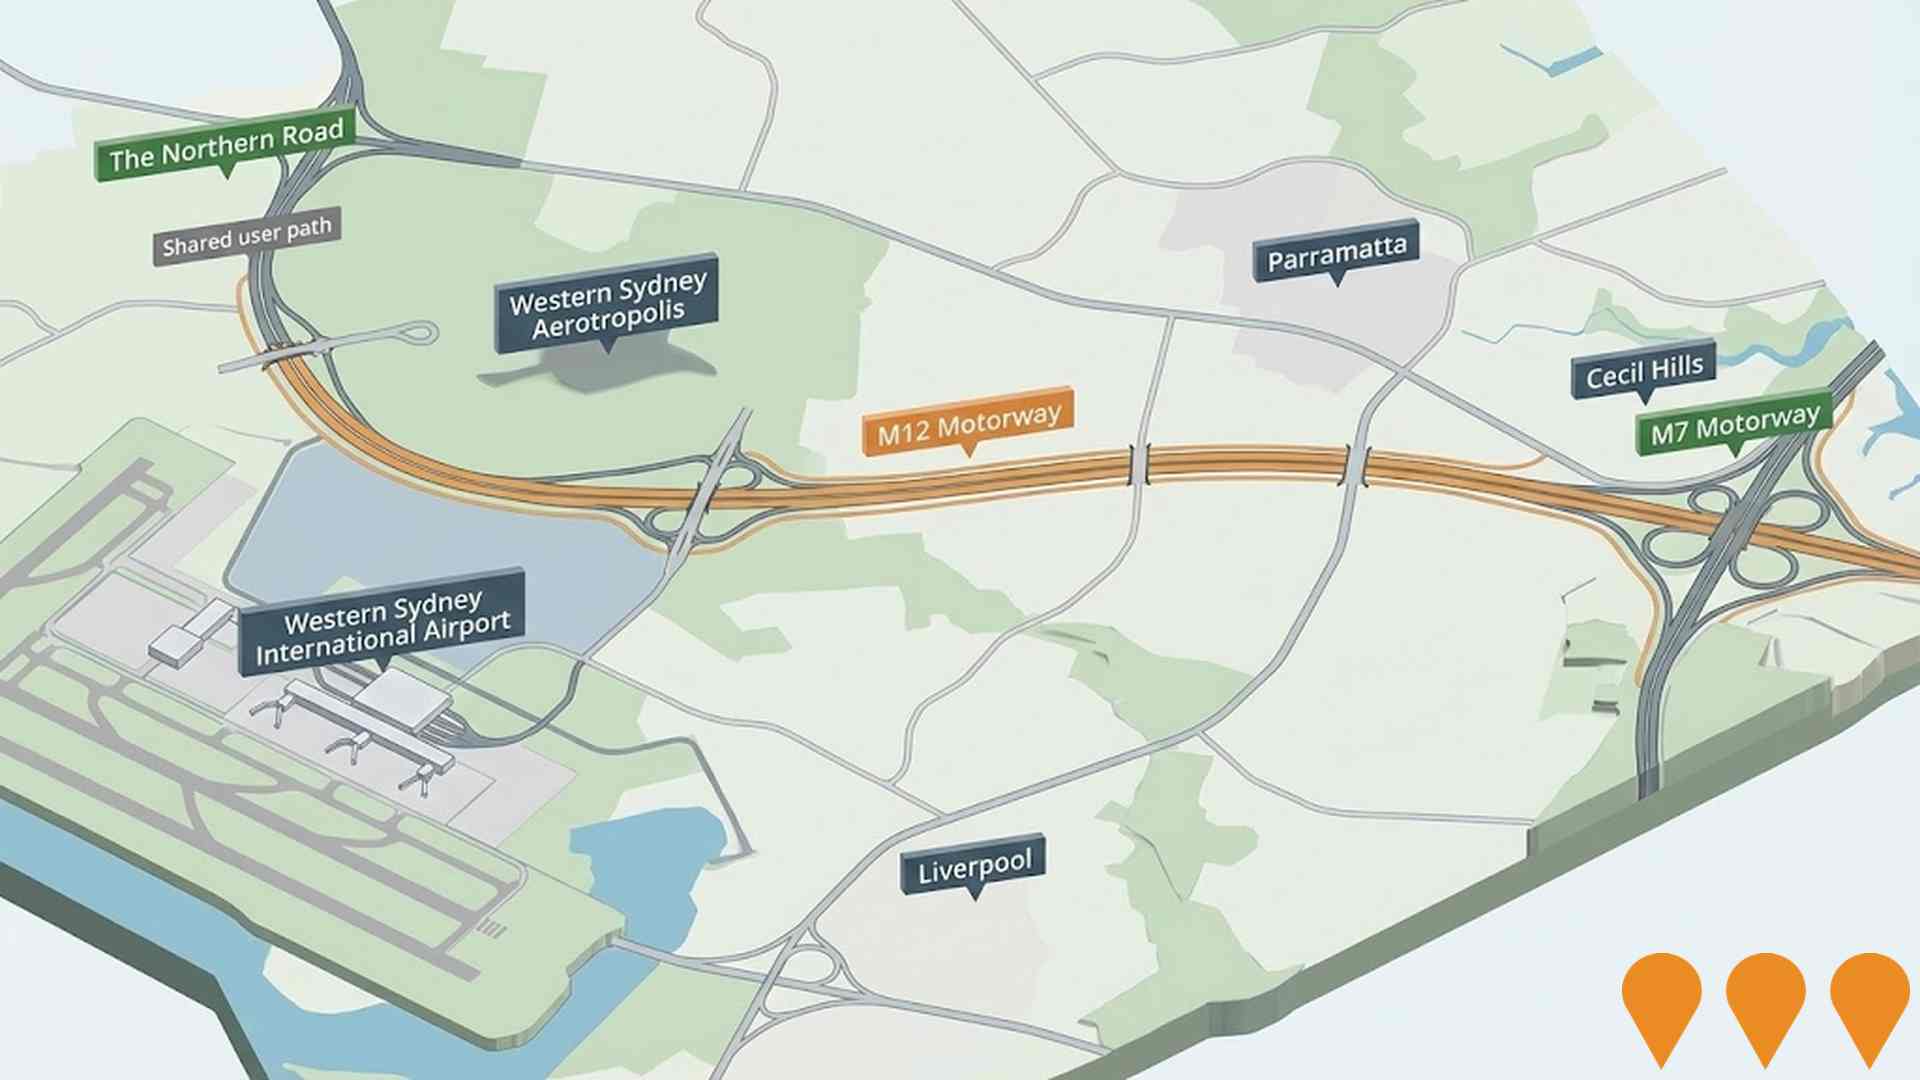
 Denotes AI-based impression for illustrative purposes only, not to be taken as definitive under any circumstances. Please follow links and conduct other investigations from the project's source for actual imagery. Developers and project owners wishing us to use original imagery please Contact Us and we will do so.
Frequently Asked Questions - Infrastructure
Erskine Park Employment Area Expansion
Major Western Sydney industrial and logistics employment area within the Erskine Park / Western Sydney Employment Area precinct. The precinct includes Goodman assets such as Erskine Park Industrial Estate, Westpark Industrial Estate and Interlink Distribution Centre, with modern warehouse, office, distribution and light industrial space close to the M4 and M7 motorways. Most land is established or committed, while remaining activity is focused on leasing, fitout, subdivision and new warehouse facilities, including recent state significant development activity at Interlink Distribution Centre.

Mamre Road Upgrade - M4 Motorway to Erskine Park Road (Stage 1)
Stage 1 of the Mamre Road upgrade widens about 3.8 km of Mamre Road between the M4 Motorway at St Clair and Erskine Park Road at Erskine Park to a four-lane divided road with a wide central median, allowing future expansion to six lanes if demand requires. The scope covers upgrades to six intersections (including Banks Drive, Solander Drive, Luddenham Road and Erskine Park Road), two large structural culverts and extensive drainage works to better withstand flooding, a new shared path along the eastern side of the corridor, reinstated bus stops near Banks Drive, permanent noise walls at St Clair, major utility relocations and improved access for Mamre House and the Erskine Park Rural Fire Service.Mamre Road is a critical freight and commuter connection between the M4 Motorway, the Western Sydney Employment Area and the Western Sydney International (Nancy-Bird Walton) Airport precinct, carrying about 20,000 vehicles a day with volumes forecast to double by 2041. Early works began in September 2024 and major construction commenced in October 2024. Delivery contractor Seymour Whyte Constructions holds a contract valued at $150-200 million within the $290 million Stage 1 budget, part of $1 billion in combined Federal and NSW funding across both Mamre Road stages. As at May 2026 construction is well advanced, with traffic switched onto the newly built western carriageway from March 2026 while work continues on the eastern side. Transport for NSW now advises completion in 2028. Stage 2, between Erskine Park Road and Kerrs Road at Kemps Creek, is progressing separately through planning.
Western Sydney Aerotropolis Infrastructure and Development
An 11,200-hectare economic and urban transformation precinct on the doorstep of the new Western Sydney International Airport, supported by over $28 billion in combined government investment and rapidly climbing private sector commitments. Anchor developments include Bradfield City Centre, the Advanced Manufacturing Readiness Facility, the toll-free M12 Motorway, and major transport, water, and public open space infrastructure projects targeting over 100,000 long-term jobs.
ArkExpress Industrial Development
17 industrial units plus ancillary cafe development approved for corner of Lenore Drive and Erskine Park Road. Units range from 284sqm to 625sqm plus 80sqm cafe. Originally proposed 29 units, reduced to 17 larger units. Ideally located adjacent to Erskine Park link road connecting to M7 motorway.
Distribution Dr, Orchard Hills
Plans to expand food manufacturing facility with warehouse area, office space, and 160 additional car parking spaces.
St Marys Station Upgrade and Metro Integration
A major transport interchange project integrating the existing T1 Western Line with the new Sydney Metro Western Sydney Airport line. Key features include a new underground metro station, a 55-metre-long pedestrian concourse and footbridge via Harris and Hobart Streets, a northern pedestrian plaza, and a multi-storey commuter car park with over 250 additional spaces. The 23-kilometre metro line will connect St Marys to the new Western Sydney International (Nancy-Bird Walton) Airport and Bradfield City Centre, with the metro expected to open in mid-to-late 2027 following delays from the original late 2026 target.A free interim bus service between St Marys and the airport was announced by the NSW Government in January 2026 to bridge the gap. The project is a key commitment under the Western Sydney City Deal and a vital gateway for the Western Parkland City.
Orchard Hills Switching Substation
A new 132kV high-voltage switching station providing the backbone connection between underground transmission feeders and major local substations to power Western Sydney Aerotropolis assets including Sydney Metro (Western Sydney Airport) and nearby precincts.
ESR Erskine Park Logistics Estate
A prime multi-unit logistics estate on a 7.7-hectare freehold site, delivering over 40,000sqm of gross lettable area. The facility features a 14.6m ridge height, 24/7 operational capability, and flexible warehouse designs targeting a 5 Star Green Star rating with significant rooftop solar infrastructure.

10,912 residents of St Clair (Penrith - NSW) are employed, from a labour force of 11,289. Unemployment sits at 3.3%, with participation at 68.1%. Weighted for its industry mix, the area's sectors are forecast to grow about 6.1% nationally over five years. That reflects industry composition only and makes no allowance for local population growth. The working-day population is estimated at 15,974, about 78% of the resident population, so more people leave the area for work than travel in. Unemployment and labour force come from ABS Small Area Labour Markets, updated quarterly; the industry and occupation profile is from the 2021 Census.
Detail
St Clair features a capable resident labor pool characterized by strong representation in manufacturing and industrial trades, alongside a low unemployment rate of 3.3% according to AreaSearch aggregations. As of March 2026, employed residents total 10,912, with the jobless rate tracking 0.8% below the Greater Sydney figure of 4.1% and workforce participation closely aligning with the broader metropolitan level of 68.9%. Census records also indicate that 29.2% of workers worked from home, a metric influenced by Covid-19 restrictions in place at the time. A significant portion of working residents are employed across health care & social assistance, construction, and retail trade.
Transport, postal & warehousing represents a major local specialization, capturing a workforce share 1.9 times the regional benchmark. Conversely, professional & technical roles account for only 4.3% of the resident workforce compared to 11.5% across the broader region. The balance between local jobs and resident workers indicates that St Clair serves primarily as a residential dormitory suburb with limited local employment capacity. AreaSearch assessment of ABS and SALM series shows that in the 12 months to March 2026, St Clair experienced a 3.8% contraction in its labor force and a 4.0% reduction in employed residents, resulting in a 0.2 percentage point uptick in the unemployment rate. Over the same timeframe, Greater Sydney recorded a 1.9% rise in employment, a 1.9% expansion in the labor force, and a slight decrease in joblessness. Looking ahead, Jobs and Skills Australia's Mar-26 projections forecast national employment growth of 6.6% over five years and 13.7% over ten years. Weighting these sectoral trajectories against St Clair's specific occupational makeup suggests local employment could expand by 6.1% over five years and 12.7% over ten years, assuming uniform industry trends across regions.
Frequently Asked Questions - Employment
Median household income in St Clair (Penrith - NSW) is $2,067 a week (about $107,000 a year), with median personal income at $849 a week. ATO records put median taxable income at $56,872 a year against an average of $63,145. Household income is from the 2021 Census; taxable income is from ATO Taxation Statistics for the latest financial year available, indexed forward using the ABS Wage Price Index.
Detail
Taxation records from the ATO for financial year 2023 aggregated by AreaSearch place St Clair's earning benchmarks below broader metropolitan figures. Median taxable income across the suburb sits at $56,872 against Greater Sydney's $60,817, while the mean income of $63,145 compares with $83,003 regionally. Factoring in subsequent Wage Price Index expansion of 10.32% since financial year 2023, updated estimates as of March 2026 reach approximately $62,741 for median earnings and $69,662 on average. In the 2021 Census, local household, family, and individual incomes placed near the 64th percentile nationwide, with 38.6% of residents (7,934 individuals) earning between $1,500 - 2,999 compared to 30.9% across the region.
Housing costs account for 16.0% of income, leaving disposable earnings at the 69th percentile, while the suburb ranks in the 4th decile on the SEIFA income index.
Frequently Asked Questions - Income
St Clair (Penrith - NSW) had 6,327 occupied dwellings at the 2021 Census, 99% detached houses and 1% apartments. 47% are owned with a mortgage, 22% rented and 31% owned outright. At that Census the median rent was $440 a week and the median mortgage repayment $2,167 a month, a total housing cost higher than 76% of areas nationally. Rent absorbs 21.3% of household income here and mortgage repayments 24.2%. Dwelling stock, tenure and housing costs are 2021 Census measures — the only source that counts dwellings at this boundary size.
Detail
According to the most recent Census, St Clair's housing landscape is overwhelmingly dominated by standalone houses, which account for 98.5% of residences alongside 1.4% other dwellings such as apartments and semi-detached properties, contrasting with Sydney metro proportions of 55.9% houses and 44.1% other dwellings. Outright home ownership is notably higher than the metropolitan standard at 31.2%, with 47.1% of homes being purchased under a mortgage and 21.7% occupied by tenants. Median monthly mortgage obligations were $2,167 compared to $2,427 across Sydney metro, while median weekly rents stood at $440 compared to $470 across the wider metropolis.
On a national scale, local monthly mortgage repayments exceed the Australian average of $1,863, and weekly rents surpass the national benchmark of $375.
Frequently Asked Questions - Housing
St Clair (Penrith - NSW) counted 6,327 households at the 2021 Census, averaging 3.0 people each. 43% are couples with children, more than in 86% of areas nationally, against 25% couples without children. 14% of households are people living alone, and families average 1.8 children. Household and family composition is measured only by the Census, so these are 2021 figures.
Detail
Families make up 84.1% of all households in the community, comprising couples with children at 43.3%, couples without children at 25.1%, and single parent households at 14.8%. Non-family living arrangements account for the remaining 15.9%, split between single-person households at 14.2% and shared group dwellings at 1.7%. The typical household consists of 3.0 people, exceeding the Greater Sydney average of 2.7.
Frequently Asked Questions - Households
17.1% of adults in St Clair (Penrith - NSW) hold a university qualification, including 12.7% with a bachelor degree and 3.3% with postgraduate qualifications. A further 27.5% hold a vocational qualification. 6 schools serve the area, with 2,652 enrolment places and an average ICSEA of 981 against a national benchmark of 1,000. Qualifications come from the 2021 Census; school enrolments, ICSEA and results come from ACARA's current release.
Detail
Higher education qualifications present an area for community development, with 17.1% of residents holding university credentials compared to the Greater Sydney benchmark of 38.0%. Among degree holders, bachelor degrees represent 12.7%, postgraduate awards comprise 3.3%, and graduate diplomas make up 1.1%. Vocational qualifications are particularly prevalent, with 37.6% of residents aged 15+ possessing vocational credentials, including 10.1% with advanced diplomas and 27.5% holding certificates. A substantial 29.6% of local residents are actively engaged in study, encompassing 10.9% attending primary schools, 8.4% enrolled in secondary education, and 4.0% undertaking tertiary studies.
Frequently Asked Questions - Education
Schools Detail
Public transport in St Clair (Penrith - NSW) reaches 102 stops on 33 routes, timetabled for about 1,300 services a week. The typical home sits about 210 m from its nearest stop. Buses carry the largest share of public transport commuters. Households keep an average of 1.8 vehicles. Stop and service counts are built from operators' published GTFS timetables and refresh with each timetable release; vehicle ownership is from the 2021 Census.
Detail
The local public transit network includes 102 operational bus stops across St Clair, supported by 33 routes delivering a combined total of 1,332 weekly passenger trips. Access to transit is convenient, with residents situated an average of 213 meters from their closest stop. Due to the area's residential role, outward commuting dominates, with private vehicles accounting for 91% of transport journeys and households maintaining an above-average rate of 1.8 vehicles per dwelling. Meanwhile, 29.2% of residents were recorded working from home in the 2021 Census, reflecting pandemic-related working arrangements. Public transport operations provide an average frequency of 190 trips per day across all available routes, translating to roughly 13 weekly trips for each stop.
The accompanying mapping displays the 100 closest stops relative to the centerpoint of the suburb.
Frequently Asked Questions - Transport
Transport Stops Detail
70.7% of residents in St Clair (Penrith - NSW) report no long-term health condition. 5.3% need daily assistance with core activities, and 51.9% hold private health cover. The standardised death rate runs at 5.0 per 1,000 residents. Health conditions, assistance needs and insurance are 2021 Census measures; the death rate comes from current ABS releases.
Detail
General health indicators in St Clair align closely with national standards in terms of mortality and chronic disease prevalence, displaying standard incidence rates among the broader community alongside slightly elevated rates within older age demographics. Private health insurance coverage covers approximately 52% of the population (~10,672 people), trailing the average SA2 area and comparing against 59.9% across Greater Sydney. Asthma and arthritis represent the two most widespread medical conditions, diagnosed in 8.0% and 7.4% of the population respectively, while 70.7% of residents reported having no long-term medical conditions compared to 74.6% across Greater Sydney.
Health outcomes remain standard across working-age residents. Seniors aged 65 and over account for 16.5% of the local population (3,391 people), presenting distinct health needs that nevertheless track beneath broader national health challenge rankings.
Frequently Asked Questions - Health
28.3% of St Clair (Penrith - NSW) residents were born overseas and 25.6% speak a language other than English at home. The largest reported ancestries are Australian (23.2%) and English (20.4%). Ancestry, language and country of birth are counted only by the Census, so these are 2021 figures.
Detail
Cultural diversity in St Clair is pronounced relative to most markets, with 28.3% of the community born outside Australia and 25.6% speaking a language other than English at home. Christianity is the predominant faith, practiced by 63.6% of local residents compared to 49.2% throughout Greater Sydney. The primary reported ancestries across St Clair are Australian at 23.2% (exceeding the regional level of 17.8%), English at 20.4%, and Other backgrounds representing 13.8%. Specific cultural communities show notable concentration relative to regional norms, including residents of Filipino heritage at 4.2% (vs 2.0% regionally), Maltese ancestry at 3.2% (vs 1.0%), and Samoan background at 1.8% (vs 0.5%).
Frequently Asked Questions - Diversity
The median resident of St Clair (Penrith - NSW) is 36. 27.0% of residents are aged 15 to 34. Age cohorts are not raw Census counts: the Census split is re-based to the latest ABS population estimates and state projections.
Detail
The demographic profile leans younger, with AreaSearch estimates for August 2026 identifying 33.7% of the population in the 0 - 24 age bracket compared to 30.4% across Greater Sydney, while residents aged 25 - 44 account for 27.3% compared to 31.4% regionally. The estimated median age of 36 as at August 2026 matches the 2021 Census baseline and sits 1 year below the Greater Sydney median of 37 recorded at that Census. Since the Census, the cohort aged 65+ has expanded from 12.8% to an estimated 16.5%, driven by the 65 to 74 group rising from 9.3% to 10.9% while the 55 to 64 band declined from 13.6% to 11.2%, reflecting an aging established population base.
Projections through 2041 indicate that residents aged 65 and over will experience the strongest expansion, adding 771 residents (23%) to reach 4,163, whereas younger adult and youth cohorts are expected to contract.
Frequently Asked Questions - Age
Data & MethodBoundaries, Sources & Method for St Clair (Penrith - NSW)
9 of 14 data sections on this page were updated within the last 12 months — the newest current to Sep 2026.
Everything is aggregated to the Suburb (SAL) boundary shown above, on a 2021 Census baseline. Only 3 sections — housing, households and cultural diversity — still wait on the 2026 Census.
The ledger — source, cycle and currency by section
| Section | Source & update cycle | Currency |
|---|---|---|
| Updated within the last 12 months 9 sections | ||
| Population | ABS, GNAF, Geoscience Australia Annual (ABS ERP) | Aug 2026 last month headline measures · 2021 Census baseline |
| Re-based to the ABS Estimated Resident Population (June 2025 release) and updated with new dwellings from GNAF address data. Current to Aug 2026, with the 2021 Census supplying the small-area baseline. | ||
| Age profile | ABS, Geoscience Australia, State governments Annual | Aug 2026 last month headline measures · 2021 Census baseline |
| Age cohorts are re-based to the latest ABS population estimates and state projections, current to Aug 2026. Each cohort is held as a Census baseline and a current estimate. | ||
| Development & approvals | ABS, GNAF Monthly (ABS approvals) | Aug 2026 last month headline measures · Jun 2026 baseline |
| Property sales & rents | Valuer General, Rental Board, ABS Weekly sales, quarterly rents | Sep 2026 this month all 21 measures |
| Sales from the state Valuer General register, refreshed weekly, and rents from quarterly rental bond lodgements. Both are read live each time this page loads, current to Sep 2026. | ||
| Infrastructure projects | Infrastructure Australia, State agencies, Local governments Daily | May 2026 4 months ago all 4 projects tracked here |
| Project pipeline maintained continuously from Infrastructure Australia, state agencies, local government and public announcements. Records are added and revised daily; this area was last updated May 2026. | ||
| Employment | ABS, DEWR, JSA Quarterly (ABS SALM) | Mar 2026 6 months ago headline measures · 2021 Census baseline |
| Unemployment and labour force from ABS Small Area Labour Markets, current to Mar 2026. The growth outlook applies Department of Employment (now Jobs and Skills Australia) forecasts for all 19 industry divisions to the local industry mix, so it measures sector composition rather than local expansion and makes no allowance for population growth. Job demand comes from the same agency via its Internet Vacancy Index; industry and occupation structure from the 2021 Census. | ||
| Education | ABS, ACARA Annual (ACARA) | Aug 2026 last month headline measures · 2021 Census baseline |
| Transport | ABS, State Transport Departments Each timetable release | Jul 2026 2 months ago headline measures · 2021 Census baseline |
| Services & amenities | Provider directories, ACECQA Continuous | Jul 2026 2 months ago all 14 measures |
| Annual and financial-year sources 2 sections | ||
| Income | ABS, ATO Annual (ATO) | FY 2023 3 years ago headline measures · 2021 Census baseline |
| ATO taxable income statistics for FY 2023, indexed forward using the Wage Price Index. Census household income provides the distribution detail. | ||
| Health | ABS, ATO Annual | 2024 2 years ago headline measures · 2021 Census baseline |
| Census-measured — next update: 2026 Census 3 sections No more current small-area source exists for these, so they are labelled as Census-measured rather than implied to be current. | ||
| Housing | ABS 5-yearly (Census) | 2021 Census next update 2026 all 30 measures |
| Households | ABS 5-yearly (Census) | 2021 Census next update 2026 all 18 measures |
| Cultural diversity | ABS, Geoscience Australia 5-yearly (Census) | 2021 Census next update 2026 all 44 measures |
"Currency" is the most recent release feeding that section. Where the Census supplies the structural baseline underneath a current headline figure, the row says so.
How the numbers are built
Population
The Census provides the small-area baseline, aggregated from mesh blocks to this boundary. It is then re-based to the ABS Estimated Resident Population (June 2025 release), and new dwellings built since Census night are counted from address data — 34 validated new addresses here. The headline figure is therefore a current estimate for Aug 2026, not a 2021 count (19,942 at the 2021 Census → 20,556 now). Annual growth rates are compound (CAGR), not simple averages.
Age profile
Cohort shares are not raw Census counts. Every cohort is held as a pair — the Census baseline and a current estimate — and the split is re-based using ERP and state population projections, current to Aug 2026. Median age is the Census median plus modelled change since. Charts that show both are labelled "2021 Census vs Current Estimate".
Property sales
Sourced from the state valuation authority's sales register — current, not Census, and refreshed weekly. Medians are calculated from settled transactions in the period shown; periods with very low transaction counts are flagged or suppressed, because a handful of sales can move a median substantially.
Rents
Derived from state rental bond lodgement data, by dwelling type and bedroom count. Bonds are lodged at the start of a new tenancy, so this reflects new lettings, not the whole rented stock.
Development & infrastructure
Building approvals come from current ABS releases; development applications are collected from council and state planning portals; the infrastructure pipeline is compiled from Infrastructure Australia and local government sources. Applications are matched to this boundary by address or coordinates, so very recent lodgements may not yet appear.
Employment & income
Industry and occupation structure comes from the Census, but the headline labour-market indicators do not. Unemployment and labour force are derived from ABS Small Area Labour Markets (quarterly). The employment outlook applies Department of Employment forecasts for all 19 industry divisions to this area's own industry mix (the agency is now Jobs and Skills Australia), as does the Internet Vacancy Index used for job demand. Because it is weighted on industry composition alone, that outlook carries no allowance for local population growth — in fast-growing areas the real rise in local jobs will typically be higher. Income combines Census household income with ATO taxable-income statistics for FY 2023, indexed forward using the Wage Price Index.
Education, transport & amenities
School enrolments, ICSEA and performance come from ACARA's current release, not the Census. Public transport stops and service frequency are derived from GTFS timetable feeds published by state transport departments. Services and amenities are proximity and count scores built from provider directories, refreshed on their own cycle. The Census contributes only the travel-to-work and qualification measures.
Rankings and benchmarks. Where we rank this area, the comparison set is every area of the same boundary type — suburbs against suburbs, SA2s against SA2s. Benchmarks compare this area against its greater capital city region and the national figure for the same measure and period.
Limits worth knowing. Small areas carry larger error margins, and the ABS introduces small random adjustments to Census counts to protect confidentiality — so totals may not sum exactly. Estimates re-based from regional data describe the area's expected trajectory, not a direct count of it. Figures are indicative for research and are not financial, planning or valuation advice.
Cross-check us. The Census baseline for this boundary is at ABS 2021 Census QuickStats (SAL13647). QuickStats reports 2021 only — the figures on this page are more current wherever the ledger shows a later date.