Chart Color Schemes
This analysis uses Suburbs and Localities (SAL) boundaries, which can materially differ from Statistical Areas (SA2) even when sharing the same name.
SAL boundaries are defined by Australia Post and the Australian Bureau of Statistics to represent commonly-known suburb names used in postal addresses.
Statistical Areas (SA2) are designed for census data collection and may combine multiple suburbs or use different geographic boundaries. For comprehensive analysis, consider reviewing both boundary types if available.
est. as @ -- *
2021 Census | -- people


The median unit price in Sydney is $1.02m. House values have moved 0.0% a year compounded over five years.
Curious about local property values? Filter the chart to assess the volume and appreciation (including resales) trends and regional comparisons, or scroll to the map below view this information at an individual property level.
Find a Recent Sale

Sales Detail
Sydney has an estimated 20,435 residents, up from 16,667 at the 2021 Census — a change of 3,768 people, or 22.6%. Growth has averaged 2.1% a year over five years, faster than 91% of areas nationally. 596 new addresses have been validated here since Census night. Overseas migration accounts for 94.0% of that increase. That puts 6,951 residents on each square kilometre. Population is estimated from ABS Estimated Resident Population releases and GNAF address data, re-based from the 2021 Census and updated annually.
Detail
According to AreaSearch evaluations combining ABS demographic revisions across the wider vicinity with newly verified post-Census address records, the suburb of Sydney houses an estimated 20,435 residents as of Aug 2026. This equates to an expansion of 3,768 people (22.6%) compared to the 16,667 residents recorded at the 2021 Census. These findings stem from a calculated local population of 20,430 derived from the ABS ERP release in June 2025 alongside 596 validated new addresses identified since the enumeration. At 6,950 persons per square kilometer, population density sits within the top 10% across the nation in AreaSearch rankings, placing real estate at a high premium.
The suburb of Sydney outpaced both NSW (7.3%) and Greater Sydney with its 22.6% expansion rate since the 2021 census, establishing itself among the leading growth locations in the metropolitan footprint. Inbound international migration served as the principal driver of this expansion, accounting for roughly 94.0% of recent population additions. Demographic forecasting incorporates ABS and Geoscience Australia projections for local SA2 divisions published in 2024 using 2022 baseline figures, supplemented by 2022 NSW State Government SA2 forecasts (based on 2021 benchmarks) where necessary. Projections for 2032 to 2041 additionally integrate these aggregated age-bracket growth trajectories. Looking ahead, the suburb of Sydney is positioned for outstanding expansion that ranks in the top 10 percent of AreaSearch study areas, with SA2 modelling indicating an influx of 10,542 persons by 2041, representing a cumulative increase of 51.6% across the 16 years.
Frequently Asked Questions - Population
658 new dwellings have been approved in Sydney over the past five years, an average of 131 a year. That is 1.5 approvals per 1,000 residents. Of the 27 dwellings approved in the latest reporting year, 0% were detached houses and the rest townhouses or apartments. Few approvals have been recorded in the most recent months, well below the longer-run average; the latest ABS periods are still being reported. Figures come from ABS building approvals aggregated to this Suburb (SAL) boundary and are updated monthly as the ABS releases them.
Detail
ABS residential building approval data compiled by AreaSearch shows that the local area has recorded an annual average of approximately 131 residential approvals, accumulating to 658 homes across the last 5 financial years. Throughout FY-25 to date, no approvals have been registered. Between FY-21 and FY-25, an average of 14.8 people arrived locally per annum for each new residence constructed over those 5 financial years, creating an environment where demand substantially outstrips supply, which typically drives up property values and heightens buyer competition. Concurrently, $89.8 million worth of non-residential commercial approvals have been granted during the current financial year, underlining substantial local commercial capital investment.
Per-capita development volumes in the local market sit well below the regional benchmark, trailing Greater Sydney by 71.0%. This limited pipeline of new residential stock generally bolsters buyer interest and valuations across established real estate. Activity also tracks below national levels, reflecting a mature built environment alongside possible zoning and planning constraints. Furthermore, recent residential construction has been exclusively focused on medium and high-density formats. Emphasising higher-density dwellings delivers relatively accessible pricing tiers catering to downsizers, property investors, and first-home purchasers. According to the most recent AreaSearch quarterly projections, the local population is expected to expand by 10,537 residents by 2041. Should current construction tempos persist, residential completions could lag behind demographic expansion, potentially intensifying purchasing pressure and underpinning sustained capital appreciation.
Frequently Asked Questions - Development
Development applications around Sydney
Loading development applications…
| Lodged | Address | Description | Type | Distance | Status |
|---|
SOURCE: Planning portals and council registers, compiled by AreaSearch. Distance & bearing measured from the suburb midpoint.
AreaSearch tracks 30 current infrastructure and development projects inside Sydney, worth an estimated $88.1 billion. A further 131 sit in the immediately surrounding suburbs, taking the tracked pipeline within reach of the area to $146 billion. 41 are already under construction and 50 are due for completion within three years. The pipeline spans residential development, communities, precincts & urban renewal and transport & logistics. Records are compiled from Infrastructure Australia, state agencies, council planning portals and public announcements, reviewed and updated daily, then ranked by proximity, construction stage, completion horizon and project scale.
Detail
Local economic momentum is heavily shaped by major project delivery, strategic planning frameworks, and capital works programs. AreaSearch has pinpointed 122 key infrastructure developments positioned to influence the surrounding precinct. Prominent undertakings among these include Central Barangaroo, Mariyung Fleet (New Intercity Fleet), Harbourside Redevelopment by Mirvac, and Central Place Sydney, with primary initiatives detailed in the accompanying overview.
Professional plan users can use the search below to filter and access additional projects.
INFRASTRUCTURE SEARCH
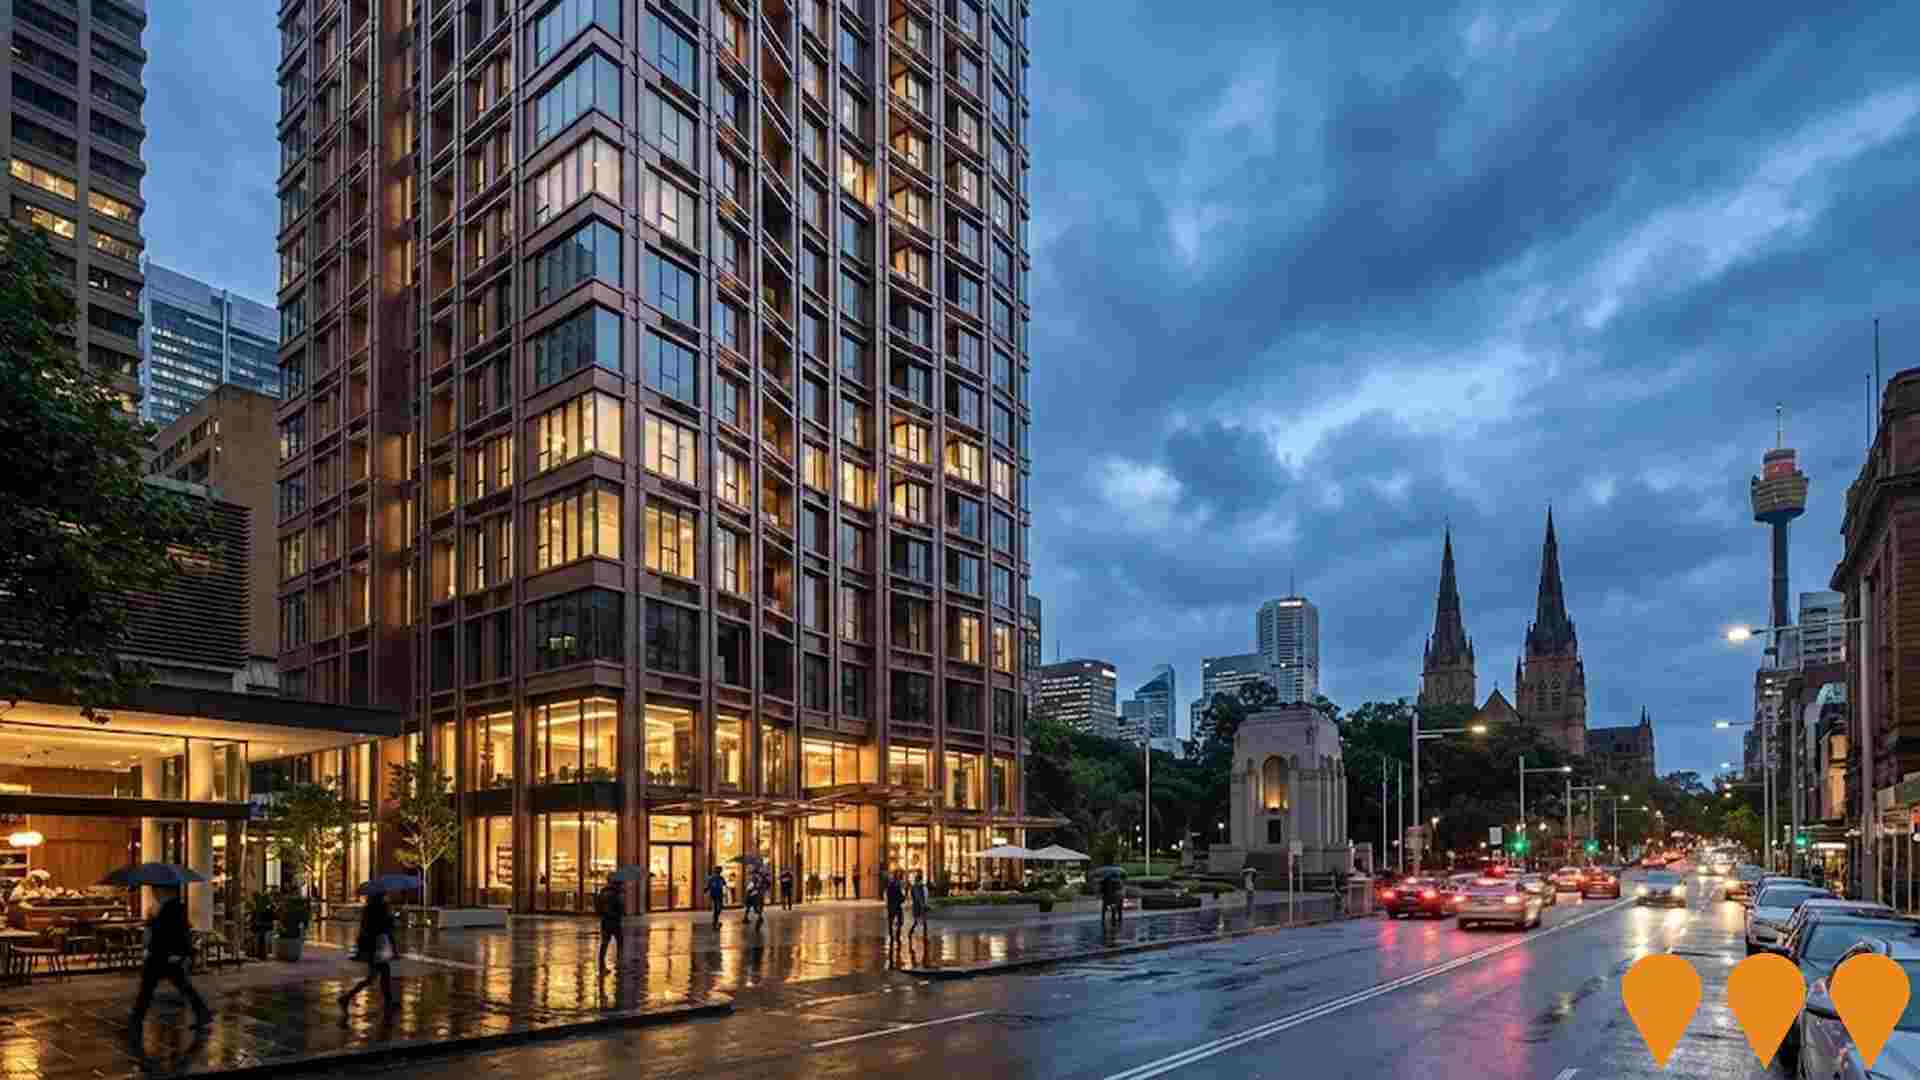
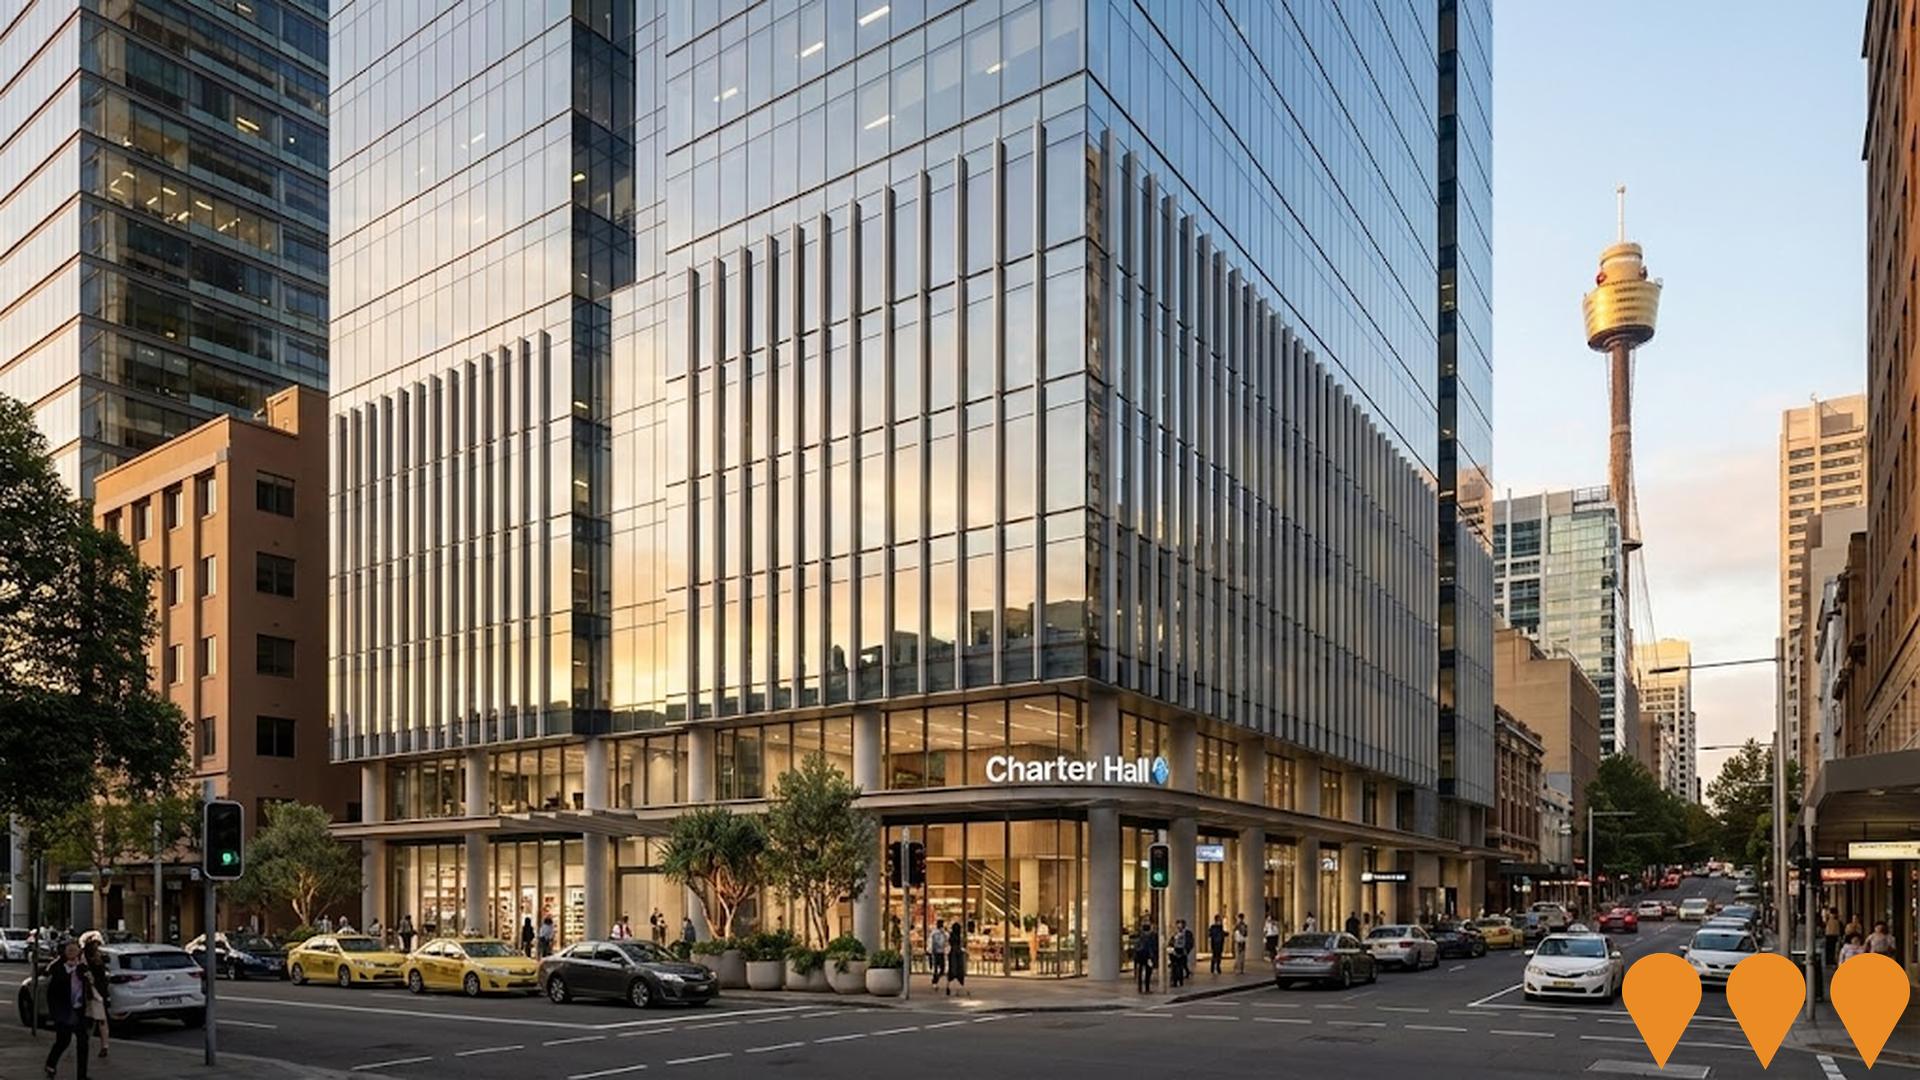
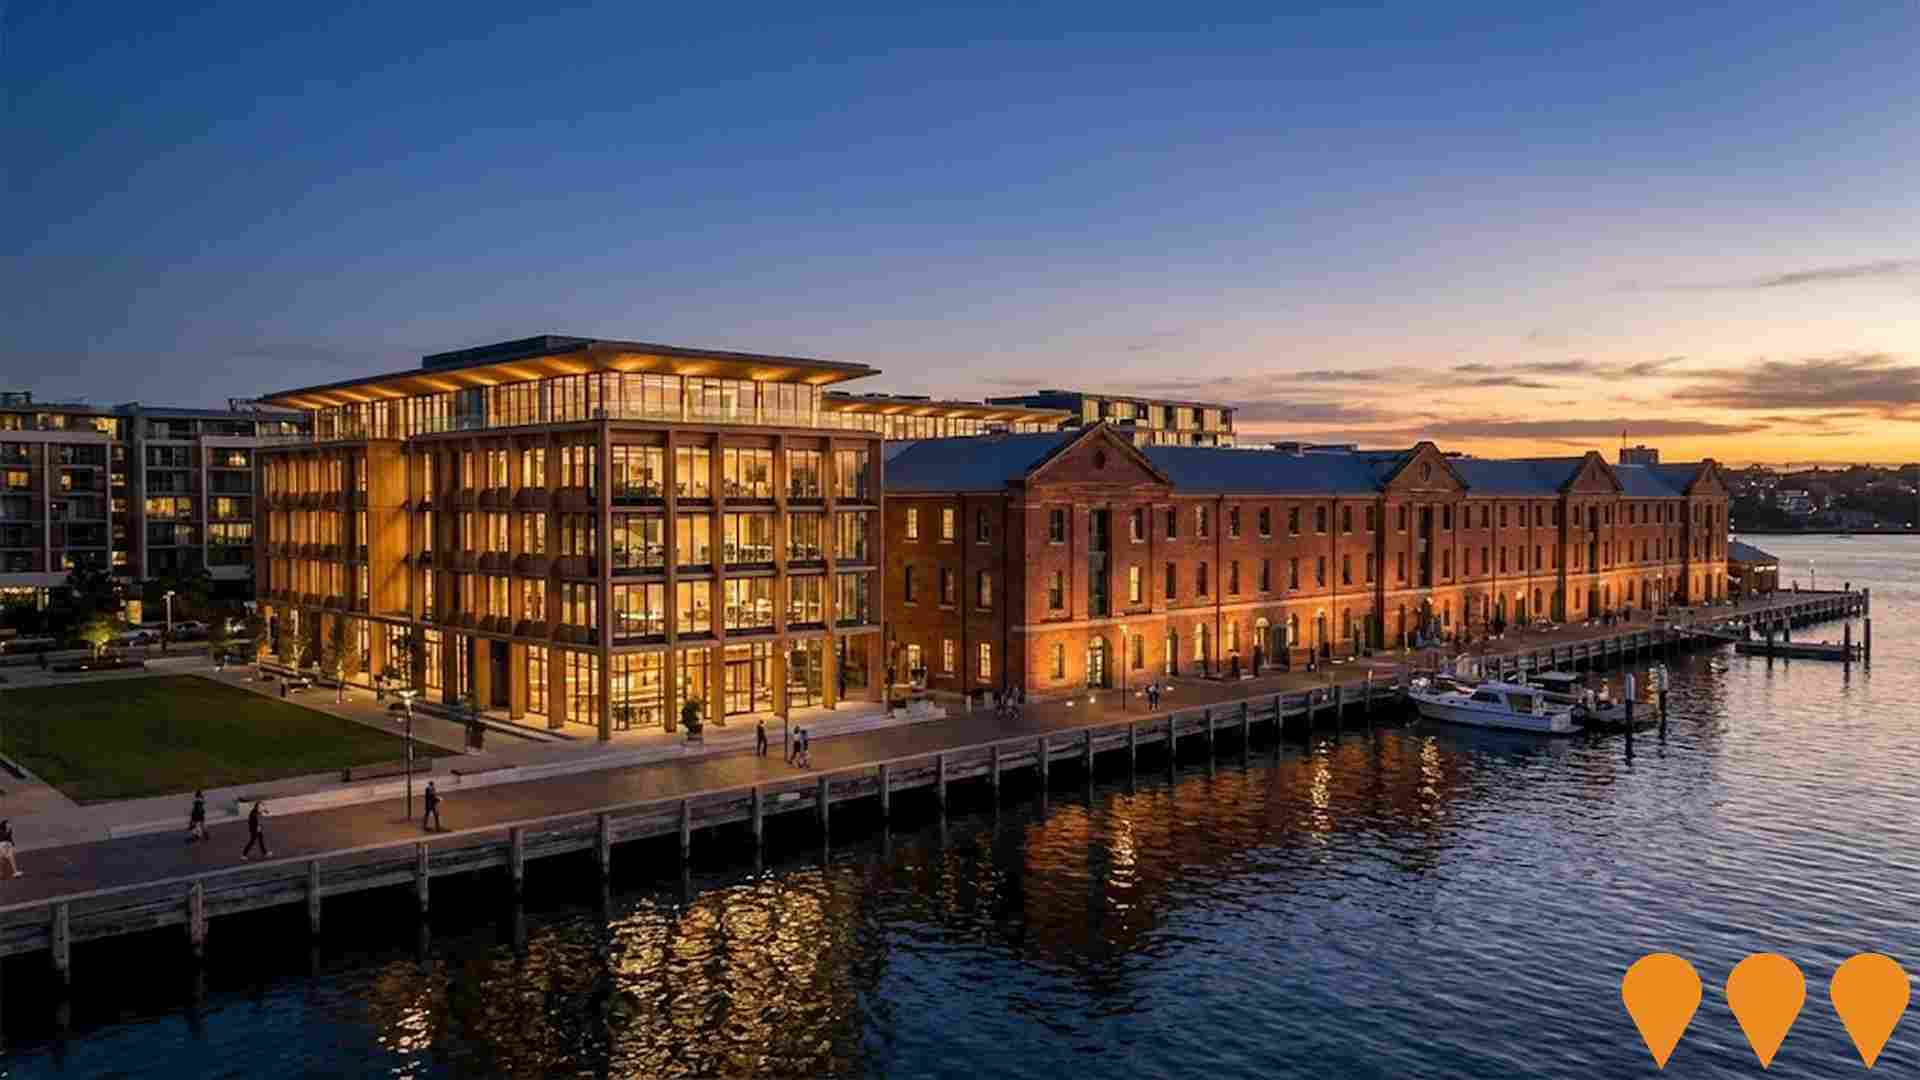
 Denotes AI-based impression for illustrative purposes only, not to be taken as definitive under any circumstances. Please follow links and conduct other investigations from the project's source for actual imagery. Developers and project owners wishing us to use original imagery please Contact Us and we will do so.
Frequently Asked Questions - Infrastructure
Cockle Bay Park (Cockle Bay Wharf Redevelopment)
A state-significant transformation of Cockle Bay Wharf into a vibrant mixed-use precinct. The project features a 183-metre commercial tower providing 75,000 sqm of premium office space, a 14,000 sqm retail and entertainment podium, and over 15,000 sqm of public open space, including a 5,500 sqm elevated park bridging the Western Distributor to reconnect the CBD with the waterfront.
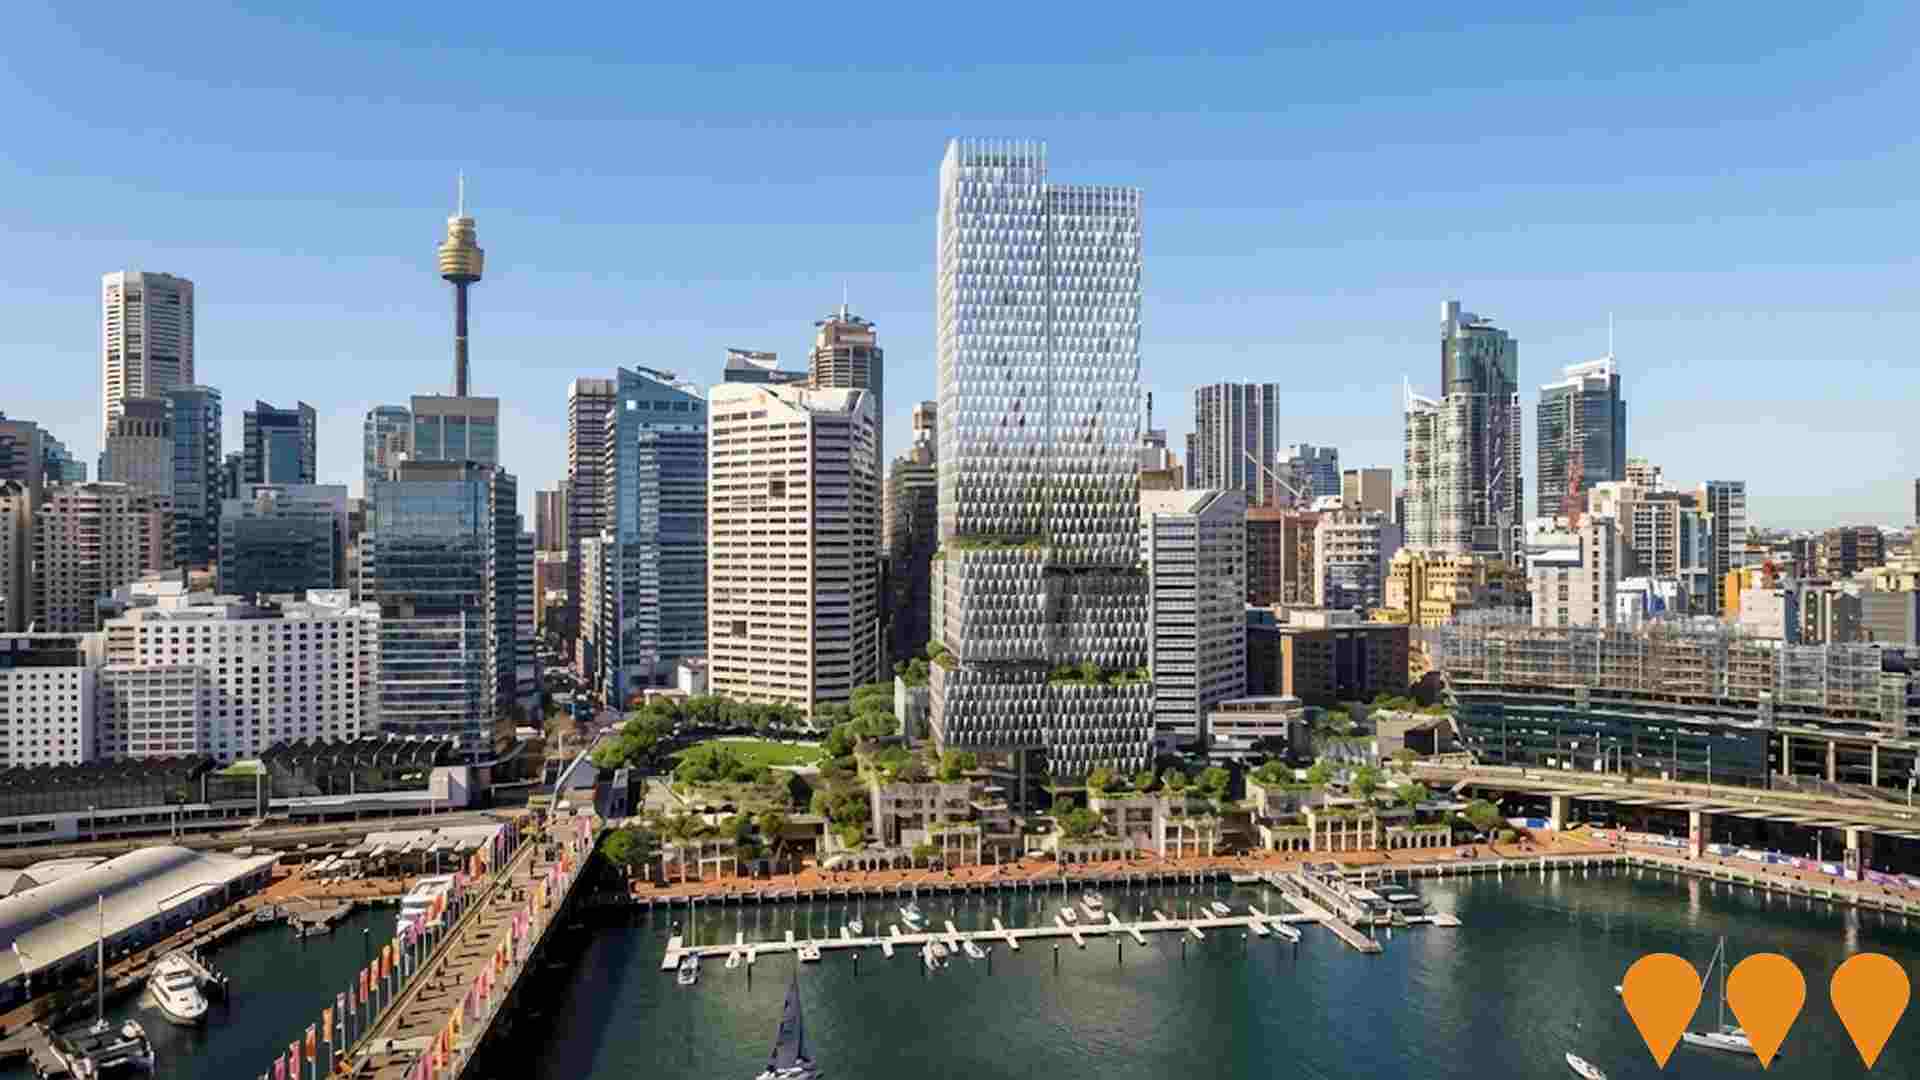
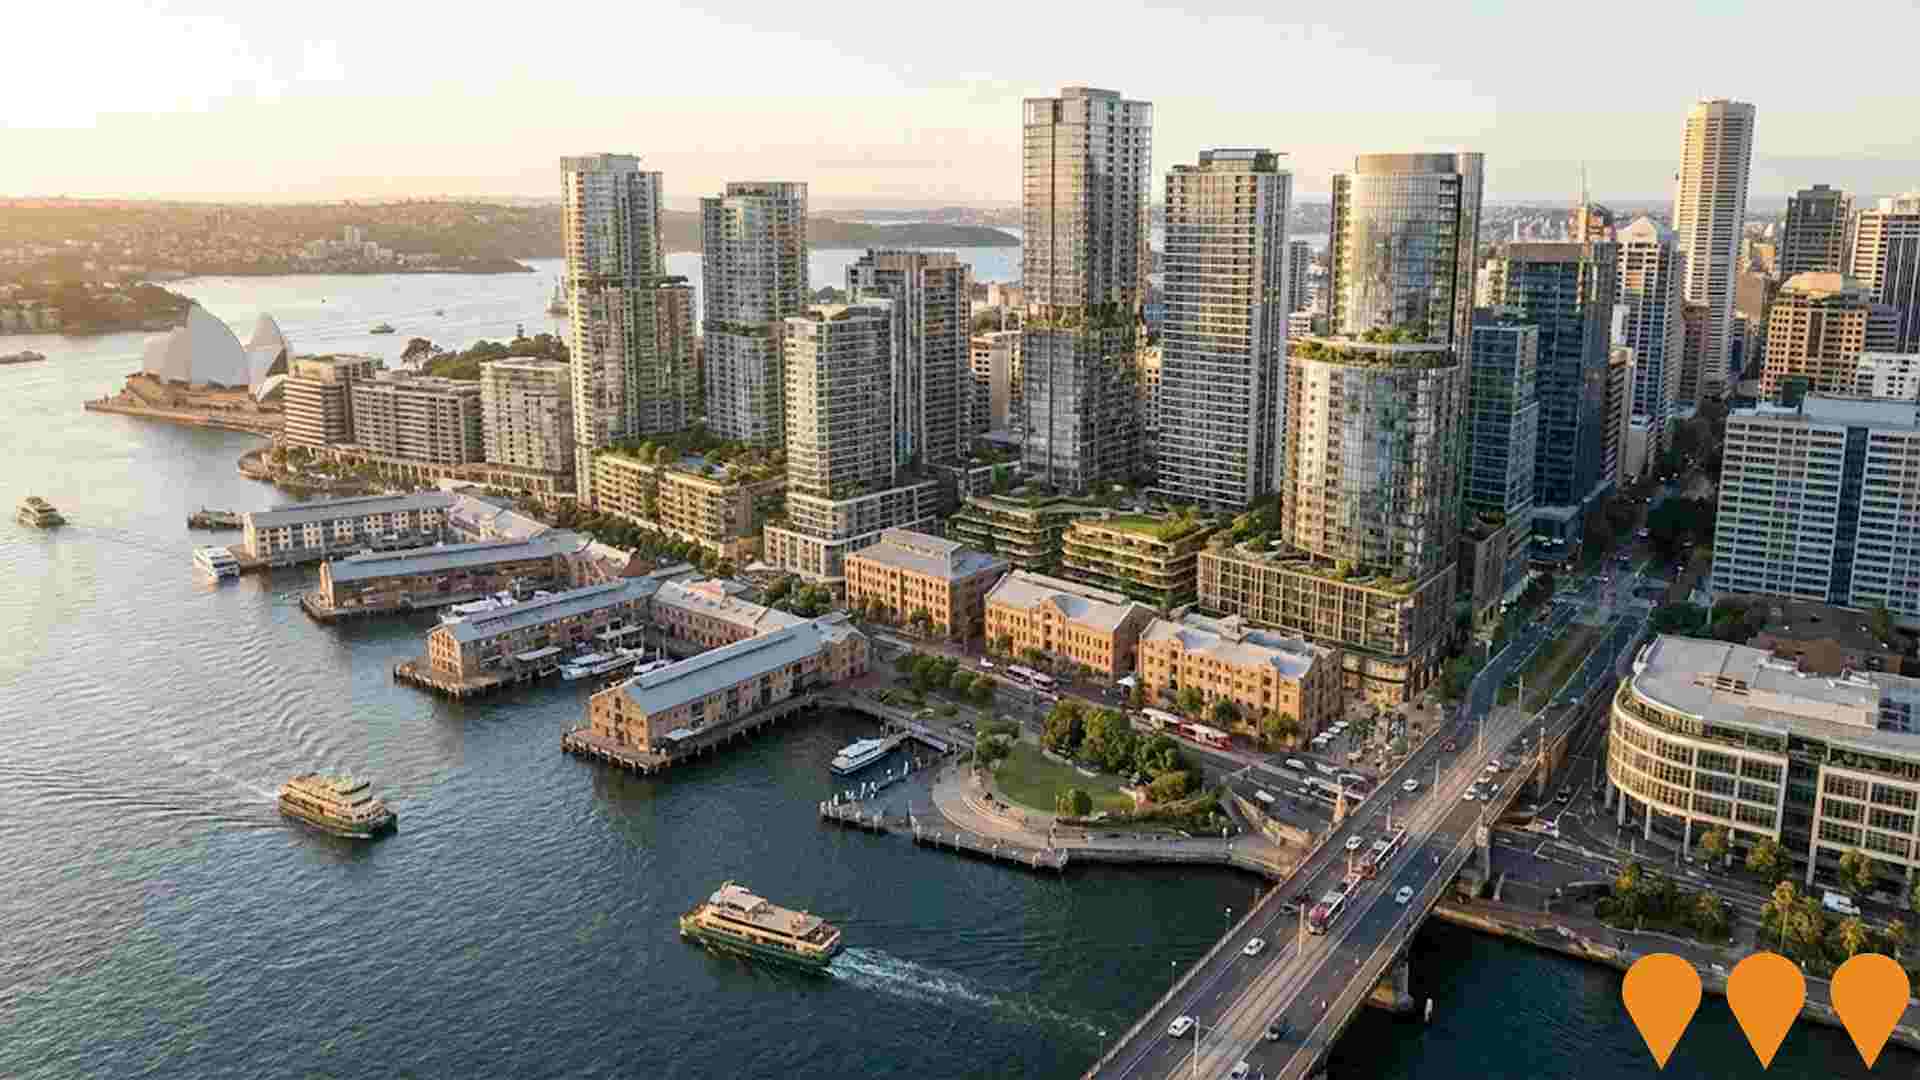
Harbourside Redevelopment by Mirvac
A $2 billion transformative mixed-use redevelopment of the former Harbourside Shopping Centre at Darling Harbour, delivered as a 50/50 joint venture between Mirvac and Mitsubishi Estate Co. The project delivers 87,000 sqm of gross floor area including 45,000 sqm of commercial and retail space and 42,000 sqm of residential in a 48-storey tower with approximately 260 luxury apartments and penthouses. The precinct features 10,000 sqm of public open space including a 3,500 sqm waterfront park, a widened promenade, a new laneway network, and 6,000 sqm of green roofs.A 4,000 sqm conference and events centre is also included. The tower core structure passed Level 20 as of late 2025 and the final major development application (SSDA No. 03 Public Domain) was approved by the Independent Planning Commission in June 2025. Staged completion is expected from 2026/2027. The precinct is designed by Snohetta and Hassell Studio.

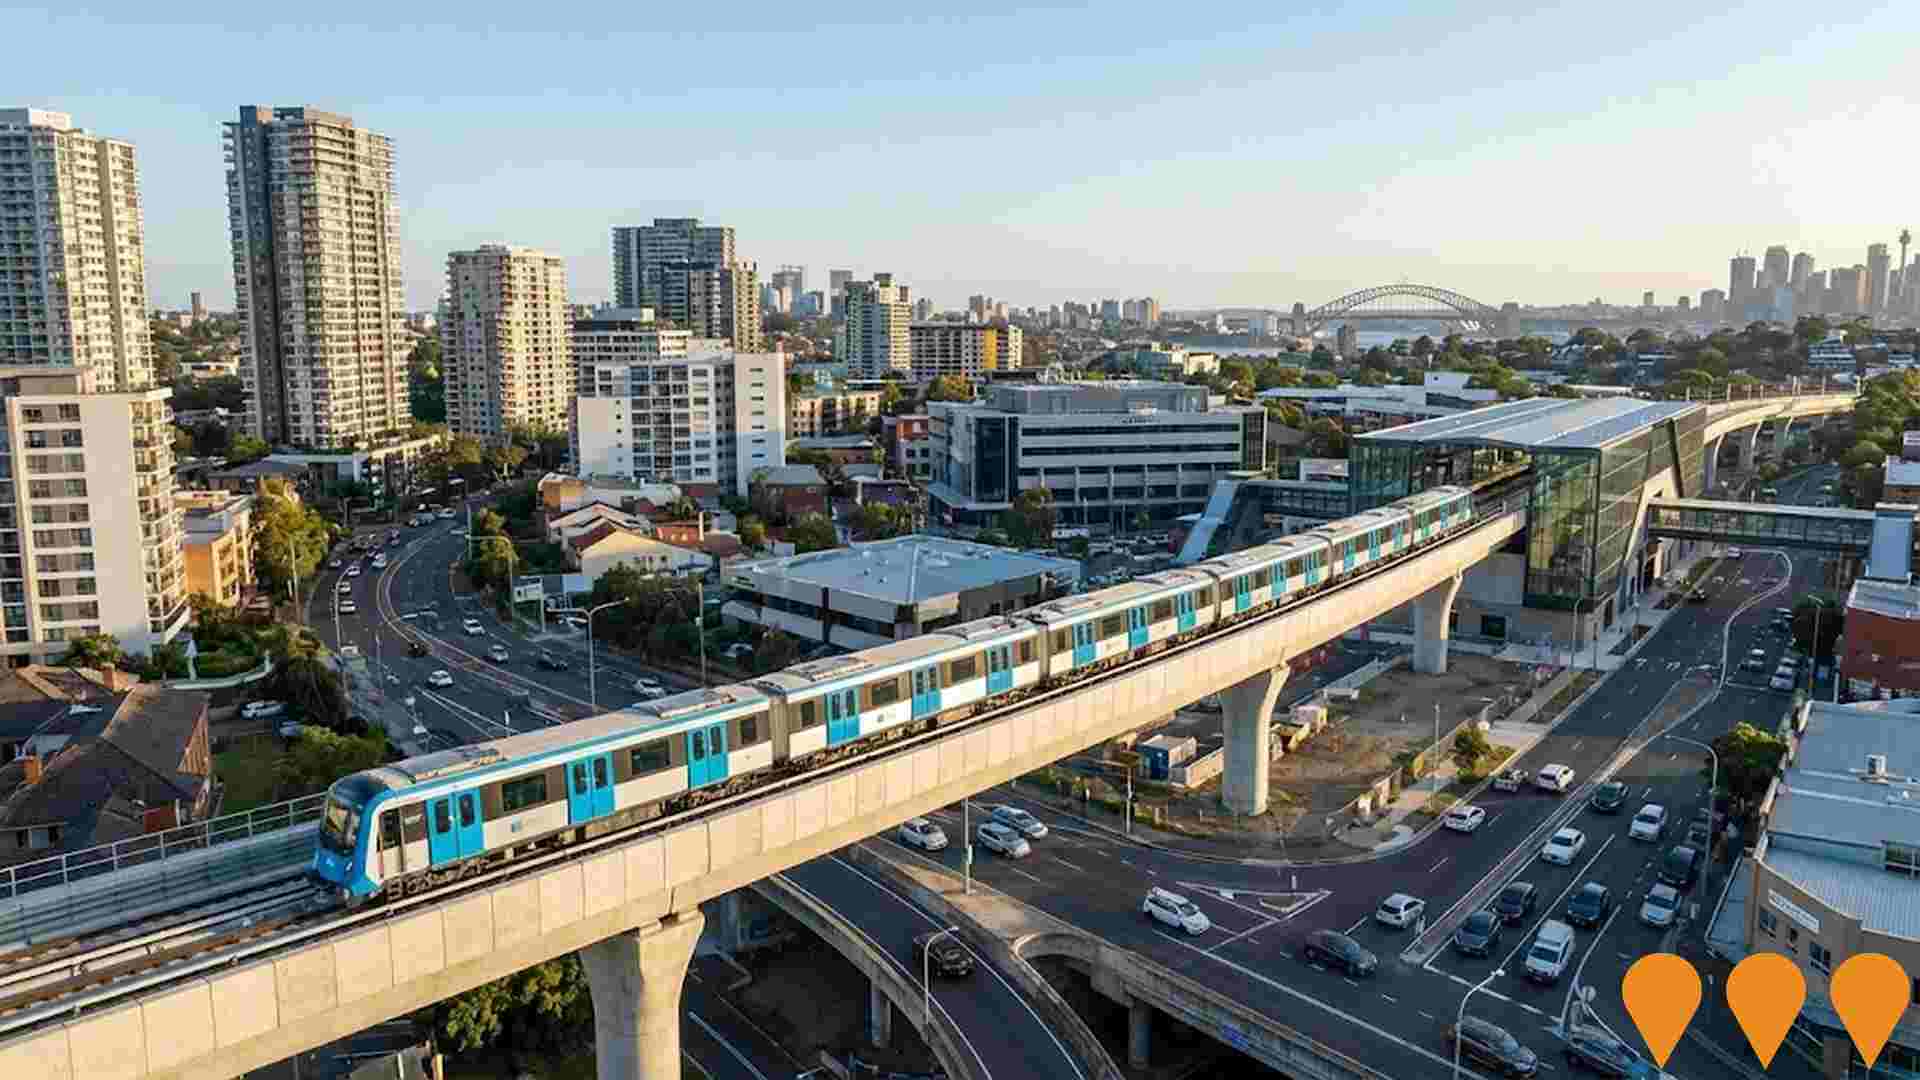
Sydney Metro Program
Australia's largest public transport program, comprising multiple metro lines across Greater Sydney. The M1 City and Southwest line is operating to Sydenham, while the Sydenham to Bankstown conversion is in final testing with weekend closures scheduled from May to July 2026 as the project moves toward trial running and a second-half 2026 opening. Sydney Metro West is a 24 kilometre underground line between Westmead and Hunter Street targeting a 2032 opening, with confirmed stations at Westmead, Parramatta, Sydney Olympic Park, North Strathfield, Burwood North, Five Dock, The Bays, Pyrmont and Hunter Street.Sydney Metro Western Sydney Airport is under construction between St Marys, the new Western Sydney International Airport and Bradfield, with the objective of opening when the airport starts passenger services.
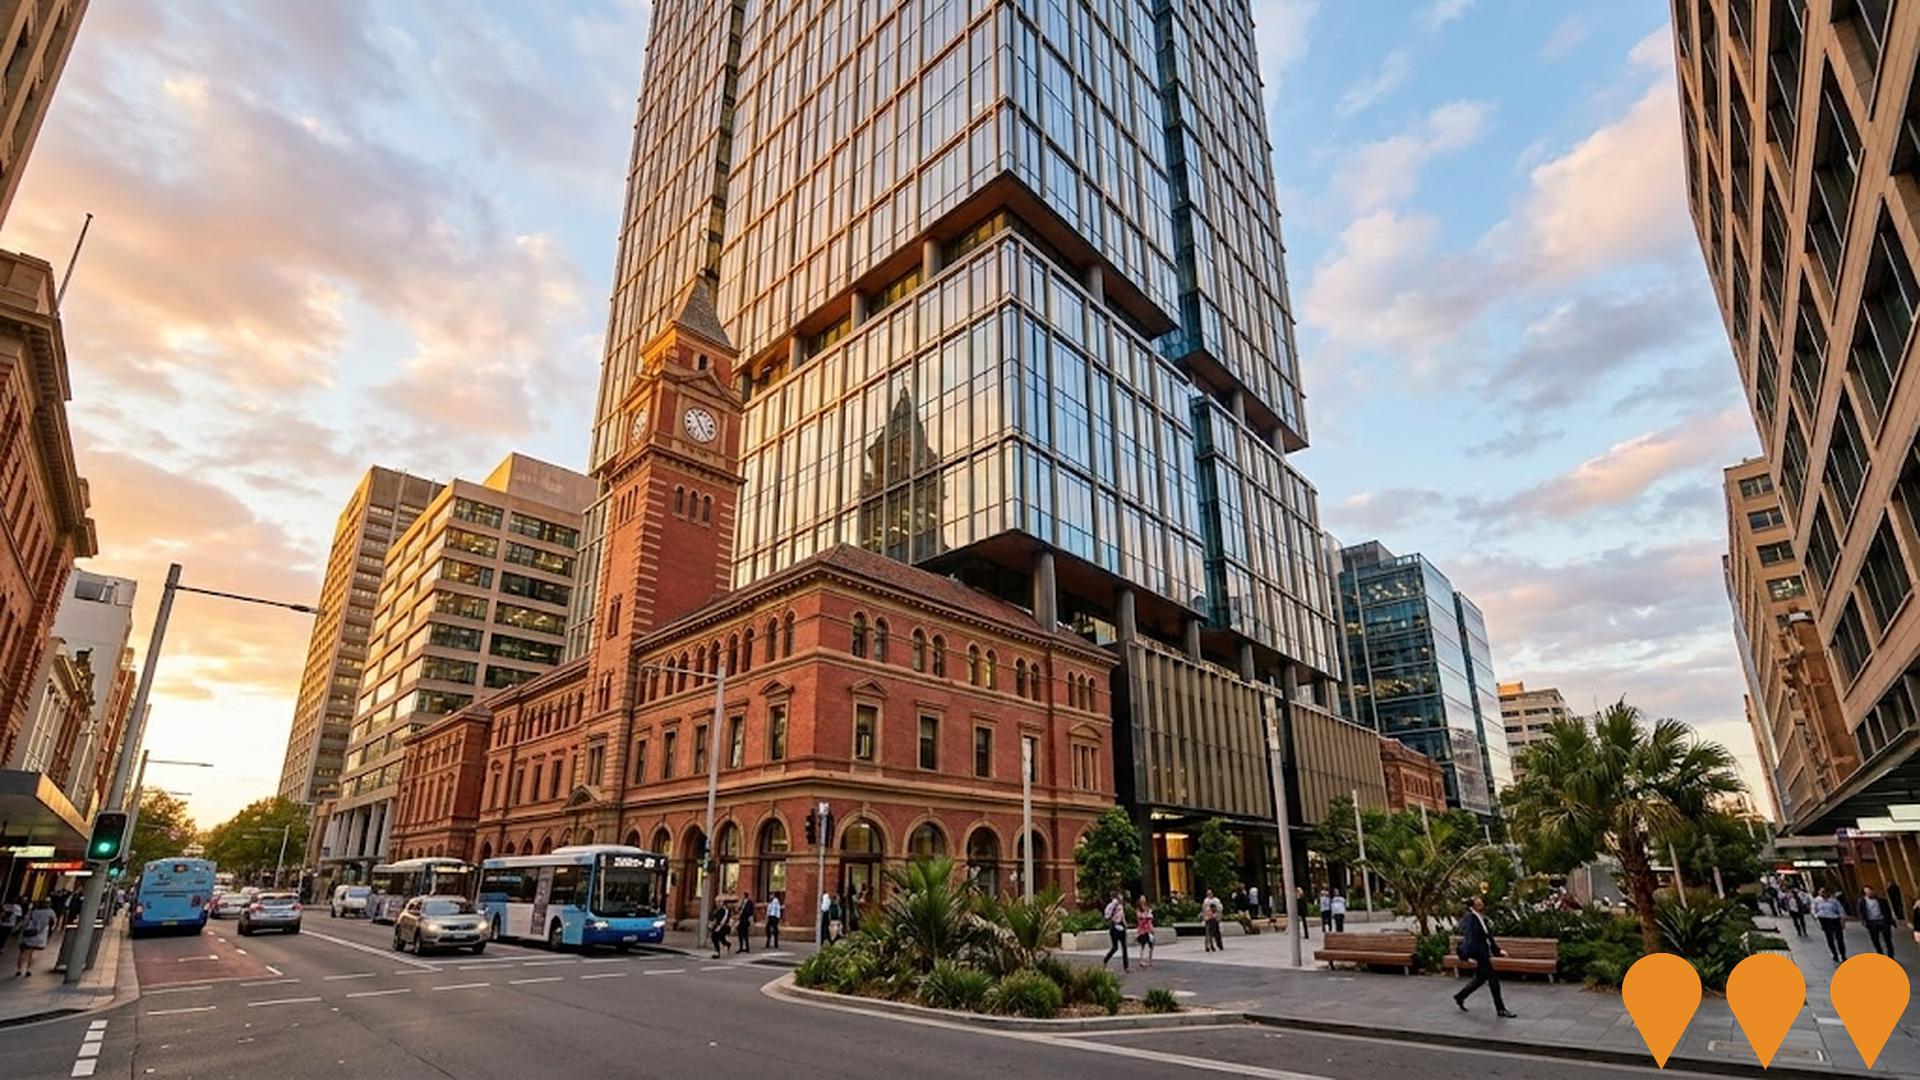
The Post House
A 45-storey mixed-use tower in the Tech Central precinct, also known as TOGA Central. The development integrates the heritage-listed former Parcels Post Office and delivers 29,228sqm of premium office space, a 204-key boutique hotel, and ground-floor/podium retail. Key features include a rooftop pool, day spa, gym, and the new public Henry Deane Plaza. The project targets a 6-star Green Star and 5.5-star NABERS Energy rating.
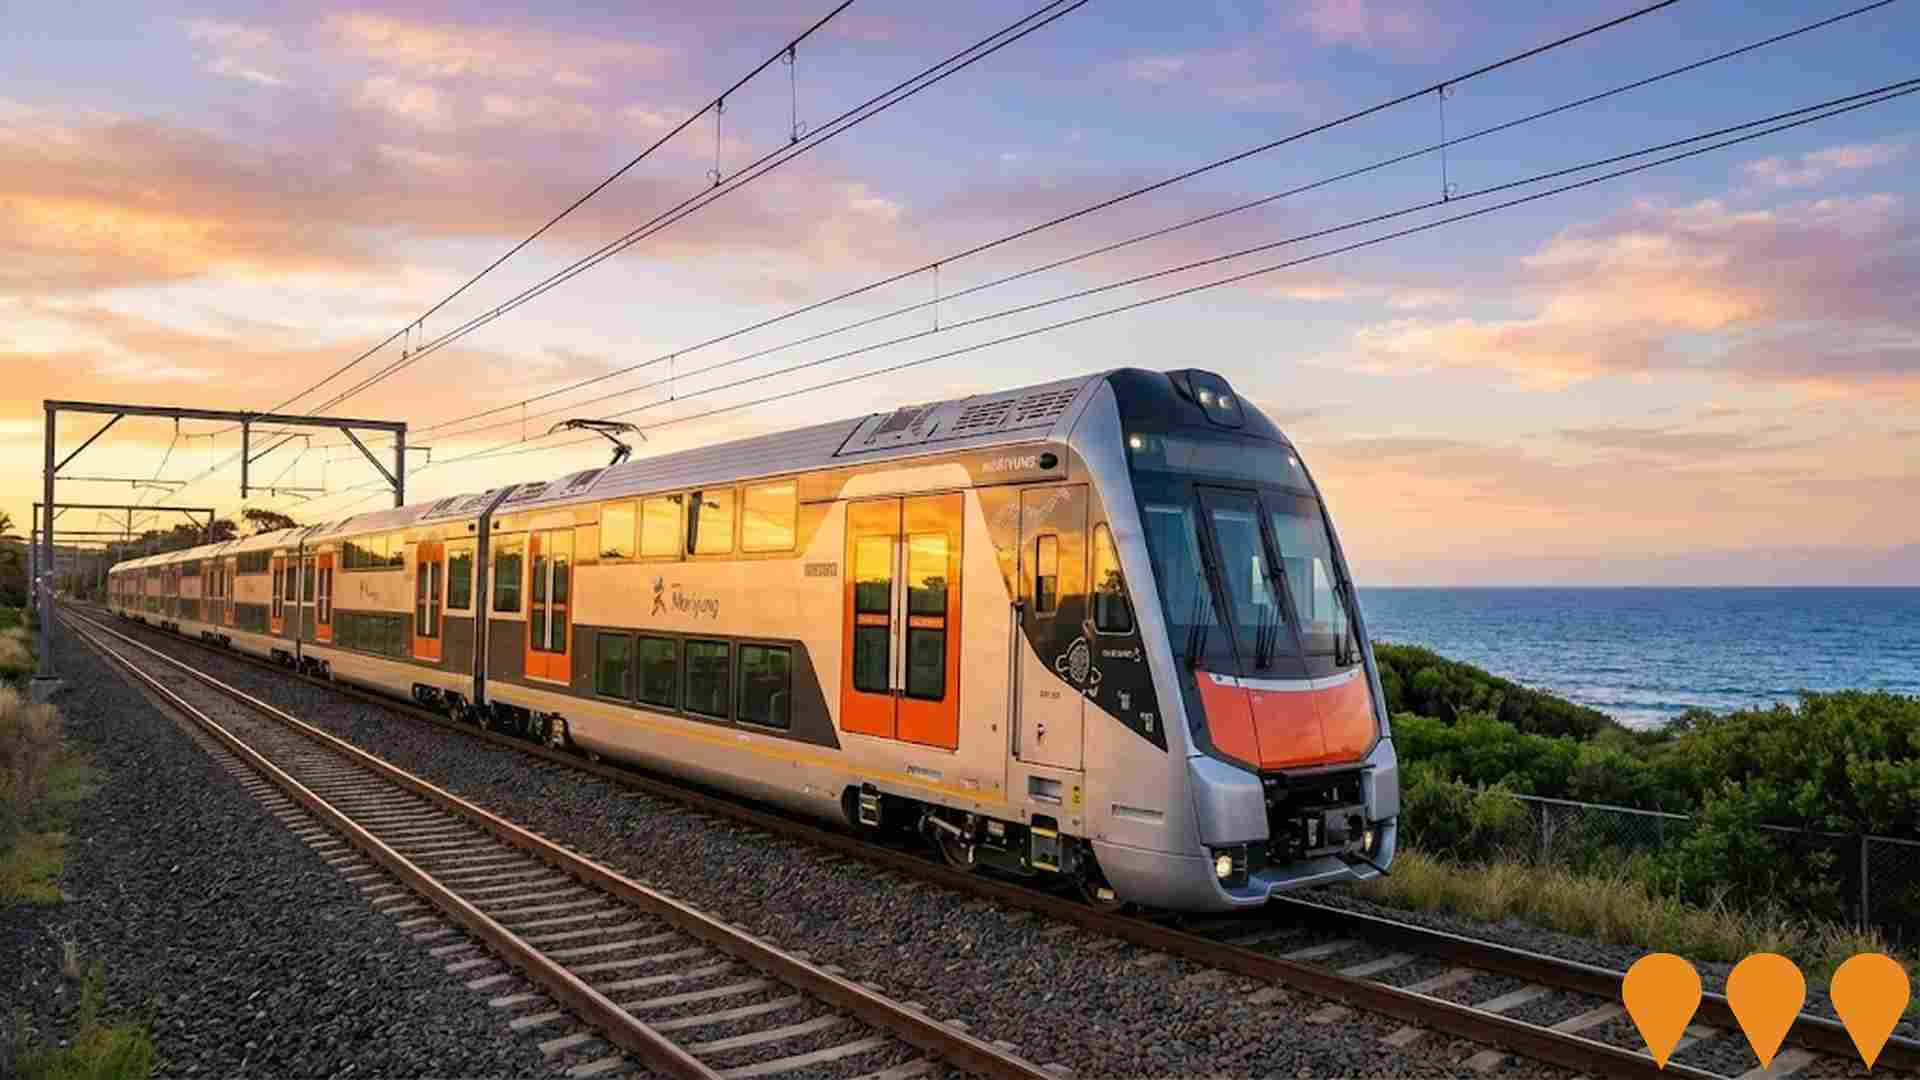
Mariyung Fleet (New Intercity Fleet)
The Mariyung Fleet is a 610-carriage double-deck electric train fleet (D sets) replacing the ageing V-set and Oscar fleets across the NSW intercity network. Delivered by the RailConnect NSW consortium (UGL, Hyundai Rotem, Mitsubishi Electric Australia), the trains feature wider 2x2 seating with arm rests, tray tables and cup holders, charging ports, dedicated luggage, pram and bicycle spaces, accessible toilets, dedicated wheelchair spaces, CCTV, digital information screens and Automatic Selective Door Operation. The fleet operates in 4, 6, 8 or 10-car formations.Passenger services commenced on the Central Coast & Newcastle Line on 3 December 2024, on the Blue Mountains Line on 13 October 2025, and on the South Coast Line on 14 April 2026. The South Coast Line rollout begins with seven 4 and 6-car sets, scaling to 16 trains by 2027 with 8-car sets later in 2026 and 10-car configurations in 2027. The project includes the Kangy Angy Maintenance Facility (operated by UGL on a 15-year contract) and extensive corridor upgrades including platform extensions, signalling modifications, balise installation and overhead wiring works.
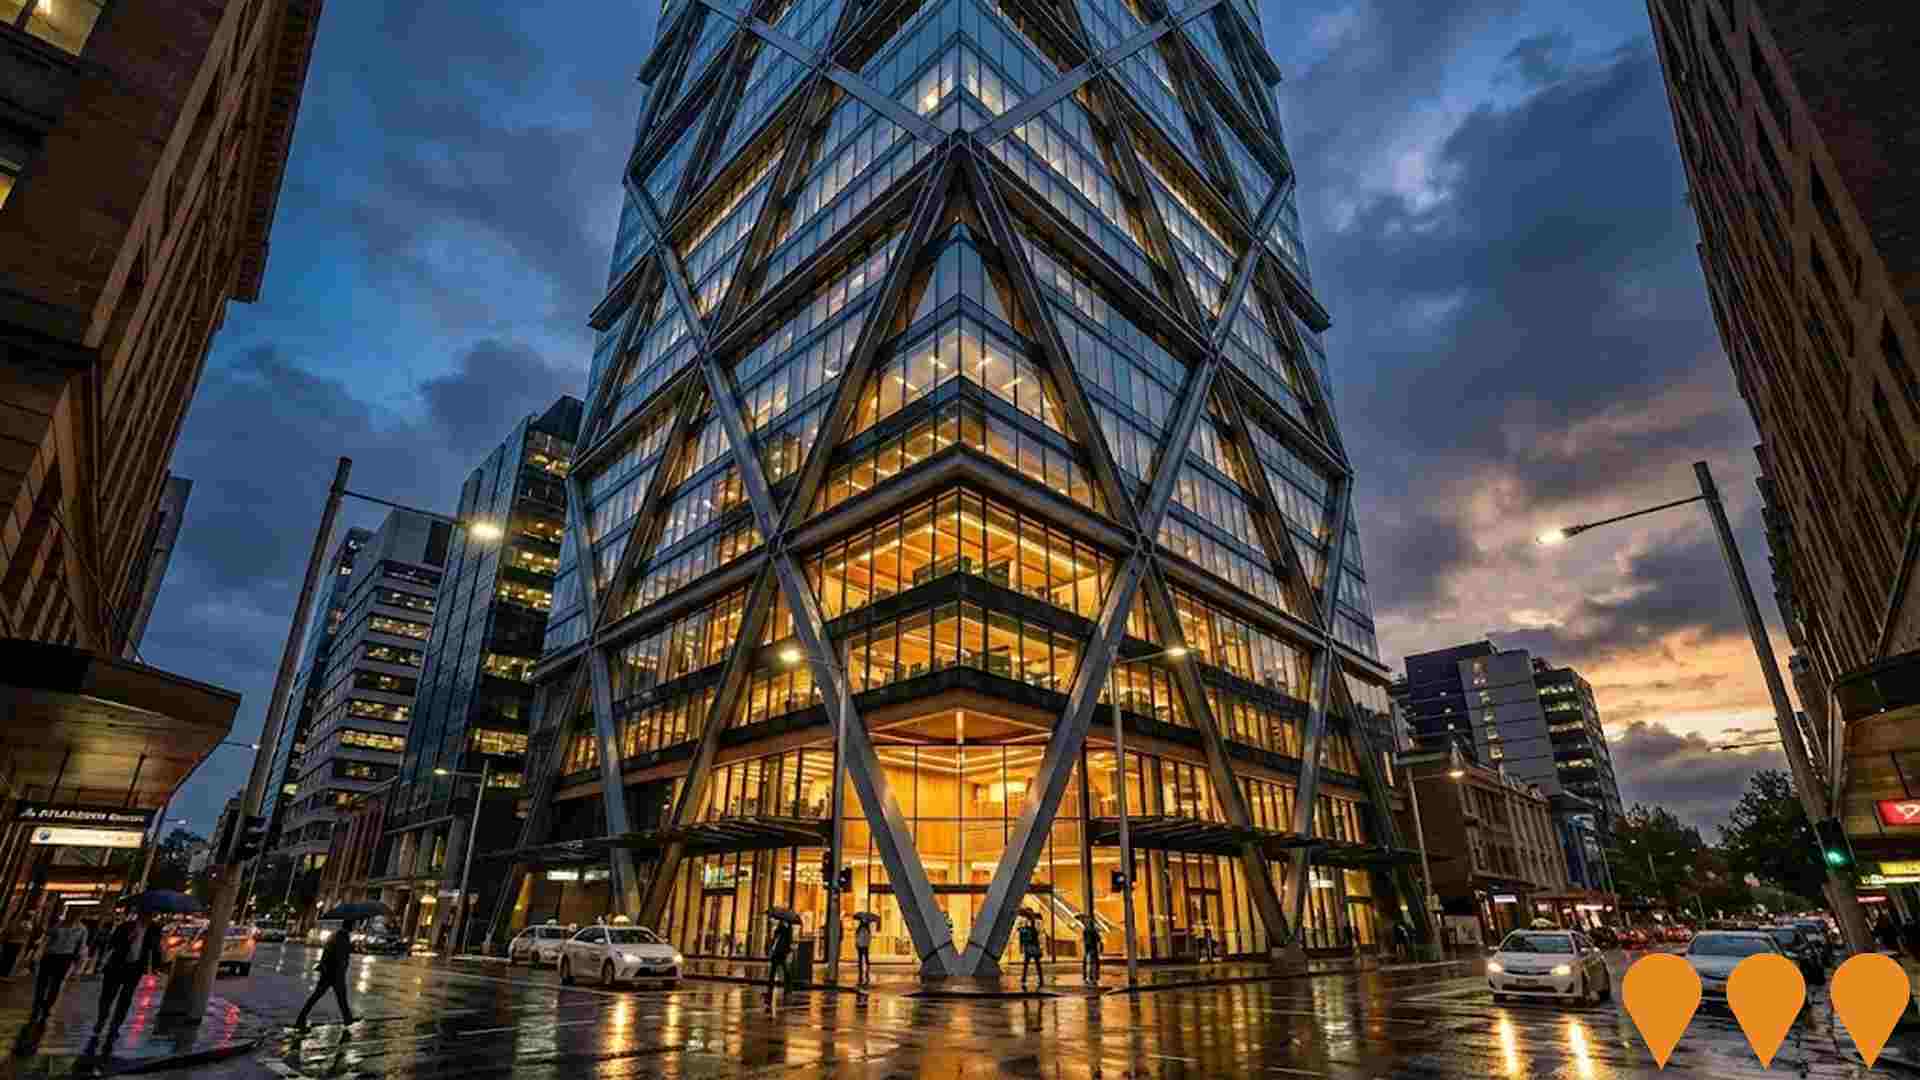
Atlassian Central
Atlassian Central is a 39-storey, 183-metre tower under construction at 8-10 Lee Street, Haymarket, anchoring the NSW Government's Tech Central innovation precinct adjacent to Central Station. Designed by SHoP Architects and BVN, the building combines a steel exoskeleton with a hybrid mass timber and concrete structure, featuring seven four-storey internal timber 'habitats' built using more than 30,000 cubic metres of cross-laminated timber and glulam. Once complete, it will be the world's tallest commercial hybrid timber building.The tower offers 75,000 square metres of gross floor area (around 59,100 square metres net lettable) and is co-owned by Dexus and Atlassian. The lower five levels integrate a 137-room YHA hostel and the heritage-listed Parcel Shed, which is being adaptively re-used as the building lobby. Sustainability targets include a 50 percent reduction in embodied carbon, 100 percent renewable energy operation, a 5.5-star NABERS Energy commitment and a 6-star Green Star target, supported by an electricity-generating photovoltaic facade. Built and Obayashi Corporation joint venture (BOJV) commenced construction in August 2022. As of mid-2026 the tower has surpassed Milwaukee's Ascent to become the world's tallest hybrid timber tower, with Level 39 top-out scheduled for June 2026 and practical completion targeted for November 2026. Atlassian is expected to occupy five of the seven habitats from late 2028 following fit-out.
Griffin Theatre
Major redevelopment of SBW Stables Theatre to increase capacity by 44% and improve accessibility. Designed by Tonkin Zulaikha Greer Architects, funded by Neilson Foundation and NSW Government.
Sydney Metro West - Hunter Street Station and Precinct
New underground metro station and integrated precinct in the Sydney CBD for the Sydney Metro West line, with entrances on George, Bligh and O'Connell Streets. All tunnelling on Sydney Metro West completed in March 2026 with the final TBM breaking through into the Hunter Street cavern. The Metropolis Consortium (Lendlease, Mirvac and Coombes Property Group) was awarded the $1.5 billion integrated station development contract in January 2026, covering station fitout and two over-station commercial towers (51-storey West tower and 58-storey East tower).Main station construction is expected to begin in late 2026 once cavern work is finalised. The towers will deliver up to 150,000 square metres of commercial office and retail space. The station will provide connections to Wynyard and Martin Place stations and is targeted to open with the Metro West line in 2032.



12,679 residents of Sydney are employed, from a labour force of 12,909. Unemployment sits at 1.8%, with participation at 65.9%. Weighted for its industry mix, the area's sectors are forecast to grow about 6.9% nationally over five years. That reflects industry composition only and makes no allowance for local population growth, so in an area growing as fast as this one it understates the likely rise in local jobs. The working-day population is estimated at 144,109, about 7.1 times the resident population, so the area draws in more workers than it sends out. Unemployment and labour force come from ABS Small Area Labour Markets, updated quarterly; the industry and occupation profile is from the 2021 Census.
Detail
A highly qualified talent pool characterizes the local labor force, underpinned by a prominent professional services footprint, an unemployment rate standing at a modest 1.8%, and annual employment expansion estimated at 1.4% according to AreaSearch statistical area aggregations. As of March 2026, employed residents total 12,679, while local unemployment sits 2.3% below the 4.1% recorded across Greater Sydney, even though the participation rate of 65.9% trails the broader regional level of 68.9%. Census figures also showed that 45.2% of workers operated from home, though this metric should be viewed alongside the prevailing Covid-19 restrictions of that period.
Resident employment centers heavily on accommodation & food, professional & technical, and finance & insurance. Representation in accommodation & food is exceptionally prominent, reaching 3.5 times the broader metropolitan baseline. In contrast, health care & social assistance maintains a comparatively minor footprint, engaging 6.5% of workers locally against 14.1% across the region. Operating with 12.7 workers per local resident as at the Census, the precinct functions as a major destination for employment, providing a jobs surplus that draws in commuters from surrounding districts. AreaSearch compilation of ABS and SALM figures indicates that over the 12-month period, local employment expanded by 1.4% while the workforce base rose by 1.0%, bringing about a 0.4 percentage points decline in unemployment. Across Greater Sydney over the same timeframe, jobs increased by 1.9%, the labor pool grew by 1.9%, and unemployment showed a minor decrease. Future workforce trends can be gauged using national industry projections published in Mar-26 by Jobs and Skills Australia. Projecting these five-year and ten-year national trajectories (anticipating 6.6% and 13.7% nation-wide expansion respectively) against the local industry baseline suggests local employment could rise by 6.9% over five years and 13.7% over ten years, though these figures represent simple industry-weighted extrapolations rather than detailed localized population forecasts.
Frequently Asked Questions - Employment
Median household income in Sydney is $2,227 a week (about $116,000 a year), with median personal income at $971 a week. ATO records put median taxable income at $44,608 a year against an average of $111,767. The average runs 151% above the median, a wider spread than most areas and a sign of a concentrated group of high earners. Household income is from the 2021 Census; taxable income is from ATO Taxation Statistics for the latest financial year available, indexed forward using the ABS Wage Price Index.
Detail
Postcode-level ATO statistics released by AreaSearch for financial year 2023 place earnings in the suburb of Sydney well above national standards, showing a median taxpayer income of $44,608 alongside an average of $111,767. By comparison, Greater Sydney recorded a median of $60,817 and an average of $83,003. Factoring in subsequent Wage Price Index expansion of 10.32% since financial year 2023, revised benchmarks reach approximately $49,212 for median earnings and $123,301 for average income as of March 2026. Across personal, family, and household levels, 2021 Census returns consistently place local incomes between the 75th and 79th percentiles nationwide.
The single largest earnings bracket comprises 35.2% of residents (7,193 people) within the $1,500 - 2,999 per week range, mirroring the 30.9% share seen regionally. A significant 34.9% earning upwards of $3,000/week underlines high household purchasing capacity. While residential costs absorb 23.3% of earnings, strong remuneration preserves disposable incomes at the 67th percentile, contributing to a SEIFA income placement in the 9th decile.
Frequently Asked Questions - Income
Sydney had 7,107 occupied dwellings at the 2021 Census, 0% detached houses and 100% apartments. 12% are owned with a mortgage, 75% rented and 14% owned outright. At that Census the median rent was $600 a week and the median mortgage repayment $2,691 a month, a total housing cost higher than 99% of areas nationally. Rent absorbs 26.9% of household income here and mortgage repayments 27.9%. Dwelling stock, tenure and housing costs are 2021 Census measures — the only source that counts dwellings at this boundary size.
Detail
According to latest Census data, detached houses account for 0.1% of local dwellings while 99.9% consist of other dwellings such as apartments and semi-detached properties, contrasting with the Sydney metro distribution of 55.9% houses and 44.1% other dwellings. Outright ownership stands at 13.9%, trailing wider Sydney metro levels, with remaining properties held under a mortgage (11.5%) or occupied by tenants (74.6%). Local financing commitments and rental charges are elevated: median monthly mortgage repayments reached $2,691 and median weekly rents stood at $600, exceeding Sydney metro medians of $2,427 and $470.
Compared against Australian benchmarks of $1,863 for mortgages and $375 for weekly rents, local housing expenditures remain notably higher.
Frequently Asked Questions - Housing
Sydney counted 7,107 households at the 2021 Census, an estimated 8,714 today, averaging 2.1 people each. 9% are couples with children, fewer than in 98% of areas nationally, against 33% couples without children. 37% of households are people living alone, and families average 0.4 children. Household and family composition is measured only by the Census, so these are 2021 figures.
Detail
Family units account for 48.5% of local households, comprising couples without children (33.4%), couples with children (8.7%), and single parent families (4.0%). Non-family living arrangements make up 51.5% of the total, consisting of lone person households (37.4%) and group households (14.0%). The area records a median household size of 2.1 people, which is more compact than the Greater Sydney benchmark of 2.7.
Frequently Asked Questions - Households
56.5% of adults in Sydney hold a university qualification, including 37.9% with a bachelor degree and 16.4% with postgraduate qualifications, higher than 79% of areas nationally. A further 7.2% hold a vocational qualification. 7 schools serve the area, with 2,516 enrolment places and an average ICSEA of 1,067 against a national benchmark of 1,000. Qualifications come from the 2021 Census; school enrolments, ICSEA and results come from ACARA's current release.
Detail
Qualifications among residents aged 15+ track well above regional and national benchmarks, with 56.5% possessing university credentials compared to 32.2% across NSW and 30.4% throughout Australia, creating an advantageous foundation for the knowledge economy. Bachelor degrees represent the largest tier at 37.9%, accompanied by postgraduate qualifications at 16.4% and graduate diplomas at 2.2%. Vocational training accounts for 24.8% of formal qualifications among the 15+ demographic, comprising advanced diplomas (17.6%) and certificates (7.2%). Community participation in study programs is substantial, with 37.1% of the resident population actively undertaking formal education. This proportion incorporates 9.5% enrolled in tertiary institutions, 2.2% attending primary education, and 1.7% in secondary schooling.
Frequently Asked Questions - Education
Schools Detail
Public transport in Sydney reaches 174 stops on 138 routes, timetabled for about 74,400 services a week. The typical home sits about 130 m from its nearest stop. Trains carry the largest share of public transport commuters. Households keep an average of 0.1 vehicles. Stop and service counts are built from operators' published GTFS timetables and refresh with each timetable release; vehicle ownership is from the 2021 Census.
Detail
Commuter connectivity is supported by 174 operational public transport stops spanning bus, ferry, train, and lightrail networks across the precinct. These boarding points are integrated across 138 transit routes that deliver 74,419 weekly passenger trips. Transport accessibility is outstanding, with the typical resident positioned 131 meters from their closest boarding point. Reflecting its residential character, outward commuting is standard: on-foot travel represents 32% of journeys, alongside 27% by train and 16% by bus. Private vehicle ownership is modest at 0.1 per dwelling, below regional norms, while 45.2% of residents were recorded working from home (2021 Census; influenced by COVID-19 settings).
Transit schedules deliver a combined frequency of 10,631 trips per day across the network, providing an average of roughly 427 weekly trips for each stop. The corresponding map highlights the 100 closest transit locations relative to the geographic centerpoint.
Frequently Asked Questions - Transport
Transport Stops Detail
87.9% of residents in Sydney report no long-term health condition, a healthier profile than 93% of areas nationally. 1.6% need daily assistance with core activities, and 71.0% hold private health cover. The standardised death rate runs at 4.1 per 1,000 residents. Health conditions, assistance needs and insurance are 2021 Census measures; the death rate comes from current ABS releases.
Detail
AreaSearch evaluations of mortality and chronic condition metrics reflect outstanding health outcomes across the local community, marked by an unusually low incidence of typical chronic ailments throughout all demographics. Furthermore, private health insurance coverage is exceptionally strong, taken up by approximately 71% of residents (14,498 people). This compares favorably against coverage rates of 59.9% across Greater Sydney and 55.7% nationally. Asthma and mental health issues represent the most prevalent diagnosed conditions, affecting 3.6% and 3.7% of the community respectively, while 87.9% of residents reported having no long-term health ailments, exceeding the Greater Sydney proportion of 74.6%.
Seniors aged 65 and over constitute 6.7% of the local population (1,369 people), sitting below the 15.5% share observed across Greater Sydney. Health indicators among this senior cohort remain particularly robust, aligning closely with wider national health rankings.
Frequently Asked Questions - Health
76.1% of Sydney residents were born overseas and 65.7% speak a language other than English at home, more culturally diverse than 98% of areas nationally. The largest reported ancestries are Chinese (25.7%) and English (11.7%). Ancestry, language and country of birth are counted only by the Census, so these are 2021 figures.
Detail
Cultural diversity is exceptionally pronounced, with 76.1% of residents having been born overseas and 65.7% speaking a language other than English at home. Christianity represents the most common religious affiliation, encompassing 29.5% of the community. However, Buddhism exhibits the most substantial relative concentration locally, accounting for 23.6% of residents in contrast to the Greater Sydney average of 4.1%. Looking at parental background, the three most common ancestral groups locally are Other at 29.7% (compared to 16.0% regionally), Chinese at 25.7% (against 8.4% across the region), and English at 11.7% (trailing the 19.0% regional share).
Notable variations also appear across other backgrounds, with Korean representing 2.9% of the population (versus 1.1% regionally), Spanish comprising 0.9% (versus 0.6%), and Russian accounting for 0.8% (versus 0.4%).
Frequently Asked Questions - Diversity
The median resident of Sydney is 31, younger than 90% of areas nationally. That is 1 year younger than at the 2021 Census. 55.5% of residents are aged 15 to 34. Age cohorts are not raw Census counts: the Census split is re-based to the latest ABS population estimates and state projections.
Detail
The local demographic structure is heavily weighted toward pre-family cohorts. Updates to August 2026 indicate that young to middle aged adults (25 - 44) make up 62.7% of the community, double the 31.4% recorded across Greater Sydney, whereas children and young adults (0 - 24) constitute 18.5% compared to 30.4% regionally. The estimated median age is 31, dropping from 32 at the 2021 Census, which sits 6 years below the Greater Sydney Census median of 37 and under the Australian Census median of 38. The share of middle aged and young retiree residents (45 - 64) has shifted from 15.1% at the Census to an estimated 12.2%.
By 2041, young to middle aged adults are projected to see the largest absolute addition, growing by 5,522 (43%) to reach 18,335, while retiree and elderly cohorts (65+) will experience the fastest proportional surge, increasing 115% to 2,949.
Frequently Asked Questions - Age
Data & MethodBoundaries, Sources & Method for Sydney
9 of 14 data sections on this page were updated within the last 12 months — the newest current to Oct 2026.
Everything is aggregated to the Suburb (SAL) boundary shown above, on a 2021 Census baseline. Only 3 sections — housing, households and cultural diversity — still wait on the 2026 Census.
The ledger — source, cycle and currency by section
| Section | Source & update cycle | Currency |
|---|---|---|
| Updated within the last 12 months 9 sections | ||
| Population | ABS, GNAF, Geoscience Australia Annual (ABS ERP) | Aug 2026 2 months ago headline measures · 2021 Census baseline |
| Re-based to the ABS Estimated Resident Population (June 2025 release) and updated with new dwellings from GNAF address data. Current to Aug 2026, with the 2021 Census supplying the small-area baseline. | ||
| Age profile | ABS, Geoscience Australia, State governments Annual | Aug 2026 2 months ago headline measures · 2021 Census baseline |
| Age cohorts are re-based to the latest ABS population estimates and state projections, current to Aug 2026. Each cohort is held as a Census baseline and a current estimate. | ||
| Development & approvals | ABS, GNAF Monthly (ABS approvals) | Aug 2026 2 months ago headline measures · Jul 2026 baseline |
| Property sales & rents | Valuer General, Rental Board, ABS Weekly sales, quarterly rents | Oct 2026 this month headline measures · Sep 2026 baseline |
| Sales from the state Valuer General register, refreshed weekly, and rents from quarterly rental bond lodgements. Both are read live each time this page loads, current to Oct 2026. | ||
| Infrastructure projects | Infrastructure Australia, State agencies, Local governments Daily | Sep 2026 last month all 30 projects tracked here |
| Project pipeline maintained continuously from Infrastructure Australia, state agencies, local government and public announcements. Records are added and revised daily; this area was last updated Sep 2026. | ||
| Employment | ABS, DEWR, JSA Quarterly (ABS SALM) | Mar 2026 7 months ago headline measures · 2021 Census baseline |
| Unemployment and labour force from ABS Small Area Labour Markets, current to Mar 2026. The growth outlook applies Department of Employment (now Jobs and Skills Australia) forecasts for all 19 industry divisions to the local industry mix, so it measures sector composition rather than local expansion and makes no allowance for population growth. Job demand comes from the same agency via its Internet Vacancy Index; industry and occupation structure from the 2021 Census. | ||
| Education | ABS, ACARA Annual (ACARA) | Sep 2026 last month headline measures · 2021 Census baseline |
| Transport | ABS, State Transport Departments Each timetable release | Jul 2026 3 months ago headline measures · 2021 Census baseline |
| Services & amenities | Provider directories, ACECQA Continuous | Sep 2026 last month all 14 measures |
| Annual and financial-year sources 2 sections | ||
| Income | ABS, ATO Annual (ATO) | FY 2023 3 years ago headline measures · 2021 Census baseline |
| ATO taxable income statistics for FY 2023, indexed forward using the Wage Price Index. Census household income provides the distribution detail. | ||
| Health | ABS, ATO Annual | 2024 2 years ago headline measures · 2021 Census baseline |
| Census-measured — next update: 2026 Census 3 sections No more current small-area source exists for these, so they are labelled as Census-measured rather than implied to be current. | ||
| Housing | ABS 5-yearly (Census) | 2021 Census next update 2026 all 30 measures |
| Households | ABS 5-yearly (Census) | 2021 Census next update 2026 all 18 measures |
| Cultural diversity | ABS, Geoscience Australia 5-yearly (Census) | 2021 Census next update 2026 all 44 measures |
"Currency" is the most recent release feeding that section. Where the Census supplies the structural baseline underneath a current headline figure, the row says so.
How the numbers are built
Population
The Census provides the small-area baseline, aggregated from mesh blocks to this boundary. It is then re-based to the ABS Estimated Resident Population (June 2025 release), and new dwellings built since Census night are counted from address data — 596 validated new addresses here. The headline figure is therefore a current estimate for Aug 2026, not a 2021 count (16,667 at the 2021 Census → 20,435 now). Annual growth rates are compound (CAGR), not simple averages.
Age profile
Cohort shares are not raw Census counts. Every cohort is held as a pair — the Census baseline and a current estimate — and the split is re-based using ERP and state population projections, current to Aug 2026. Median age is the Census median plus modelled change since. Charts that show both are labelled "2021 Census vs Current Estimate".
Property sales
Sourced from the state valuation authority's sales register — current, not Census, and refreshed weekly. Medians are calculated from settled transactions in the period shown; periods with very low transaction counts are flagged or suppressed, because a handful of sales can move a median substantially.
Rents
Derived from state rental bond lodgement data, by dwelling type and bedroom count. Bonds are lodged at the start of a new tenancy, so this reflects new lettings, not the whole rented stock.
Development & infrastructure
Building approvals come from current ABS releases; development applications are collected from council and state planning portals; the infrastructure pipeline is compiled from Infrastructure Australia and local government sources. Applications are matched to this boundary by address or coordinates, so very recent lodgements may not yet appear.
Employment & income
Industry and occupation structure comes from the Census, but the headline labour-market indicators do not. Unemployment and labour force are derived from ABS Small Area Labour Markets (quarterly). The employment outlook applies Department of Employment forecasts for all 19 industry divisions to this area's own industry mix (the agency is now Jobs and Skills Australia), as does the Internet Vacancy Index used for job demand. Because it is weighted on industry composition alone, that outlook carries no allowance for local population growth — in fast-growing areas the real rise in local jobs will typically be higher. Income combines Census household income with ATO taxable-income statistics for FY 2023, indexed forward using the Wage Price Index.
Education, transport & amenities
School enrolments, ICSEA and performance come from ACARA's current release, not the Census. Public transport stops and service frequency are derived from GTFS timetable feeds published by state transport departments. Services and amenities are proximity and count scores built from provider directories, refreshed on their own cycle. The Census contributes only the travel-to-work and qualification measures.
Rankings and benchmarks. Where we rank this area, the comparison set is every area of the same boundary type — suburbs against suburbs, SA2s against SA2s. Benchmarks compare this area against its greater capital city region and the national figure for the same measure and period.
Limits worth knowing. Small areas carry larger error margins, and the ABS introduces small random adjustments to Census counts to protect confidentiality — so totals may not sum exactly. Estimates re-based from regional data describe the area's expected trajectory, not a direct count of it. Figures are indicative for research and are not financial, planning or valuation advice.
Cross-check us. The Census baseline for this boundary is at ABS 2021 Census QuickStats (SAL13730). QuickStats reports 2021 only — the figures on this page are more current wherever the ledger shows a later date.