Chart Color Schemes
This analysis uses Suburbs and Localities (SAL) boundaries, which can materially differ from Statistical Areas (SA2) even when sharing the same name.
SAL boundaries are defined by Australia Post and the Australian Bureau of Statistics to represent commonly-known suburb names used in postal addresses.
Statistical Areas (SA2) are designed for census data collection and may combine multiple suburbs or use different geographic boundaries. For comprehensive analysis, consider reviewing both boundary types if available.
est. as @ -- *
2021 Census | -- people


The median unit price in Macquarie Park is $883k. House values have moved 0.0% a year compounded over five years.
Curious about local property values? Filter the chart to assess the volume and appreciation (including resales) trends and regional comparisons, or scroll to the map below view this information at an individual property level.
Find a Recent Sale

Sales Detail
Macquarie Park has an estimated 17,349 residents, up from 11,071 at the 2021 Census — a change of 6,278 people, or 56.7%. Growth has averaged 9.7% a year over five years, faster than 98% of areas nationally. 2,168 new addresses have been validated here since Census night. Overseas migration accounts for 92.0% of that increase. That puts 2,566 residents on each square kilometre. Population is estimated from ABS Estimated Resident Population releases and GNAF address data, re-based from the 2021 Census and updated annually.
Detail
According to AreaSearch's evaluation of regional ABS updates alongside newly validated post-Census addresses, the suburb of Macquarie Park has reached an estimated population of approximately 17,349 as of Aug 2026. This represents a substantial rise of 6,278 people (56.7%) from the 11,071 residents recorded during the 2021 Census. These figures draw on an estimated resident population of 17,191 determined from the ABS June 2025 ERP release, coupled with 2,168 validated new addresses added following the Census. The suburb's density stands at 2,566 persons per square kilometer, placing it within the top quartile of nationally assessed regions.
With a 56.7% expansion rate since the 2021 census, the suburb of Macquarie Park outpaced both New South Wales (7.3%) and Greater Sydney, establishing itself as a standout regional growth center. This upward trajectory was largely underpinned by net overseas migration, which accounted for roughly 92.0% of the overall population additions in recent times. Projections for the suburb of Macquarie Park incorporate 2024 ABS/Geoscience Australia data at the SA2 level (using 2022 as a base), supplemented where necessary by 2022 NSW State Government SA2 projections (using 2021 as a base). Projected age-cohort growth rates derived from these models are similarly applied across the 2032 to 2041 horizon. Looking ahead, demographic forecasts place the suburb of Macquarie Park in the top 10 percent of statistical areas across Australia, with an anticipated gain of 13,958 persons by 2041 based on SA2 aggregations, corresponding to an overall 16-year increase of 79.5%.
Frequently Asked Questions - Population
2,925 new dwellings have been approved in Macquarie Park over the past five years, an average of 585 a year. That places the area in the 99th percentile for residential development activity nationally, about 34 approvals per 1,000 residents a year. Of the 457 dwellings approved in the latest reporting year, 3% were detached houses and the rest townhouses or apartments. Approvals are currently running at an annualised 809, running ahead of that longer-run average. Figures come from ABS building approvals aggregated to this Suburb (SAL) boundary and are updated monthly as the ABS releases them.
Detail
Analysis of ABS building approvals by AreaSearch shows that the local area has seen roughly 585 residential dwellings approved per year, accumulating to approximately 2,925 approved residences across the preceding 5 financial years. Within FY-25 to date, 809 approvals have been logged. Between FY-21 and FY-25, an average of 2.9 new residents were added for every home constructed, pointing to robust underlying demand favorable for property values. New residential construction costs average $433,000 per dwelling, in line with wider regional building figures. Concurrently, commercial building approvals have reached $623.9 million during this financial year, underscoring strong local non-residential development activity.
Per capita residential construction activity in the area outstrips Greater Sydney by 233.0%, ensuring substantial choice for prospective purchasers. This elevated building rate also significantly exceeds national averages, reflecting robust developer interest. The pipeline comprises 3.0% detached houses alongside 97.0% medium and high-density formats. Emphasizing higher-density stock offers accessible price points catering to first-time buyers, downsizers, and property investors. A ratio of approximately 25 people per approval underscores the ongoing urbanization of the area. According to the most recent AreaSearch quarterly projections, the local population is set to expand by 13,800 residents by 2041. Given prevailing development patterns, the anticipated residential supply pipeline appears well positioned to absorb incoming demand, creating favorable buyer conditions and potentially supporting population growth above existing baseline forecasts.
Frequently Asked Questions - Development
Development applications around Macquarie Park
Loading development applications…
| Lodged | Address | Description | Type | Distance | Status |
|---|
SOURCE: Planning portals and council registers, compiled by AreaSearch. Distance & bearing measured from the suburb midpoint.
AreaSearch tracks 36 current infrastructure and development projects inside Macquarie Park, worth an estimated $25.8 billion. A further 65 sit in the immediately surrounding suburbs, taking the tracked pipeline within reach of the area to $43.4 billion. 26 are already under construction and 48 are due for completion within three years. The pipeline spans residential development, communities, precincts & urban renewal and education & training. Records are compiled from Infrastructure Australia, state agencies, council planning portals and public announcements, reviewed and updated daily, then ranked by proximity, construction stage, completion horizon and project scale.
Detail
Local capital expenditure and planning developments serve as critical drivers of area performance, with AreaSearch cataloging 51 key infrastructure initiatives slated to influence the precinct. Major developments include the Macquarie Centre Redevelopment, MCentral Macquarie Park, Herring Road, Macquarie Park, and the Macquarie Park Bus Depot.
Professional plan users can use the search below to filter and access additional projects.
INFRASTRUCTURE SEARCH
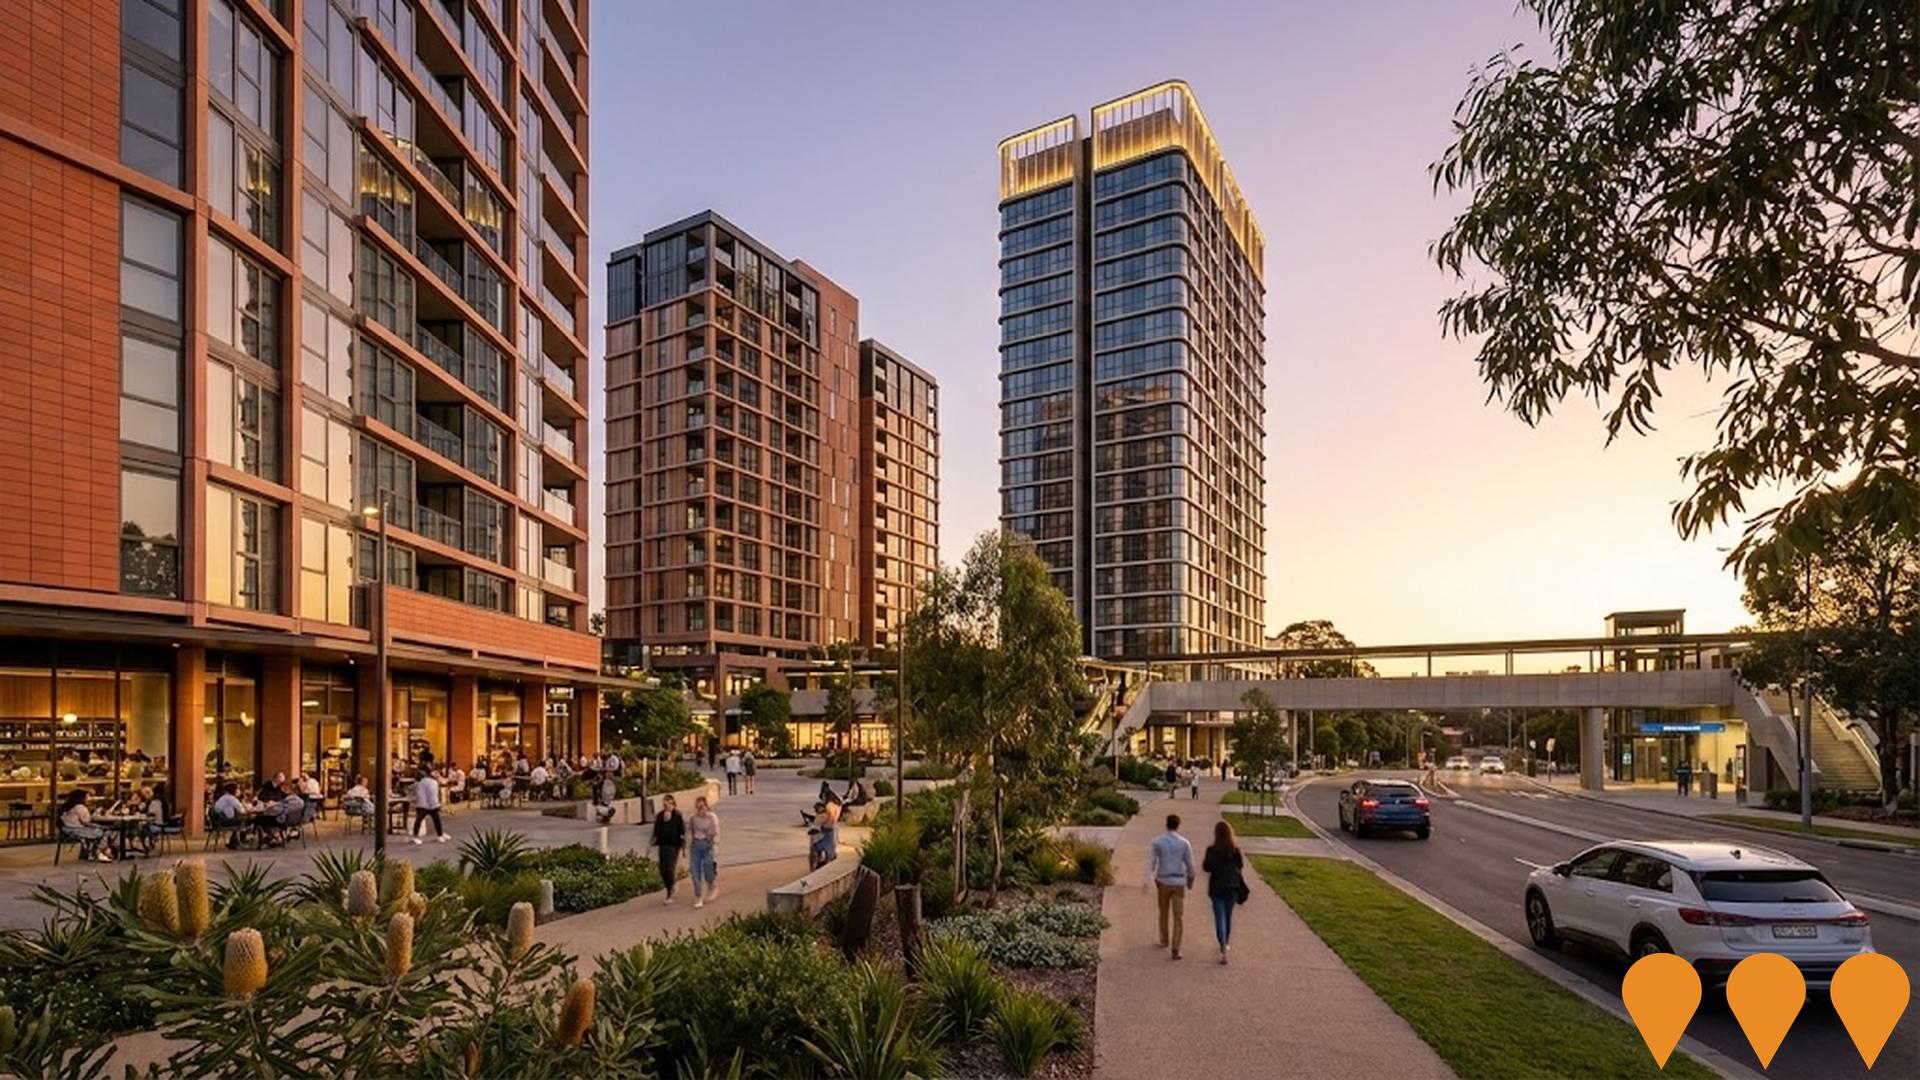
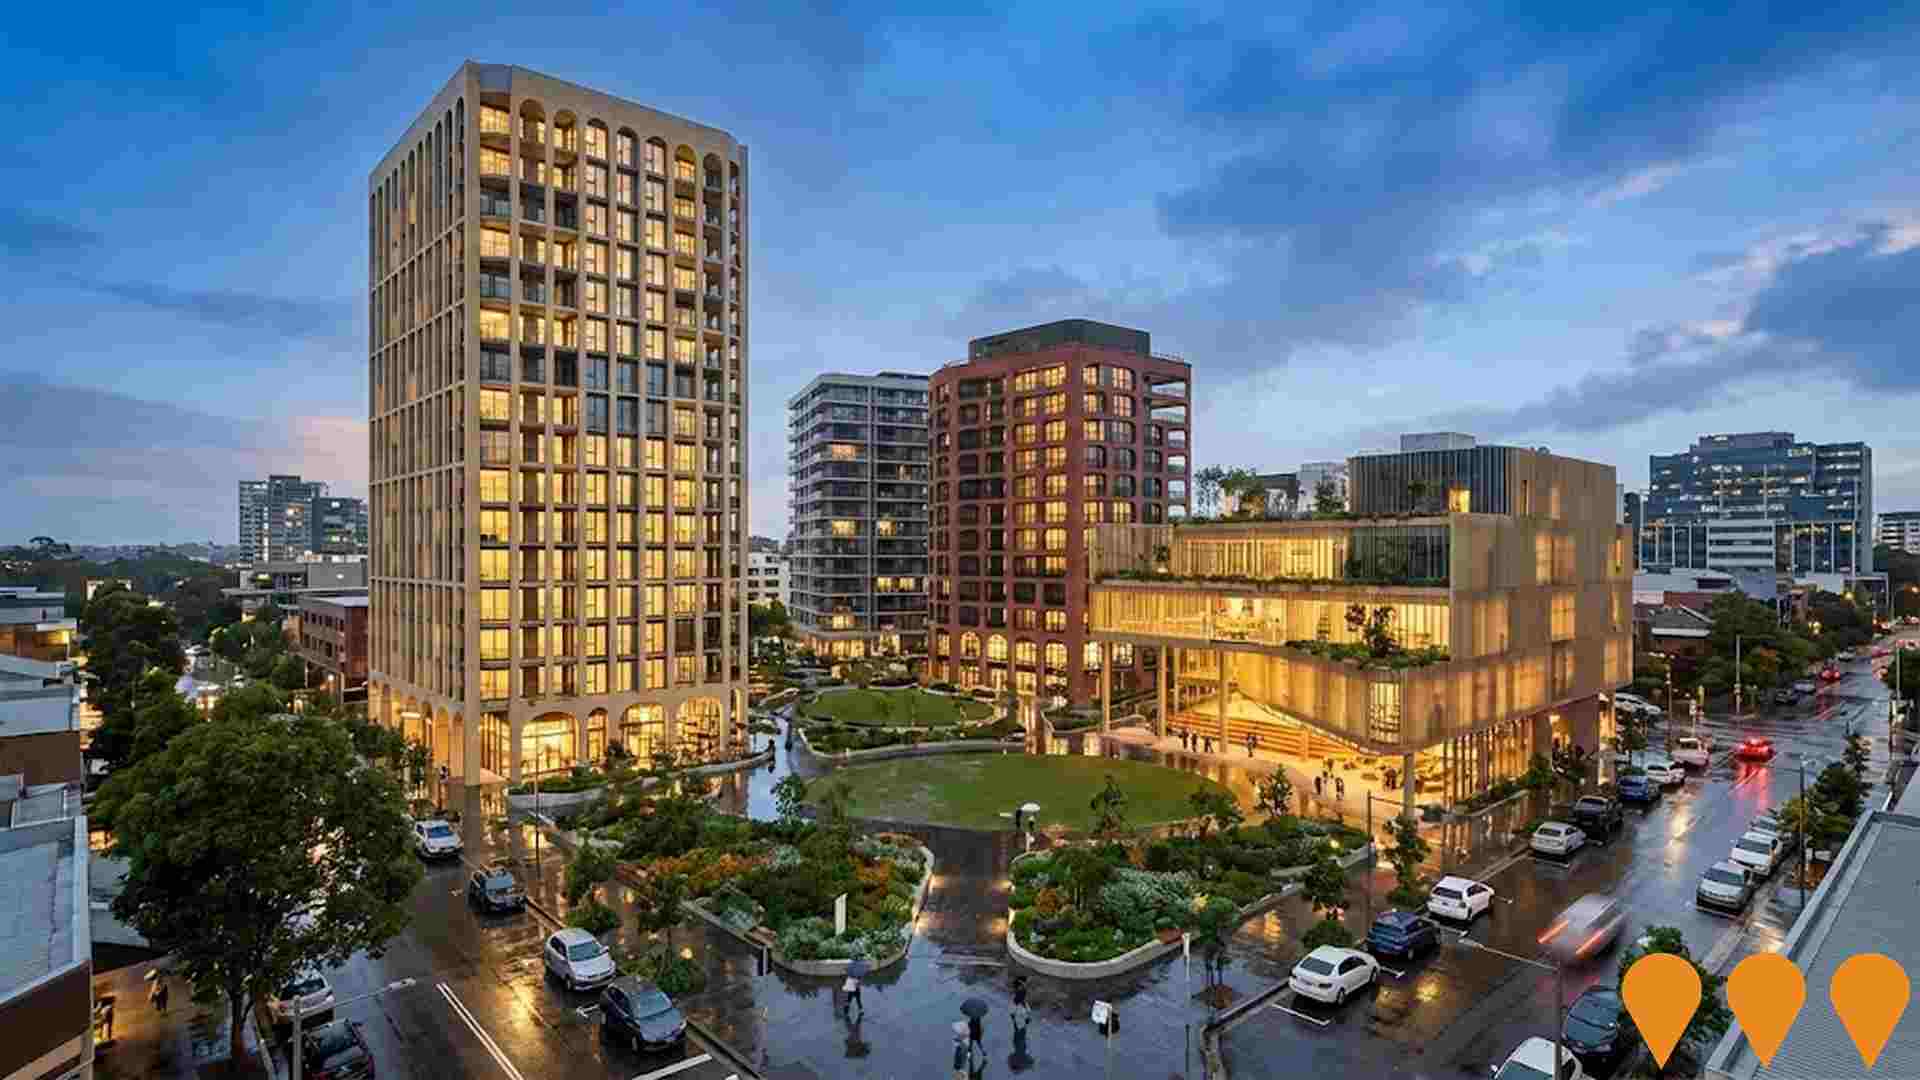
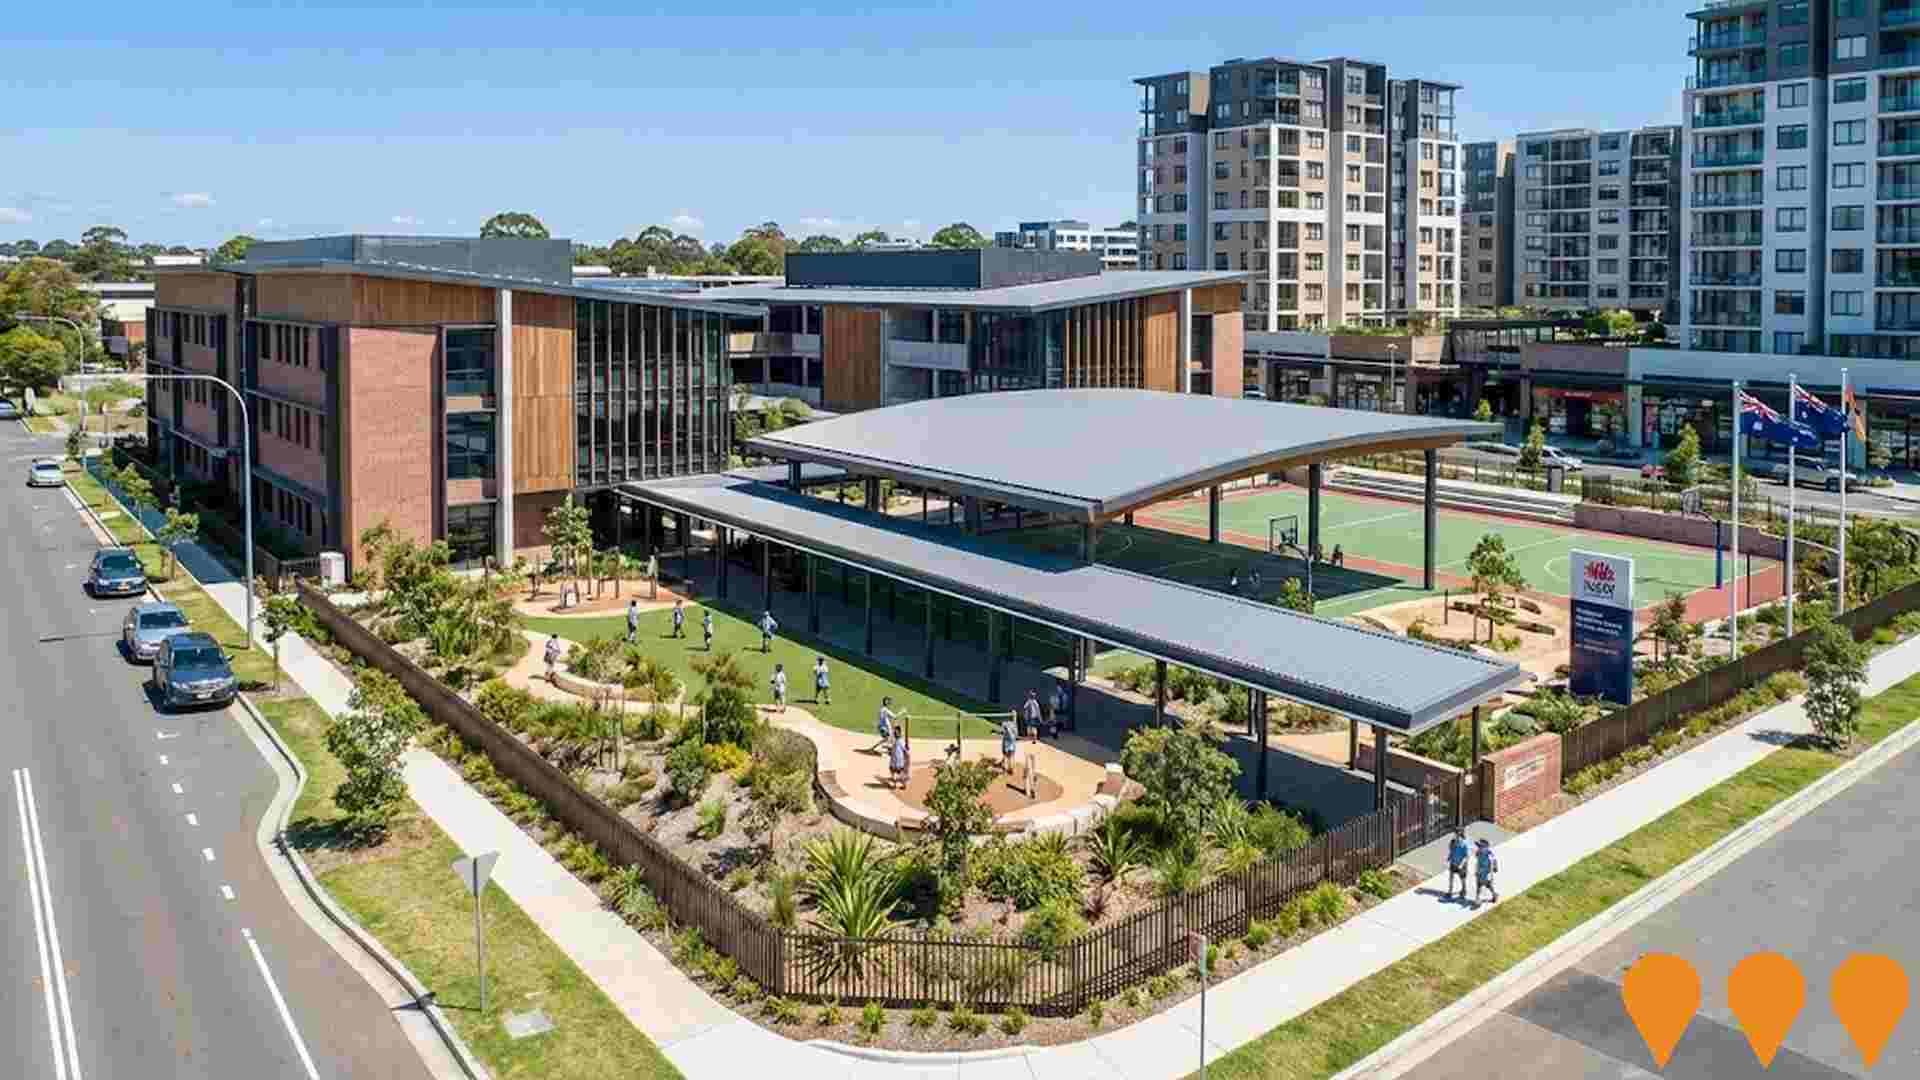
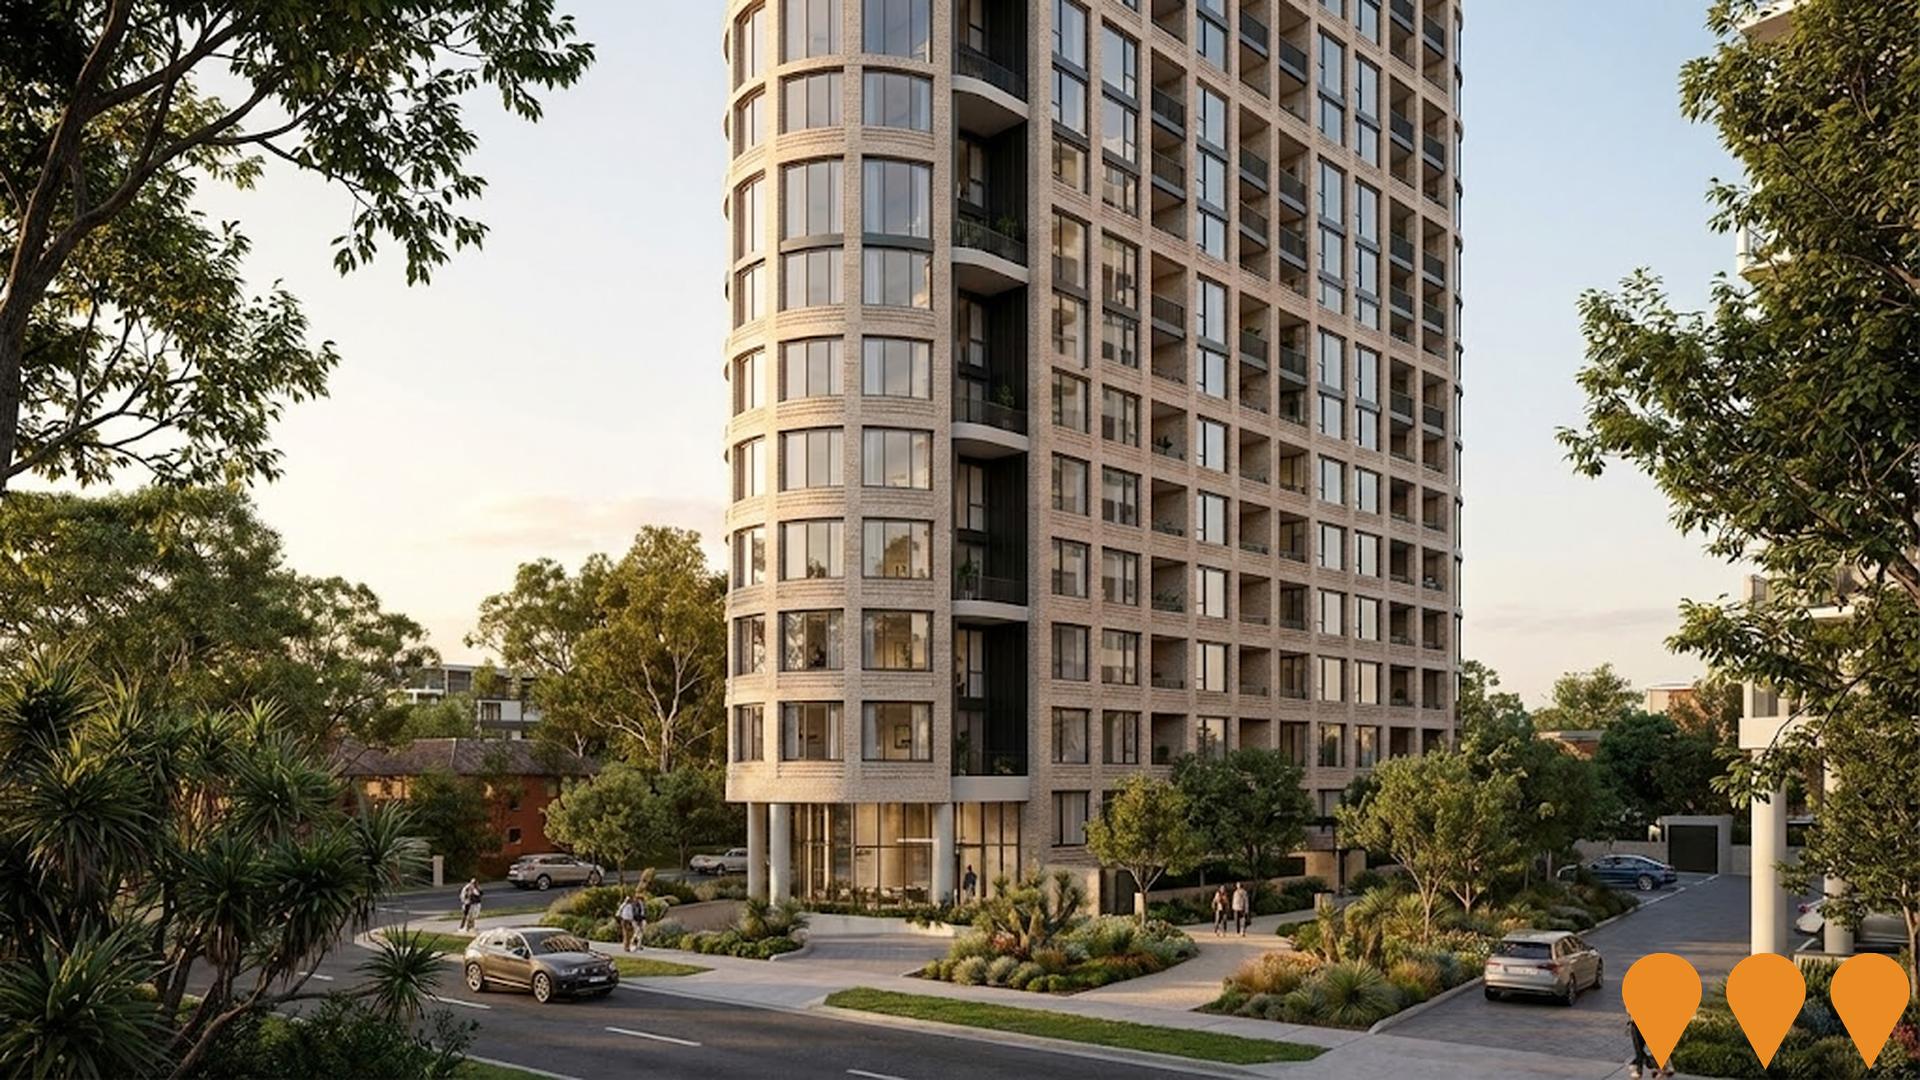
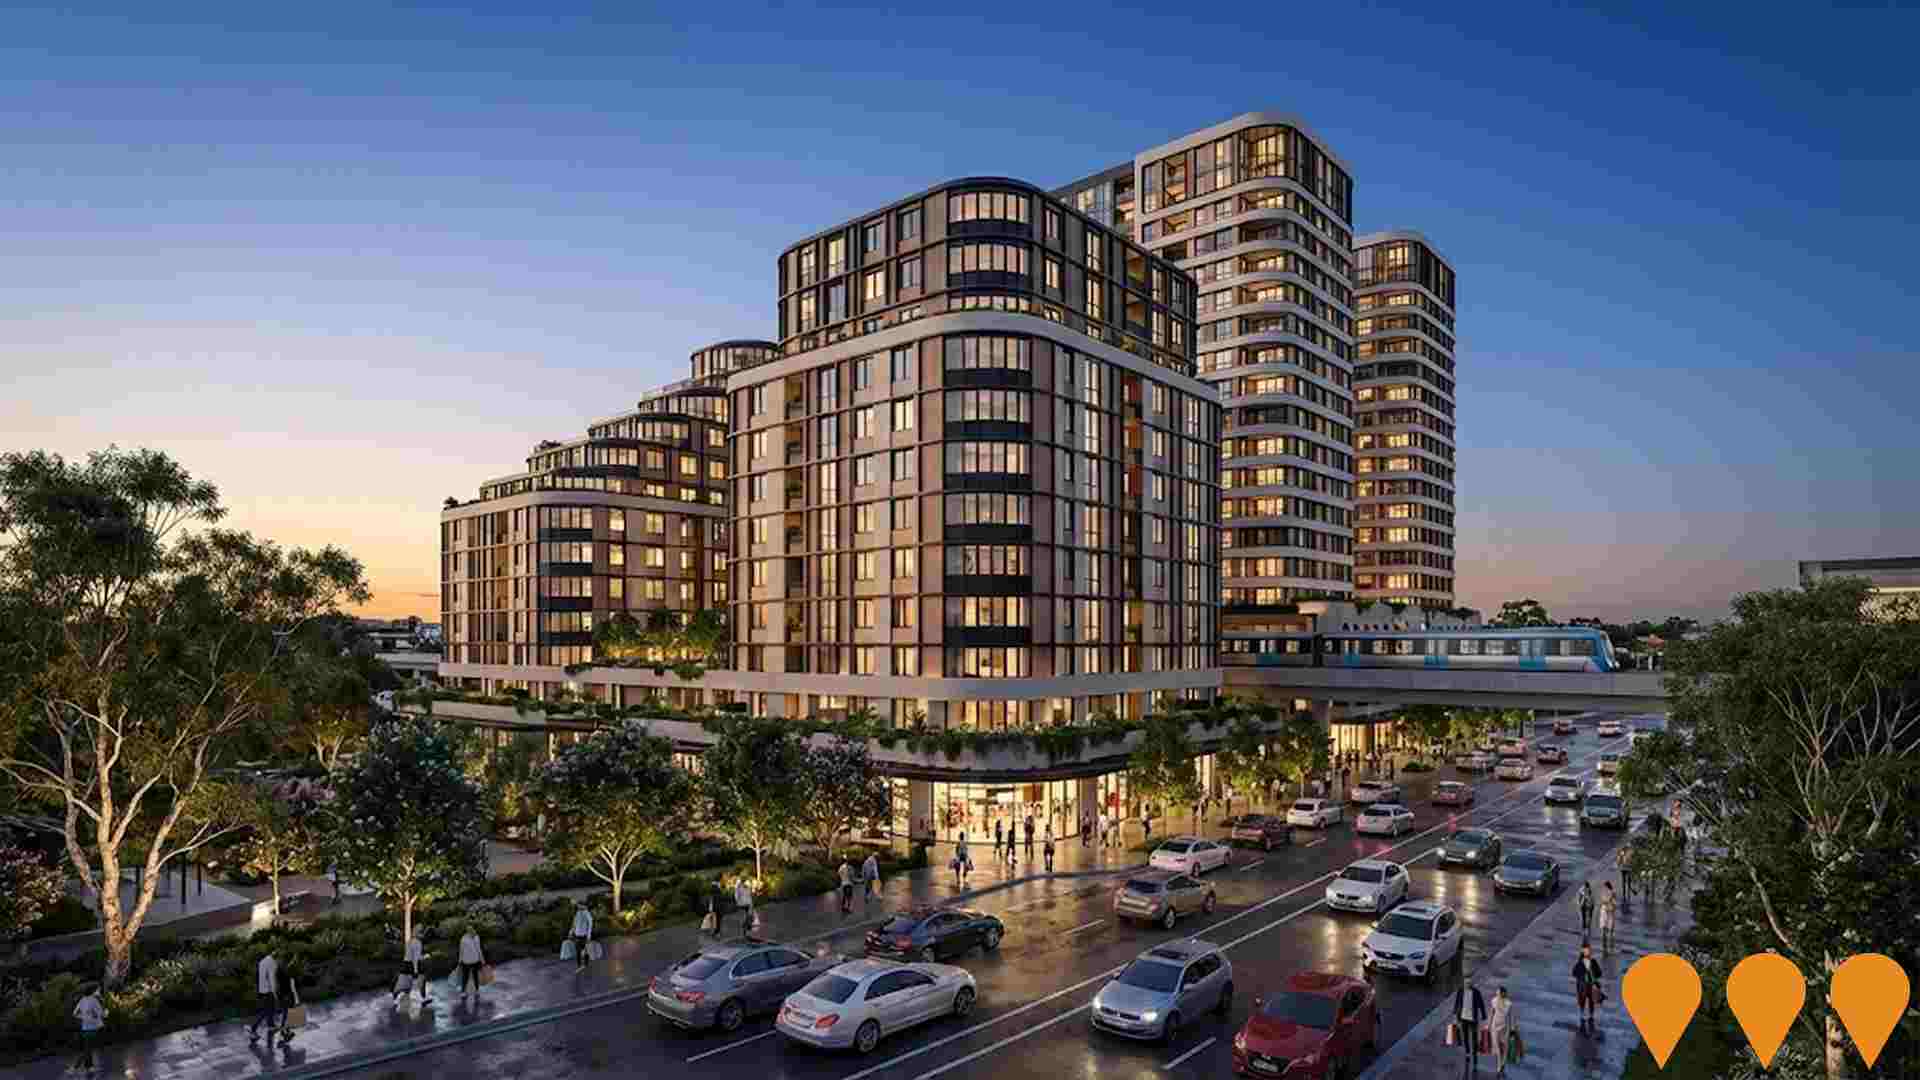
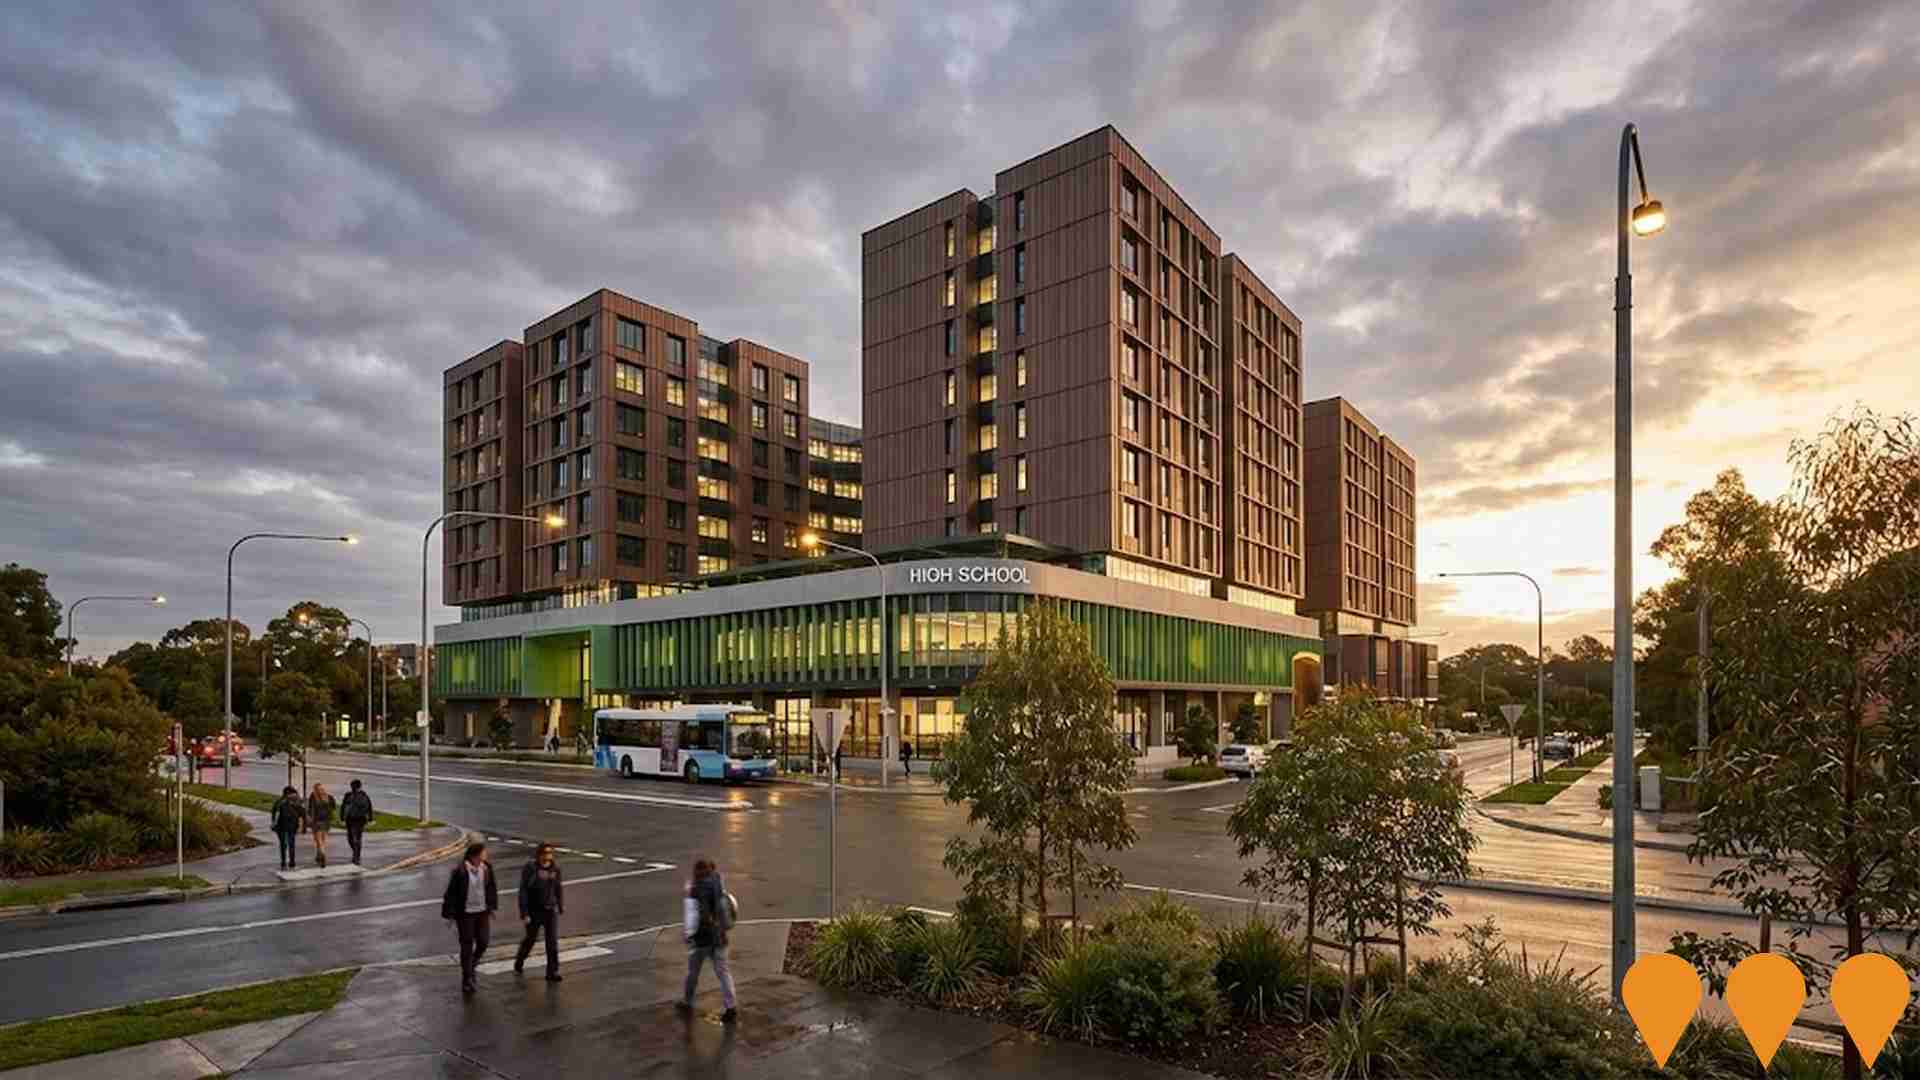
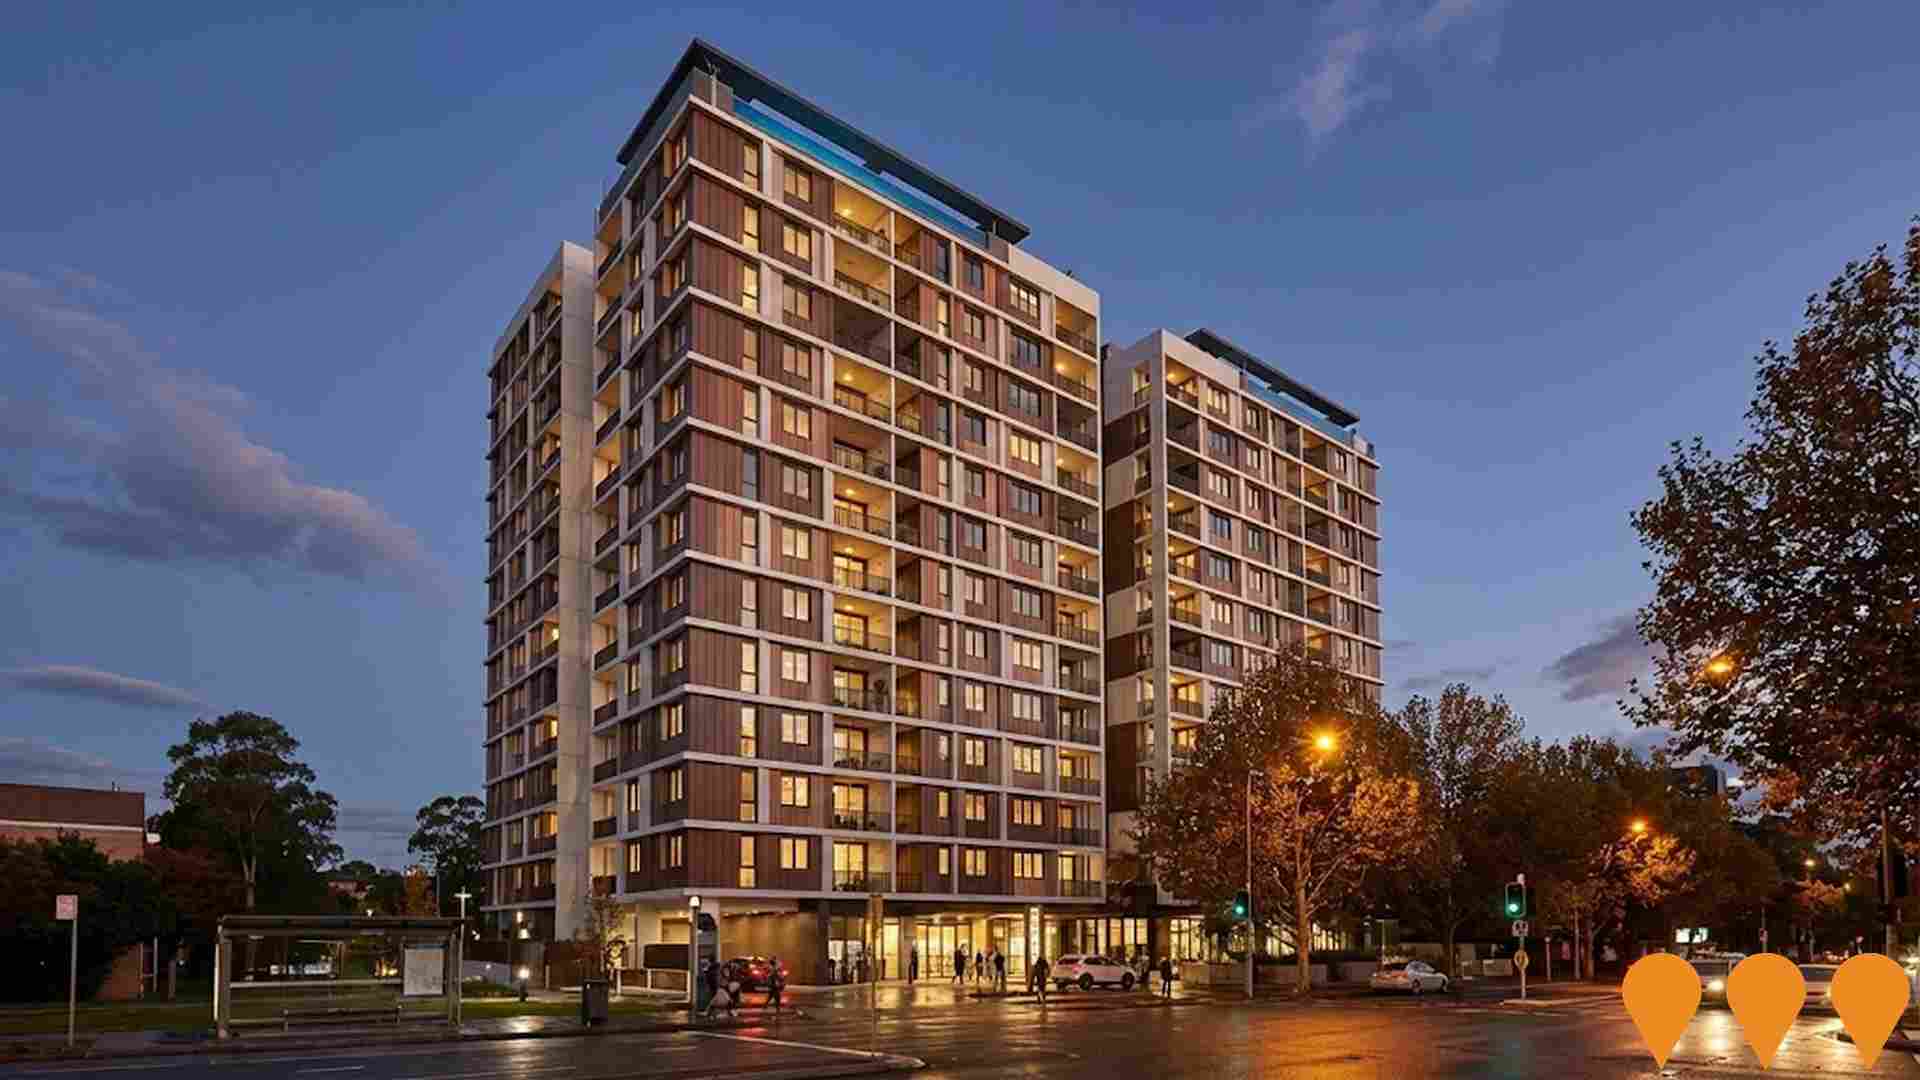
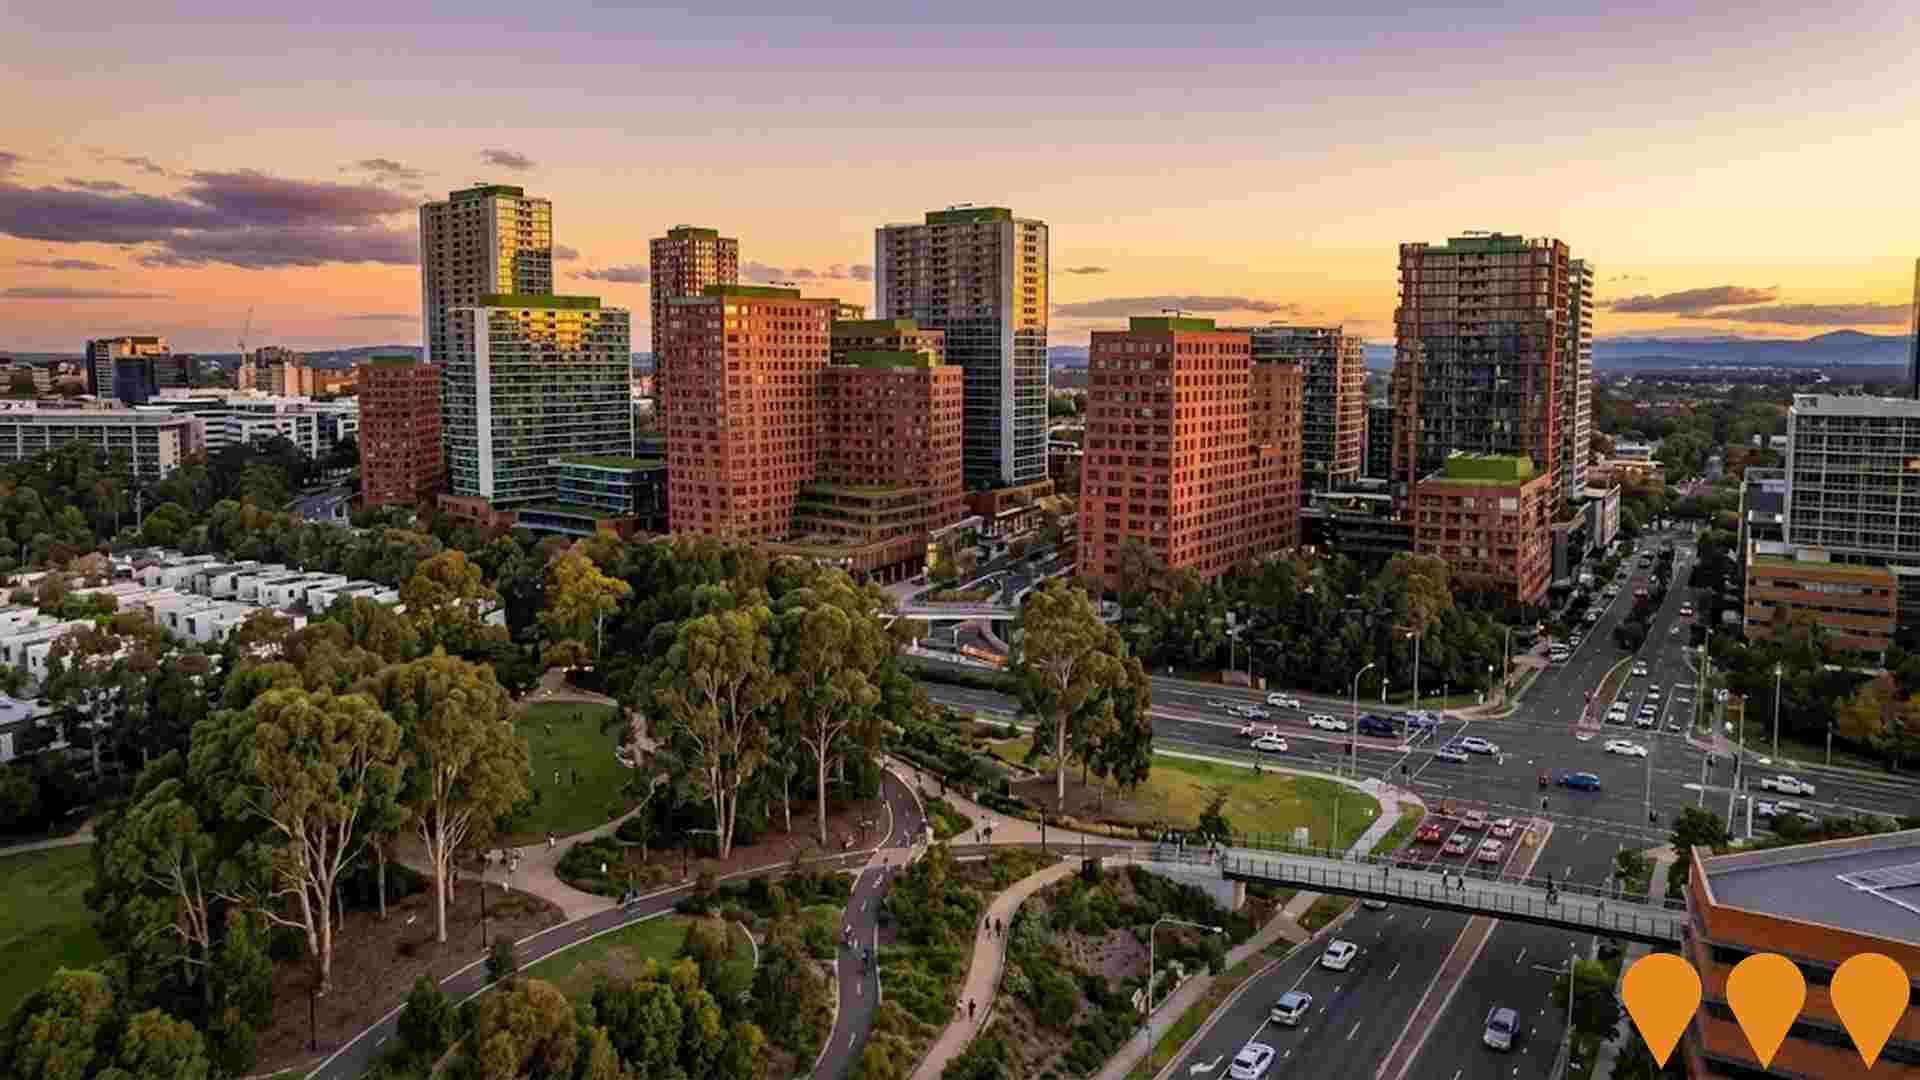
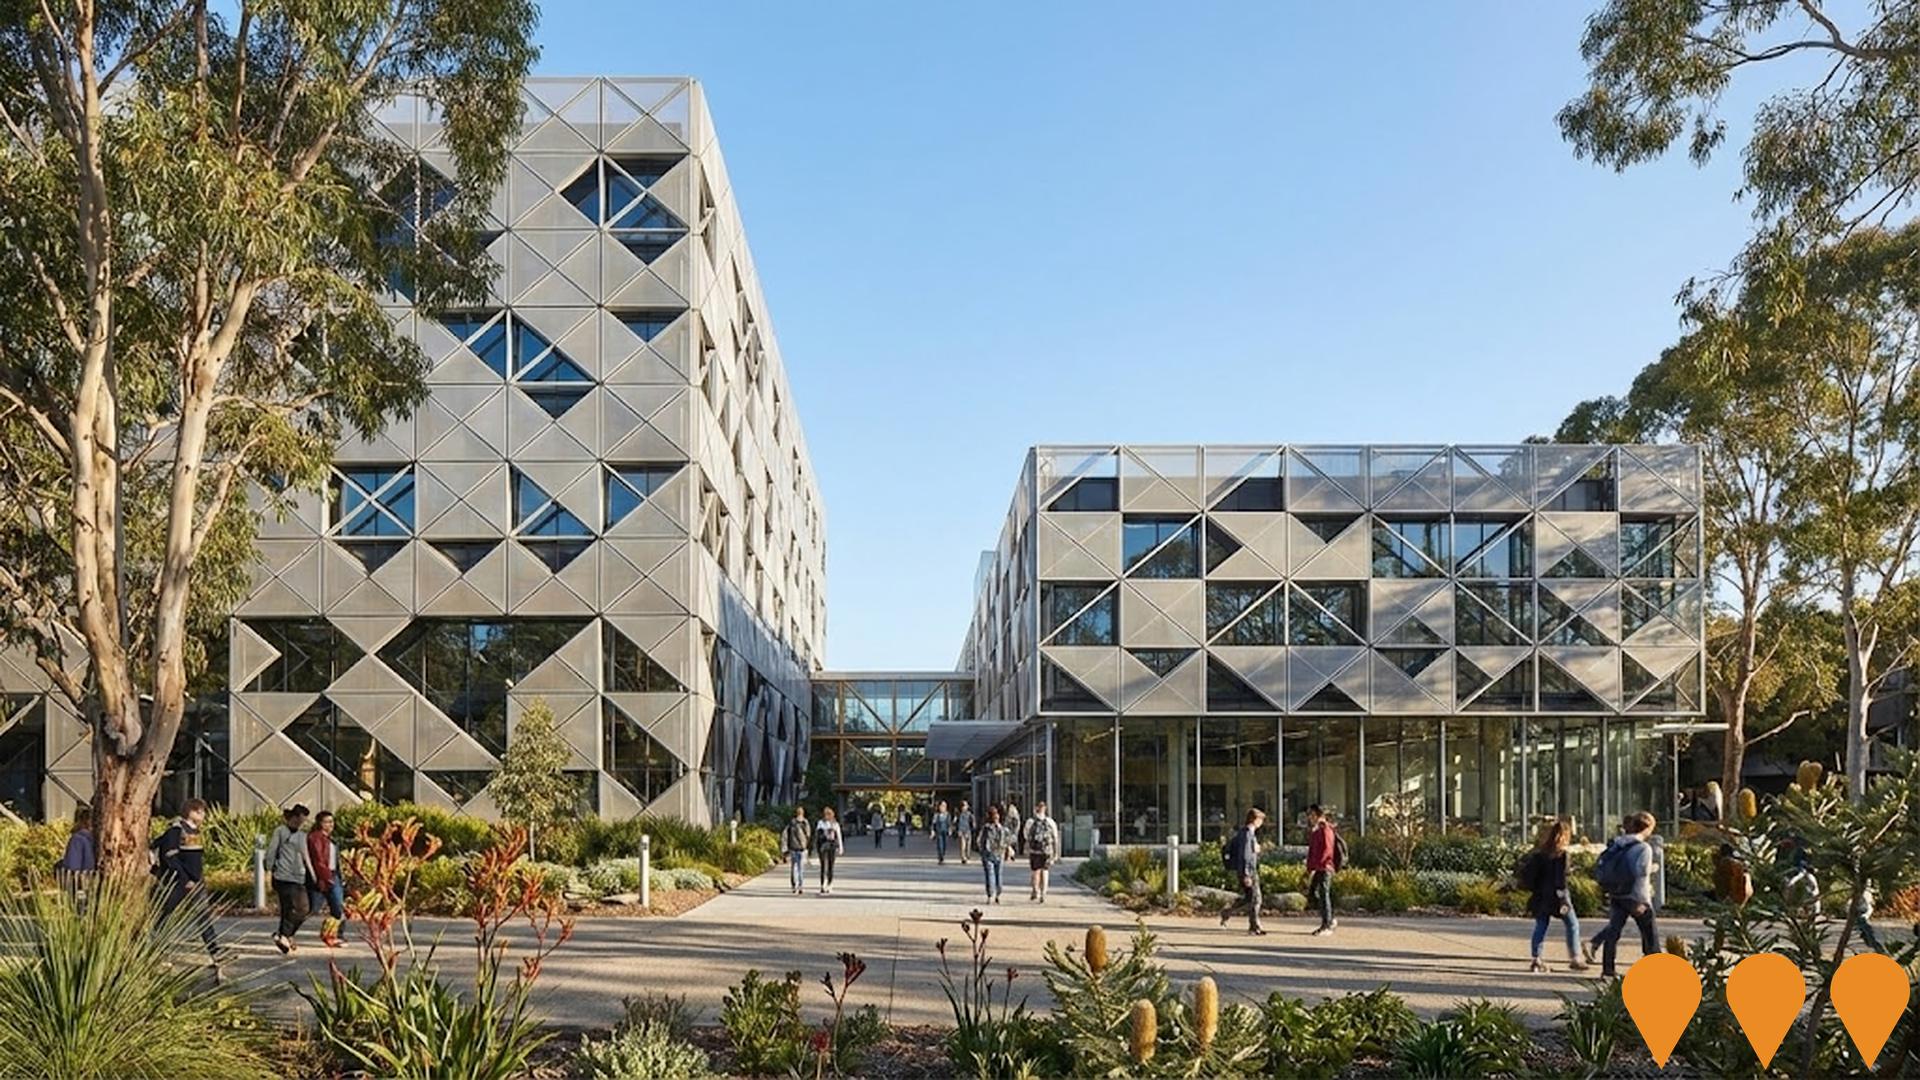
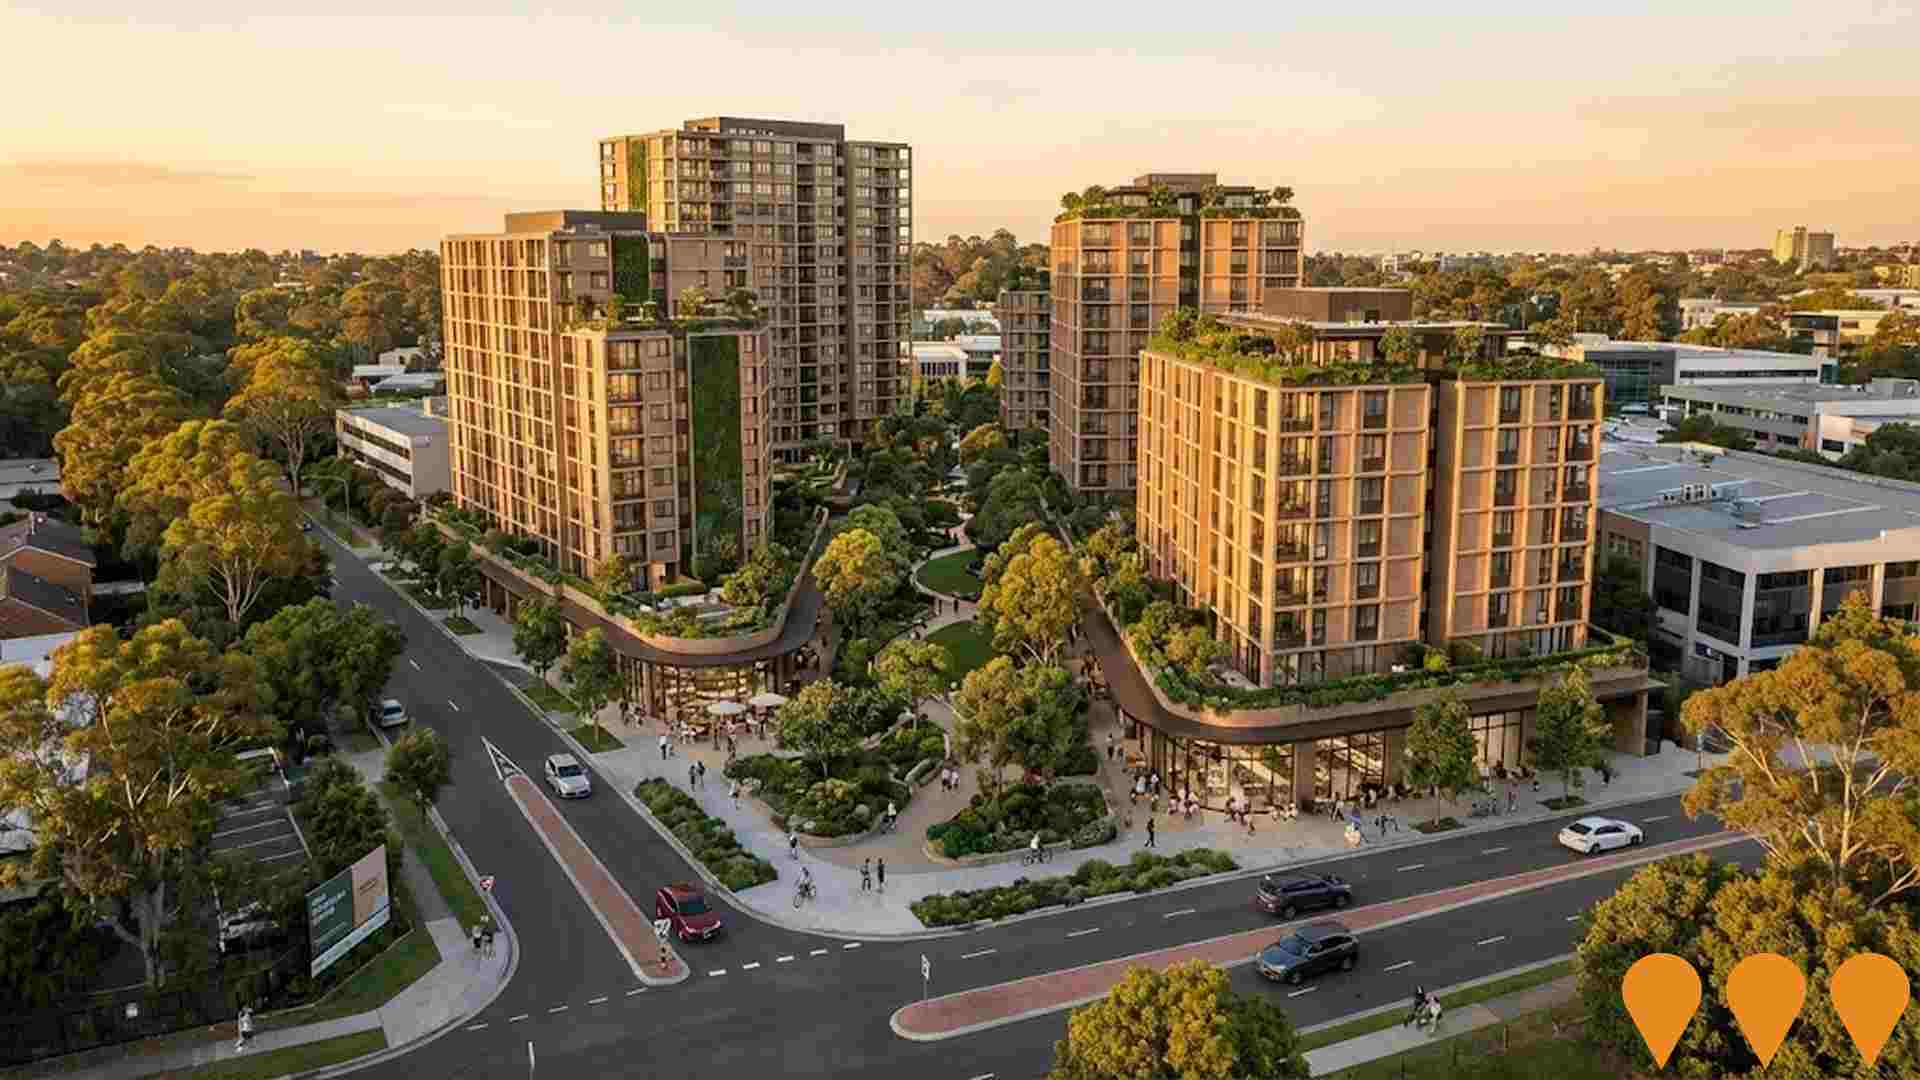
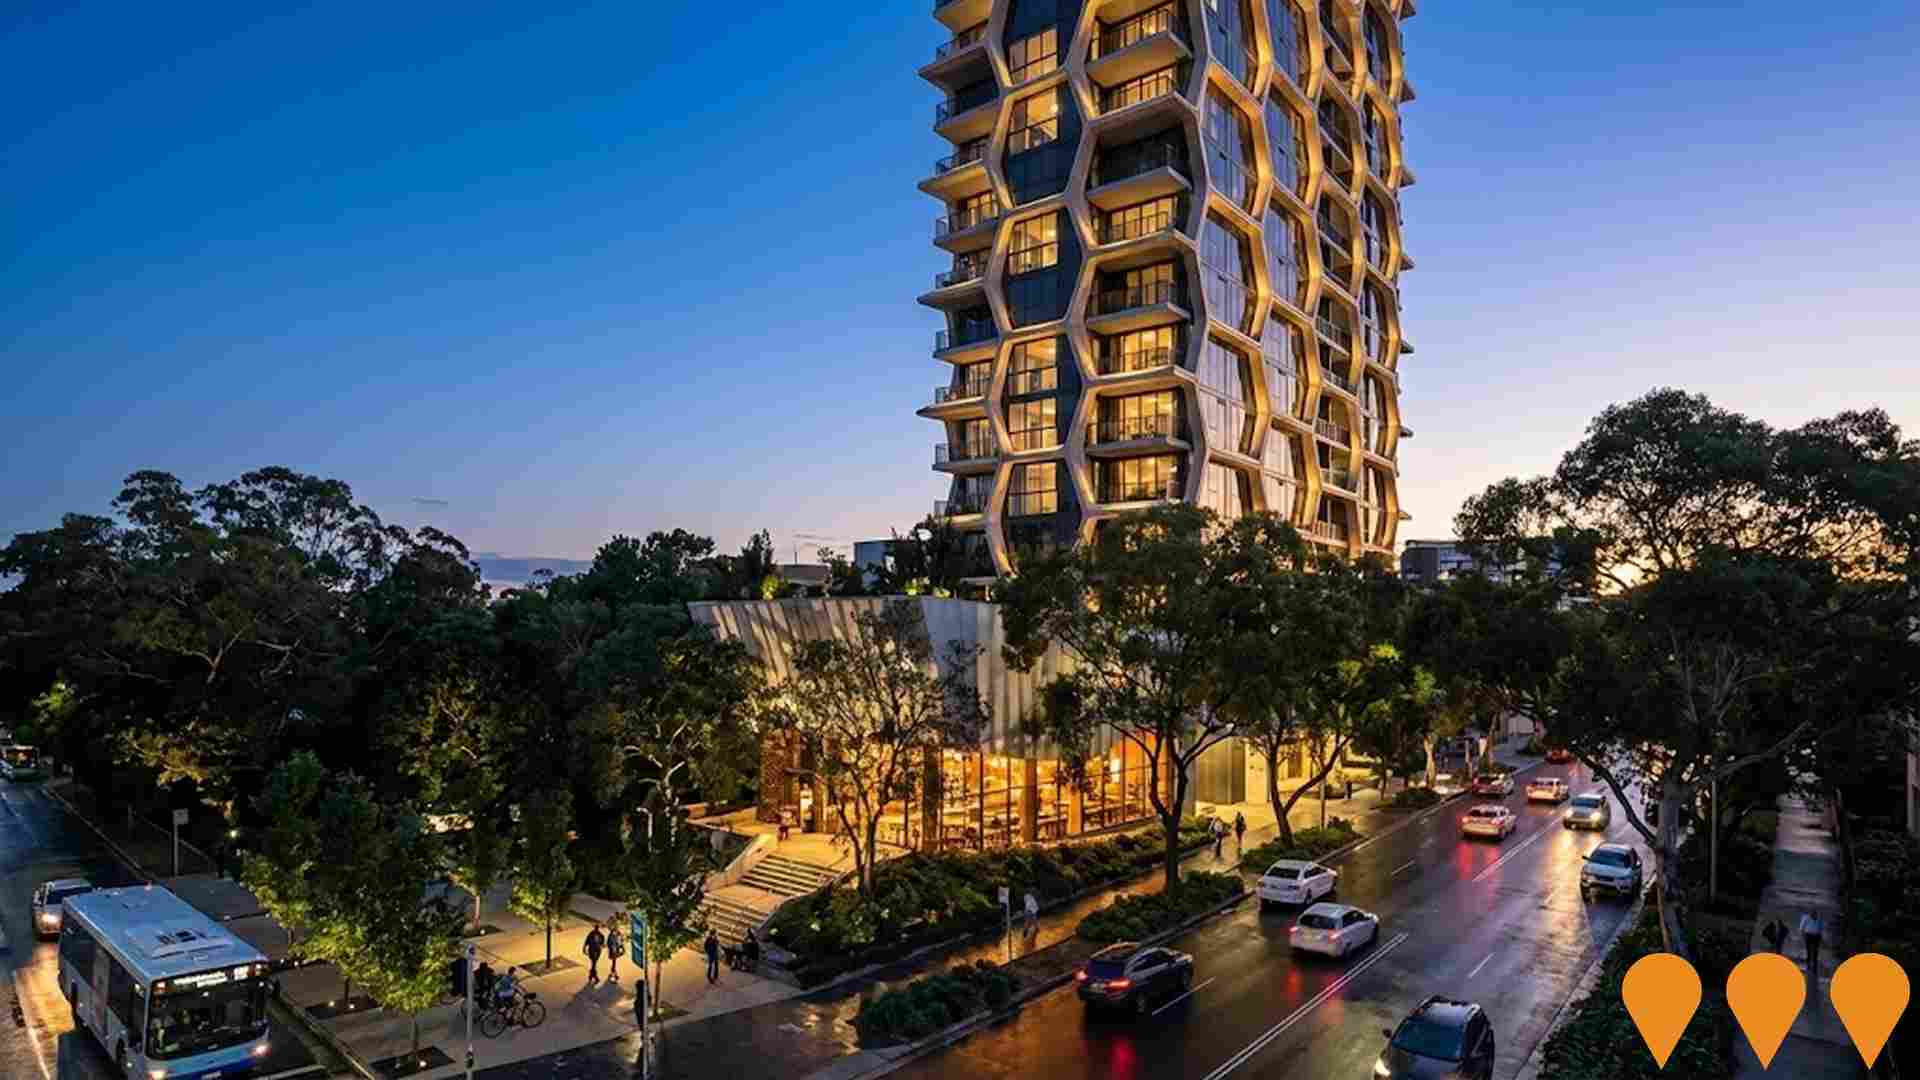
 Denotes AI-based impression for illustrative purposes only, not to be taken as definitive under any circumstances. Please follow links and conduct other investigations from the project's source for actual imagery. Developers and project owners wishing us to use original imagery please Contact Us and we will do so.
Frequently Asked Questions - Infrastructure
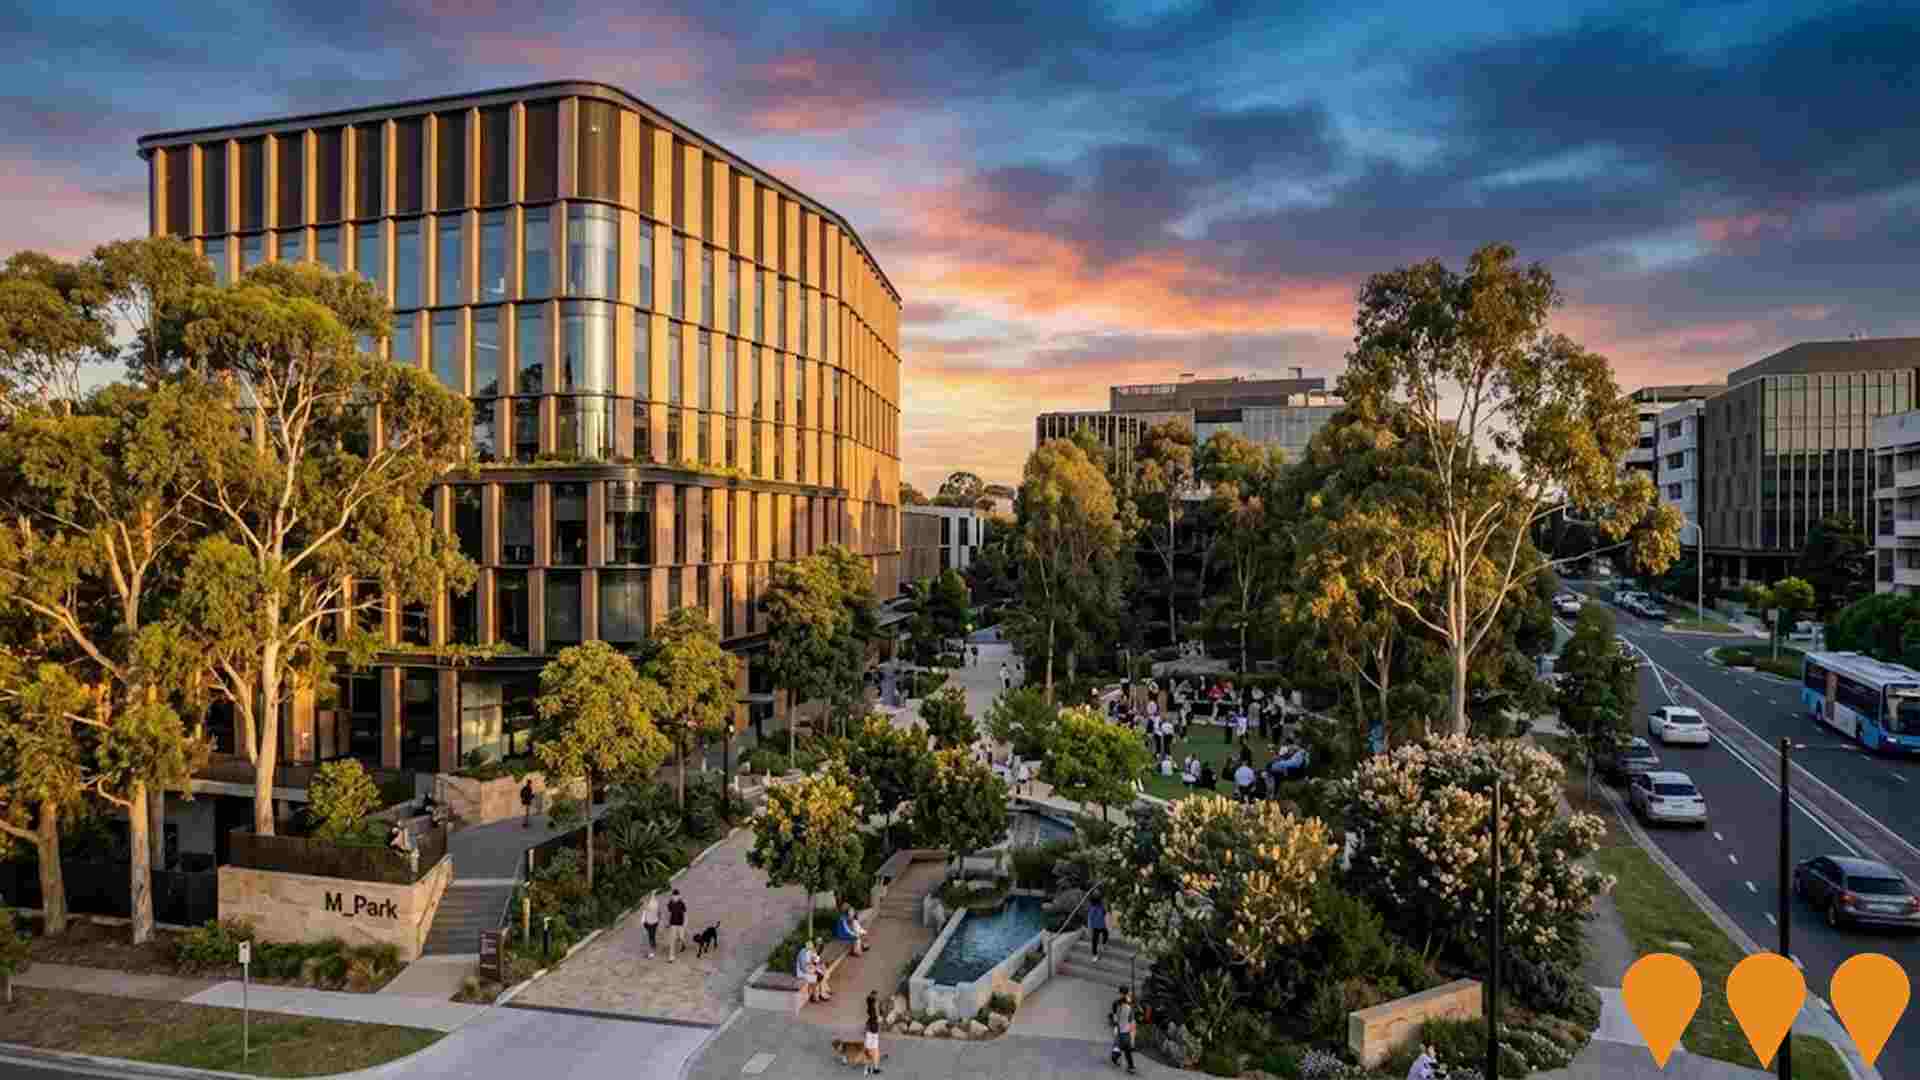
M_Park Macquarie Technology Centre
Stockland's approximately $2 billion M_Park is a multi-stage life sciences and technology innovation precinct in the Macquarie Park Innovation District. Stage 1 includes three premium commercial buildings, a data centre, retail and hospitality, and a 2,500 sqm public park. Building 11 is operational with tenants including CHEP, Demant and WiSE Medical, while Buildings 15 and 17, including Johnson & Johnson's new Australian headquarters, are in the final stages of construction.
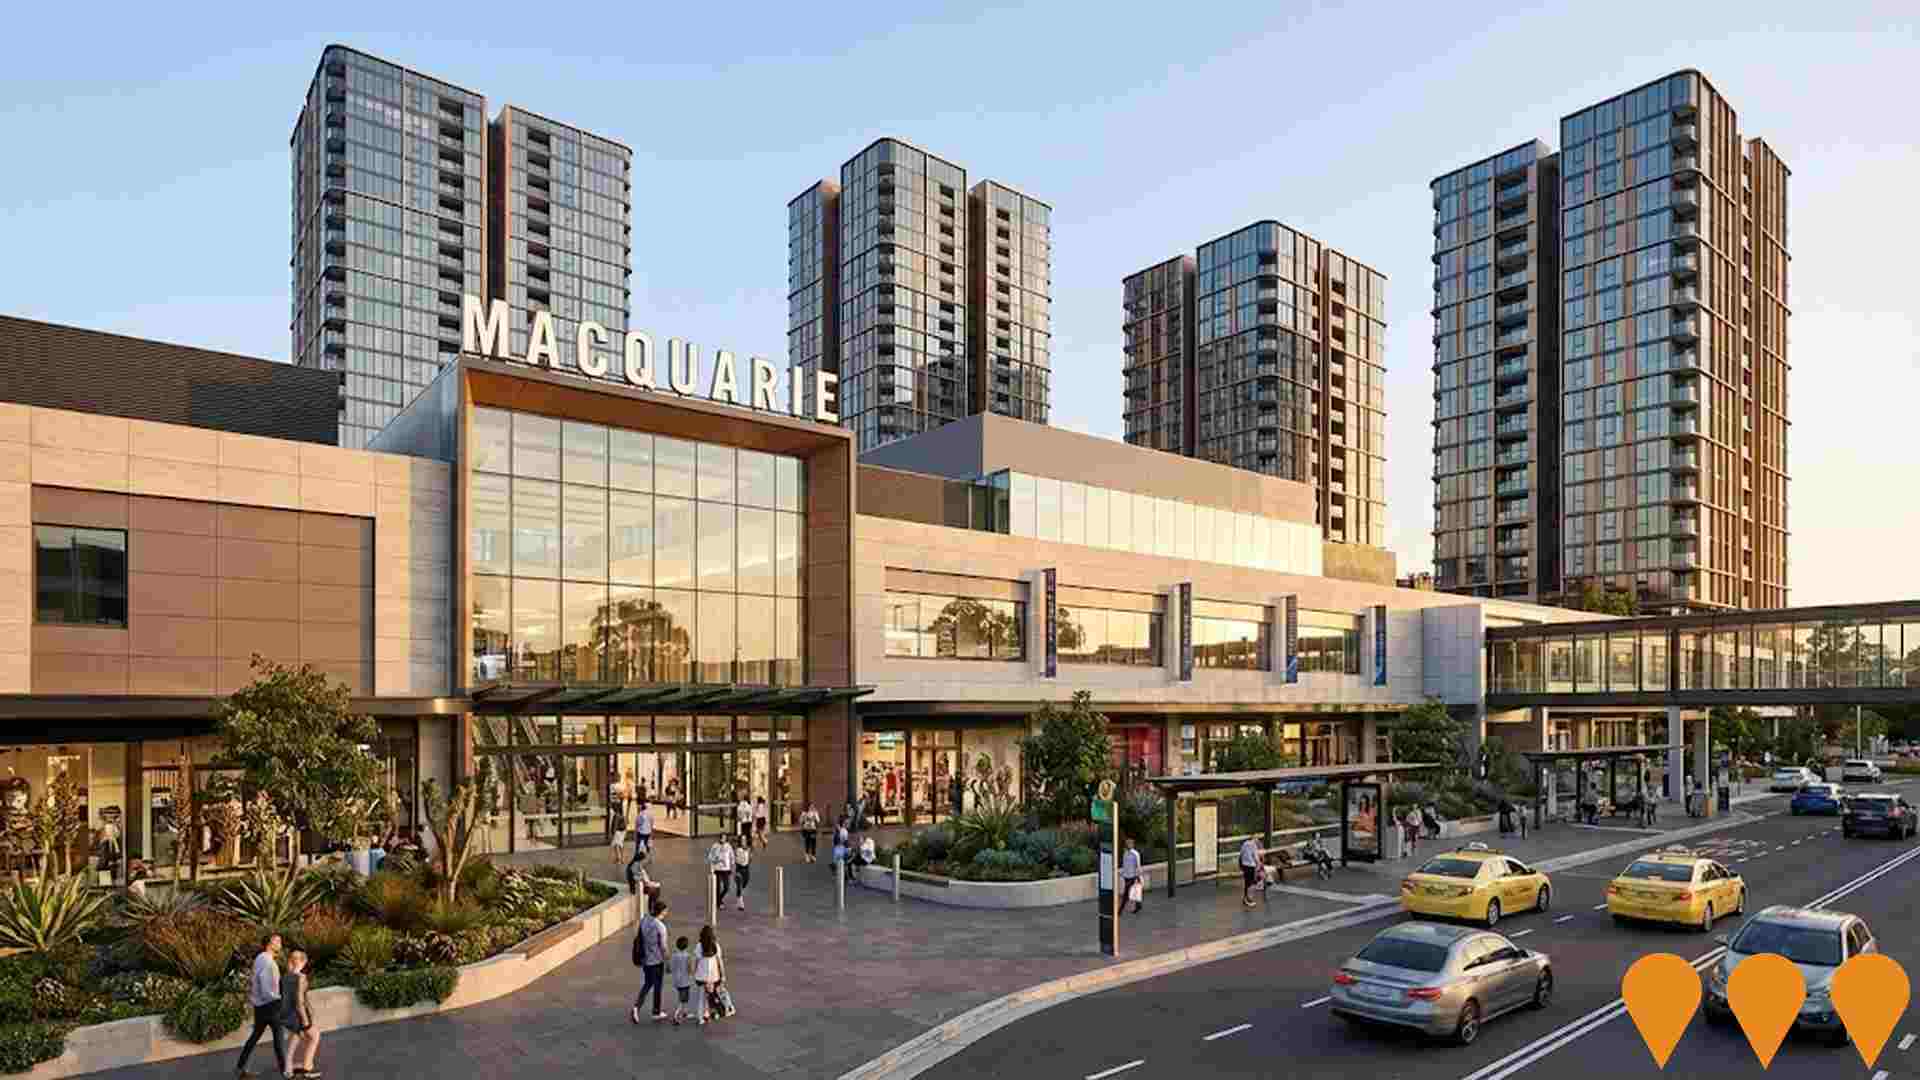
Macquarie Centre Redevelopment
A major $1 billion mixed-use expansion of Macquarie Centre. As of 2026, the project is in construction with a $400 million retail expansion underway to create Australia's largest retail footprint by 2027. The masterplan includes four residential towers ranging from 26 to 33 storeys providing approximately 1,000 apartments, 130 new specialty stores, an Olympic-sized ice rink, and 5,000sqm of community facilities. The development provides direct integration with the Macquarie University Metro station and the Macquarie Park Innovation District.
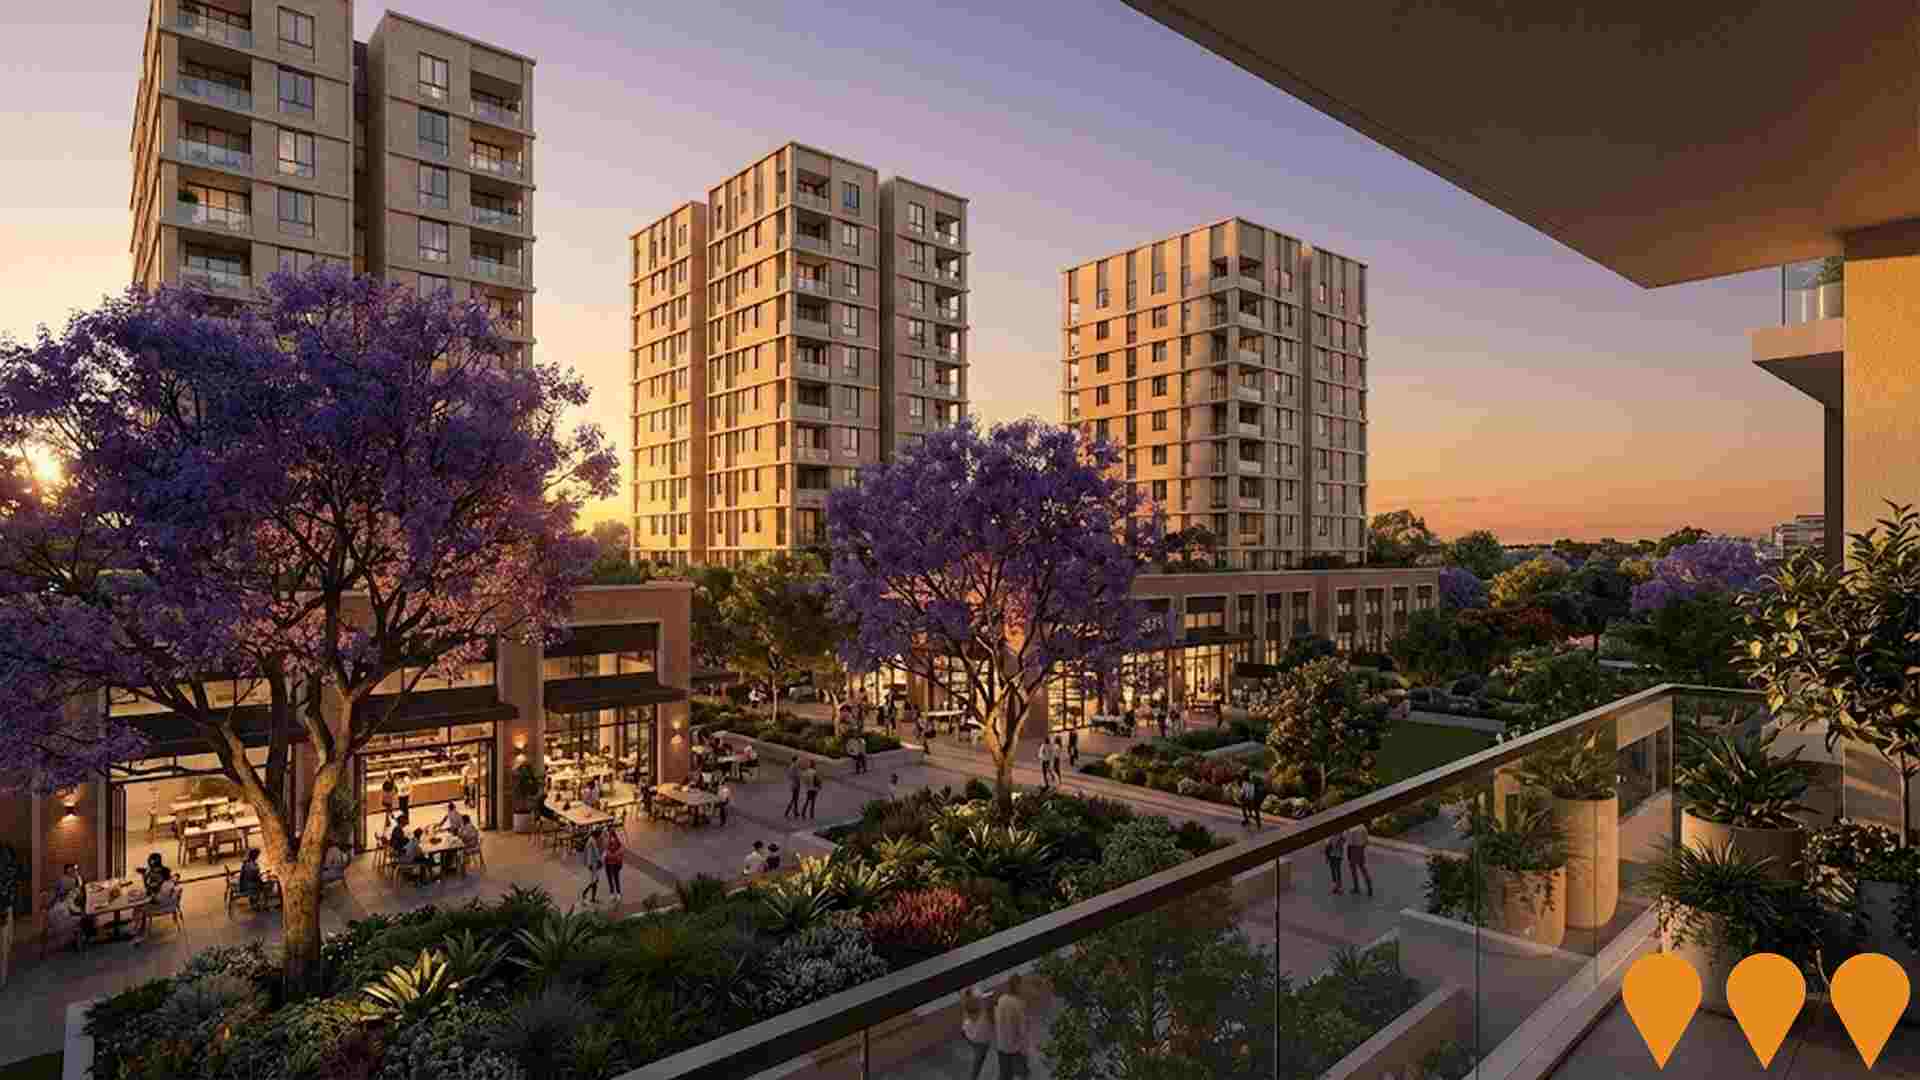
Macquarie Rise
Macquarie Rise is a luxury mixed-use development by TOGA, delivered in partnership with Baptist Union NSW and Morling College. The project features three residential towers ranging from 12 to 14 storeys, containing 268 apartments. These sit above a two-storey commercial podium providing 1,200 sqm of retail and office space. Residents have access to 'Club Rise' amenities including a 20m lap pool, gym, Pilates studio, and cinema room.
MCentral Macquarie Park
Multi-stage commercial development at 63-71 Waterloo Road comprising two office towers with ground-floor retail, a new public road and basement parking. Designed by A+ Design Group, the development integrates expansive public open spaces and contemporary architecture. Approved by the Sydney North Planning Panel on 31 March 2022 (DA LDA2021/0184); construction commenced in December 2025 with a total project value of approximately $218 million.
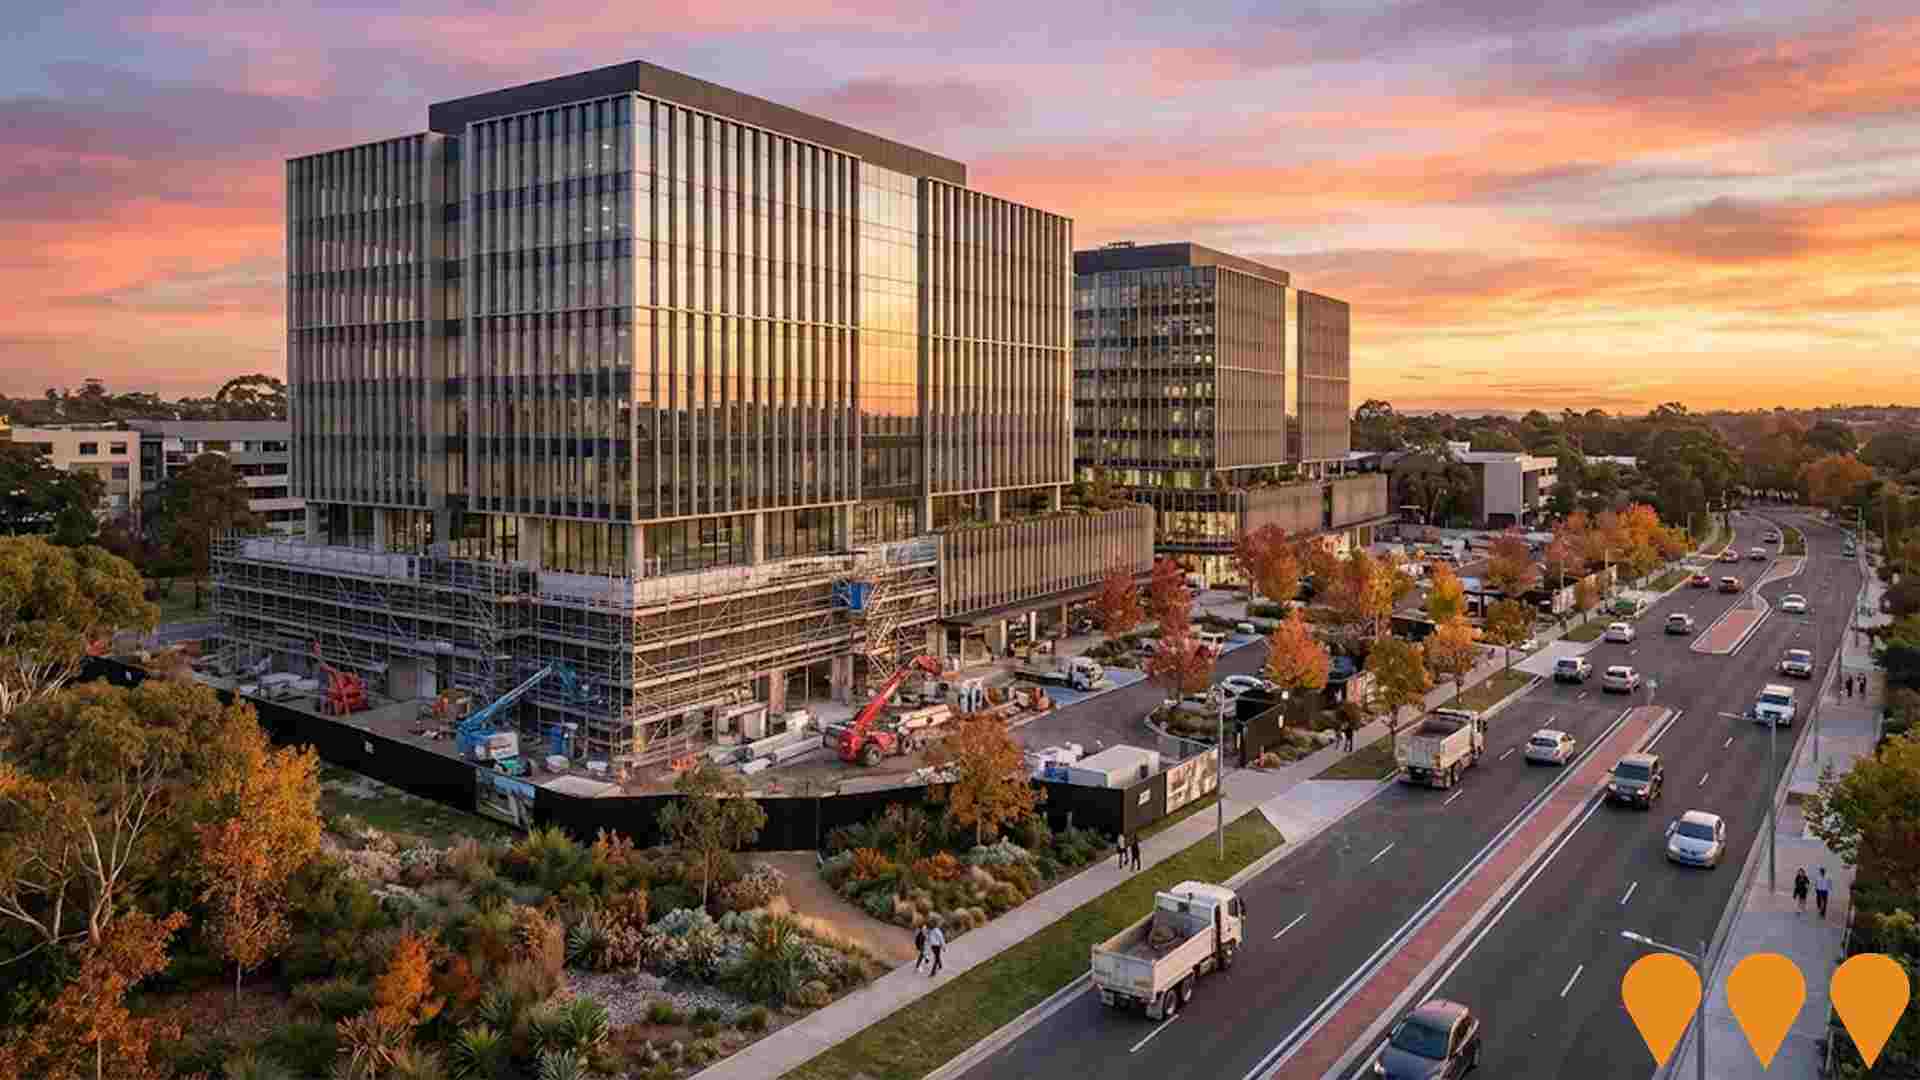
Midtown MacPark (Ivanhoe Estate Redevelopment)
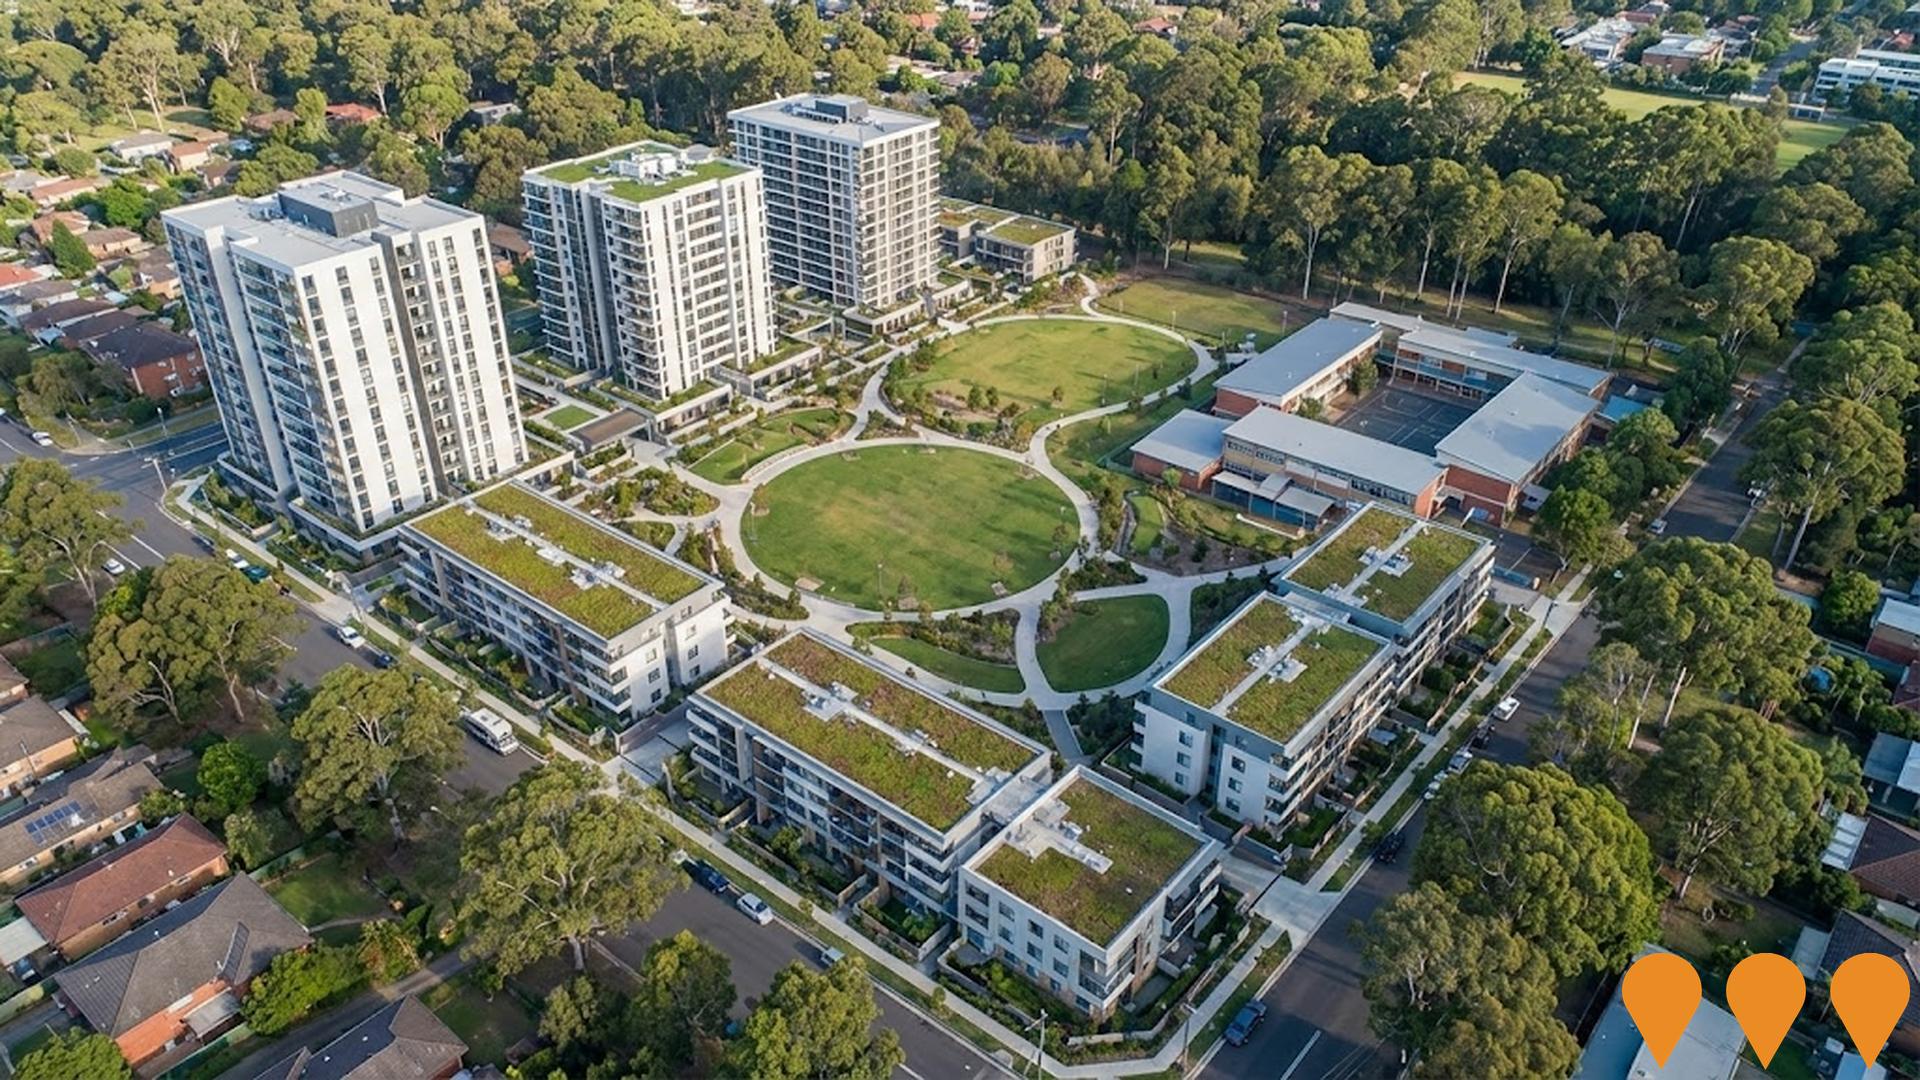
Midtown MacPark is the staged redevelopment of the former Ivanhoe Estate into an 8.2 hectare mixed-tenure urban renewal precinct in Macquarie Park. The project is led by Homes NSW with the Aspire consortium, including Frasers Property Australia and Mission Australia Housing. It will deliver around 3,300 homes, including 954 social housing units, 130 affordable rental units and more than 2,000 private homes, plus open space, parks, shops, cafes, restaurants, two childcare centres, a new primary school, a community centre, pool, gym and new road links.Stage 1 is complete and Stage 2 construction is underway, with later stages scheduled through to 2036.
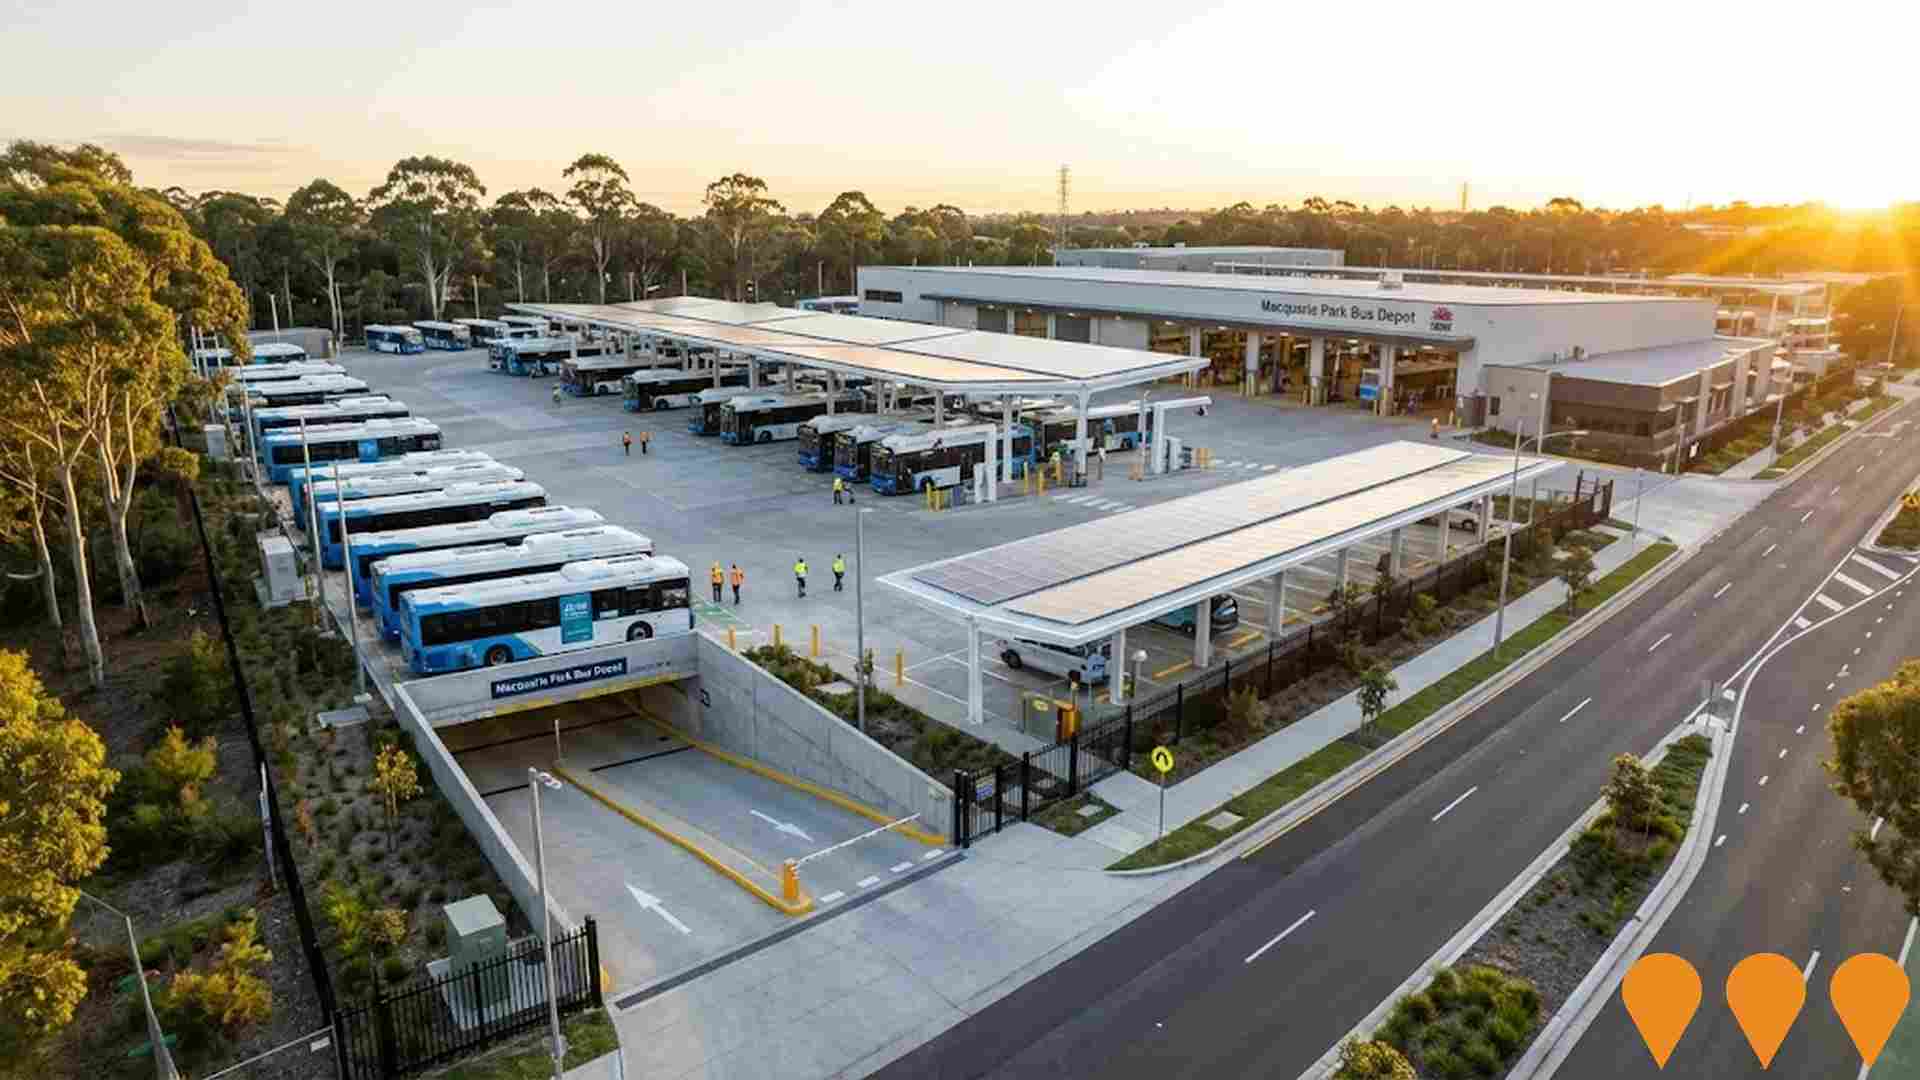
Macquarie Park Bus Depot
Sydney's first purpose-built battery electric bus depot, part of the NSW Government's Zero Emission Buses Program. The facility is designed to house 165 battery electric buses and includes comprehensive charging infrastructure, maintenance bays, a bus wash, and an underground car park for 150 staff. The project involves upgrading and widening Pittwater Road to facilitate depot access and is a key step in transitioning the state's bus fleet to zero emissions by 2047.
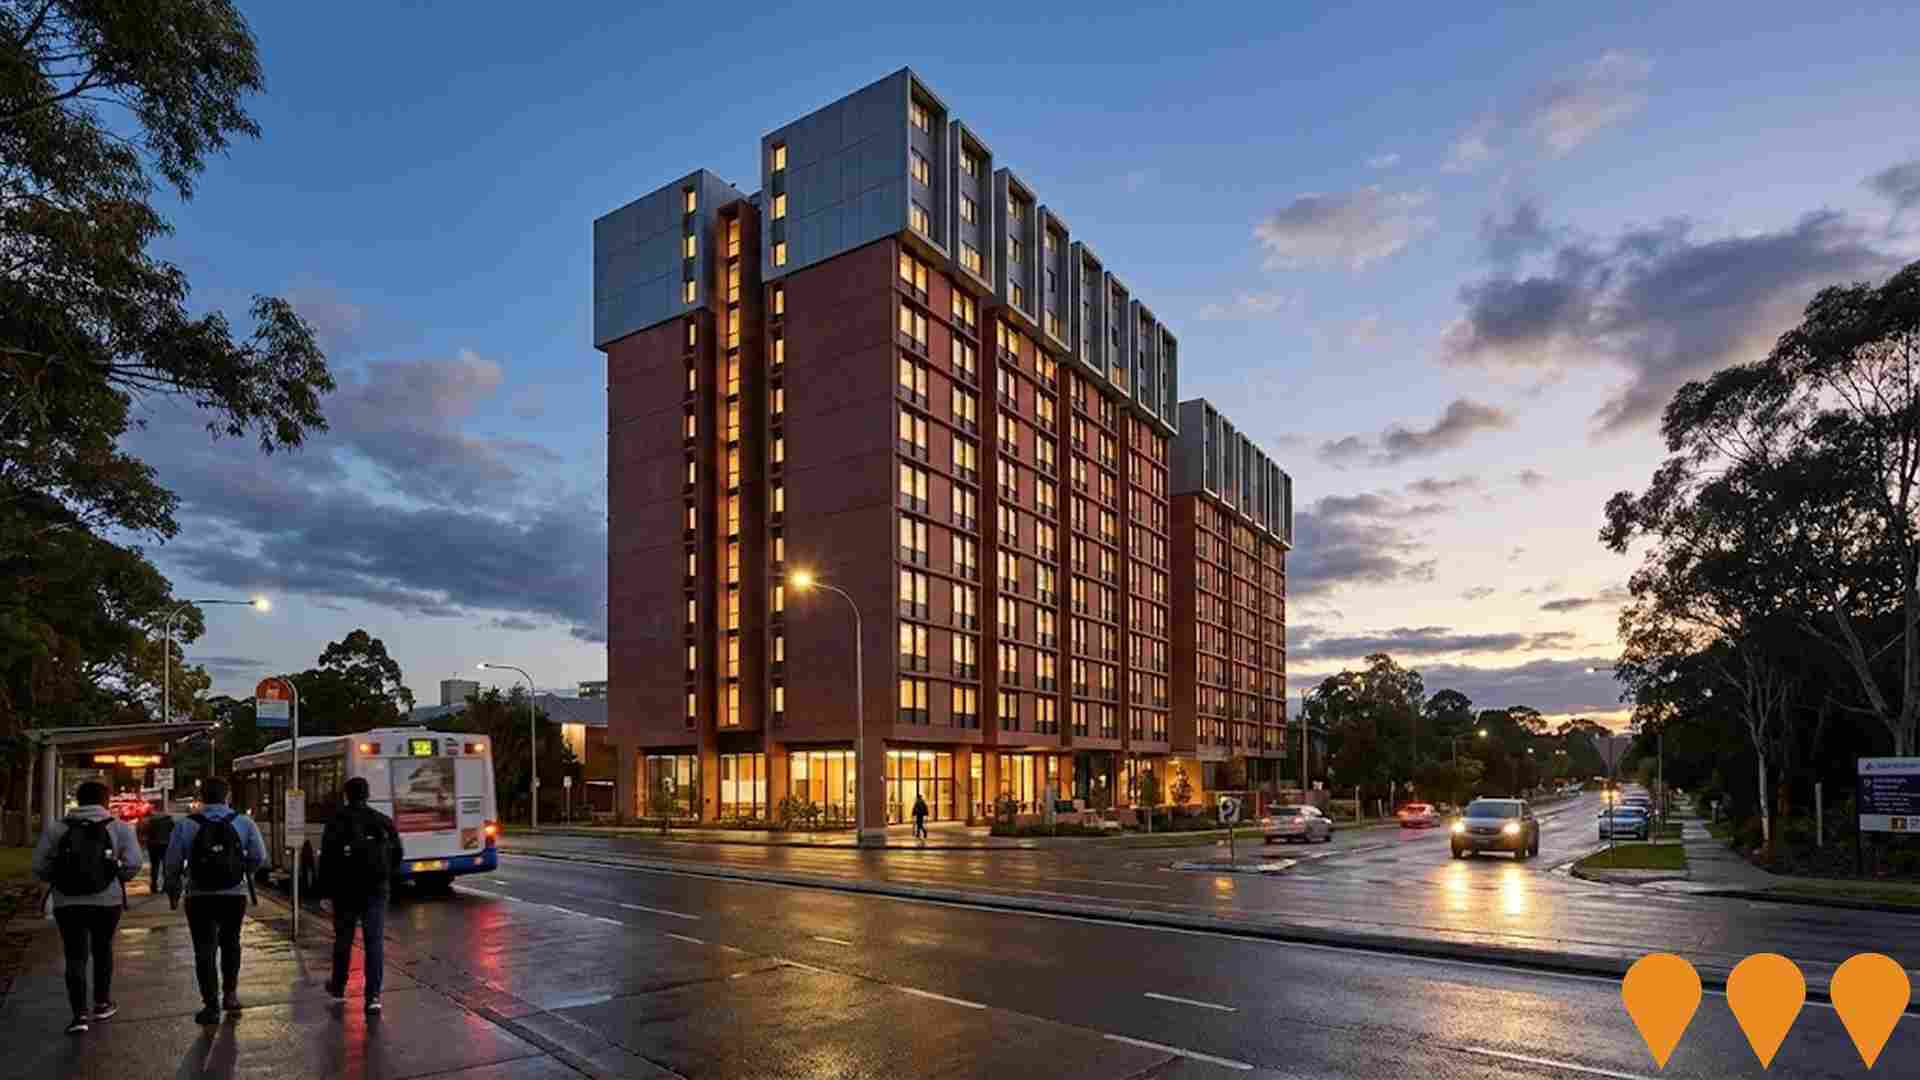
Herring Road, Macquarie Park
Australia's tallest Volumetric Modular Construction (VMC) project, this 20-storey Purpose Built Student Accommodation (PBSA) development features 528 studio units. Located 100 metres from Macquarie University metro station, the project includes extensive communal amenities such as a gym, media room, study spaces, and level 15 terrace. Designed by Cox Architecture, it targets a 5-Star Green Star rating and utilizes innovative modular steel technology for rapid delivery.
Triniti Lighthouse Build-to-Rent
State significant build-to-rent development comprising 510 rental apartments across three mixed-use buildings ranging from 9 to 20 storeys with ground floor retail and commercial space, communal resident amenities and basement parking. The project was approved by the NSW Independent Planning Commission on 10 July 2025. As of August 2026, no post-approval or construction documents have been published on the NSW Planning Portal and the project remains in the approved phase awaiting further implementation.


11,901 residents of Macquarie Park are employed, from a labour force of 12,483. Unemployment sits at 4.7%, with participation at 80.1%. Weighted for its industry mix, the area's sectors are forecast to grow about 7.2% nationally over five years. That reflects industry composition only and makes no allowance for local population growth, so in an area growing as fast as this one it understates the likely rise in local jobs. The working-day population is estimated at 40,436, about 2.3 times the resident population, so the area draws in more workers than it sends out. Unemployment and labour force come from ABS Small Area Labour Markets, updated quarterly; the industry and occupation profile is from the 2021 Census.
Detail
The local labour market is characterized by an exceptionally educated workforce with strong representation in the tech sector, recording an unemployment rate of 4.7% and annual employment growth of 5.1% based on AreaSearch statistical area aggregations. As of March 2026, employed residents total 11,901. While the jobless rate sits 0.5% above the Greater Sydney benchmark of 4.1%, the local participation rate is remarkably high at 80.1% versus 68.9% across Greater Sydney. Census records showed a notable 57.6% of residents working remotely, though pandemic-related lockdown measures at the time should be noted.
Resident employment is primarily anchored in professional & technical services, health care & social assistance, and retail trade. The professional & technical services segment is particularly dominant locally, with workforce representation standing at 1.6 times the broader metropolitan average. Conversely, construction represents a modest 3.8% of local employment, well below the 8.6% regional figure. Featuring 3.4 workers for each resident worker at the Census, the area acts as a major commercial employment destination, drawing in a substantial net influx of daily commuters. Over the past 12-month period, AreaSearch evaluation of SALM and ABS data shows local employment rising by 5.1% against a 5.8% expansion in the labour force, resulting in a 0.6 percentage points increase in unemployment. Over the same timeframe, Greater Sydney recorded a 1.9% increase in both employment and the labour force, alongside a slight reduction in unemployment. National Mar-26 projections from Jobs and Skills Australia point to nationwide job growth of 6.6% across five years and 13.7% across ten years. Applying these sector-specific trajectories to the local industry profile suggests employment could rise by 7.2% over five years and 14.5% over ten years, based on illustrative weighted modeling without adjusting for localized population shifts.
Frequently Asked Questions - Employment
Median household income in Macquarie Park is $1,886 a week (about $98,000 a year), with median personal income at $970 a week. ATO records put median taxable income at $57,671 a year against an average of $81,465. The average runs 41% above the median, a wider spread than most areas and a sign of a concentrated group of high earners. Household income is from the 2021 Census; taxable income is from ATO Taxation Statistics for the latest financial year available, indexed forward using the ABS Wage Price Index.
Detail
According to ATO postcode figures compiled by AreaSearch for financial year 2023, resident earnings place in the upper tiers nationally, featuring a median income of $57,671 and an average income of $81,465, compared to Greater Sydney metrics of $60,817 (median) and $83,003 (average). Factoring in the 10.32% Wage Price Index increase since financial year 2023, updated estimates reach roughly $63,623 (median) and $89,872 (average) as of March 2026. The 2021 Census placed personal weekly earnings at the 75th percentile ($970 weekly) and household earnings at the 58th percentile. In terms of earnings distribution, 37.2% of residents (6,453 people) sit in the $1,500 - 2,999 bracket, compared to 30.9% across the surrounding metropolitan region.
Housing costs exert significant pressure, leaving 77.2% of uncommitted income (49th percentile), while the area occupies the 7th decile on the SEIFA income index.
Frequently Asked Questions - Income
Macquarie Park had 4,786 occupied dwellings at the 2021 Census, 0% detached houses and 90% apartments. 22% are owned with a mortgage, 68% rented and 11% owned outright. At that Census the median rent was $460 a week and the median mortgage repayment $2,340 a month, a total housing cost higher than 95% of areas nationally. Rent absorbs 24.4% of household income here and mortgage repayments 28.6%. Dwelling stock, tenure and housing costs are 2021 Census measures — the only source that counts dwellings at this boundary size.
Detail
Census data indicates that the local dwelling profile consists of no detached houses whatsoever, with all residential properties (100.1%) categorized as medium-to-high density or other dwelling formats, contrasting sharply with the 55.9% standalone houses and 44.1% attached or multi-unit dwellings found across metropolitan Sydney. Outright home ownership stands at 10.5%, noticeably lower than broader Sydney levels, while 21.7% of homes are mortgaged and 67.8% are rented. Median monthly home loan repayments were $2,340 and median weekly rents stood at $460, compared with metropolitan benchmarks of $2,427 and $470 respectively. On a national scale, local monthly mortgage servicing is significantly above the $1,863 Australian norm, and weekly rents notably exceed the nationwide median of $375.
Frequently Asked Questions - Housing
Macquarie Park counted 4,786 households at the 2021 Census, an estimated 7,500 today, averaging 2.0 people each. 17% are couples with children, fewer than in 92% of areas nationally, against 31% couples without children. 35% of households are people living alone, and families average 0.6 children. Household and family composition is measured only by the Census, so these are 2021 figures.
Detail
Family households make up 56.9% of occupied residences, comprising couples without children (30.6%), couples with children (17.4%), and single parent households (6.2%). Non-family living arrangements account for the remaining 43.1%, led by single-person households at 35.4% and group households at 7.7%. The local median household size of 2.0 persons is smaller than the 2.7 average recorded across Greater Sydney.
Frequently Asked Questions - Households
64.6% of adults in Macquarie Park hold a university qualification, including 37.6% with a bachelor degree and 24.6% with postgraduate qualifications. A further 6.5% hold a vocational qualification. 4 schools serve the area, with 86 enrolment places and an average ICSEA of 999 against a national benchmark of 1,000. Qualifications come from the 2021 Census; school enrolments, ICSEA and results come from ACARA's current release.
Detail
The local population displays an advanced educational profile, with 64.6% of residents aged 15 and over holding tertiary qualifications, substantially exceeding the NSW (32.2%) and national (30.4%) benchmarks. This concentration underpins a strong capability in professional and knowledge-intensive industries. Bachelor degrees are held by 37.6% of residents, postgraduate credentials by 24.6%, and graduate diplomas by 2.4%. Vocational and technical training accounts for 14.6% of formal qualifications among those aged 15+, comprising advanced diplomas (8.1%) and certificates (6.5%). Formal study engagement is substantial across the community, with 35.0% of residents actively undertaking education.
By sector, 20.9% of residents are pursuing higher education courses, 4.7% are in primary school, and 2.3% are attending secondary school.
Frequently Asked Questions - Education
Schools Detail
Public transport in Macquarie Park reaches 99 stops on 43 routes, timetabled for about 15,000 services a week. The typical home sits about 120 m from its nearest stop. Buses carry the largest share of public transport commuters. Households keep an average of 0.3 vehicles. Stop and service counts are built from operators' published GTFS timetables and refresh with each timetable release; vehicle ownership is from the 2021 Census.
Detail
Public transport connectivity is supported by 99 operational transit stops across the suburb, encompassing bus and light rail services. These stops are served by 43 separate transit routes, generating 14,953 weekly scheduled passenger trips. Transit access is highly convenient, with residents situated an average of 124 meters from their closest stop. Outbound commuting is standard, with private vehicles accounting for 47% of work travel, trains handling 23%, and walking making up 14%. Vehicle ownership sits below regional standards at 0.3 vehicles per dwelling. Work-from-home participation was recorded at 57.6% during the 2021 Census, reflecting prevailing COVID-19 circumstances at the time.
Transit service frequency delivers an average of 2,136 trips daily across the local network, translating to roughly 151 departures each week per transit stop.
Frequently Asked Questions - Transport
Transport Stops Detail
82.9% of residents in Macquarie Park report no long-term health condition. 3.7% need daily assistance with core activities, and 59.1% hold private health cover. The standardised death rate runs at 5.1 per 1,000 residents. Health conditions, assistance needs and insurance are 2021 Census measures; the death rate comes from current ABS releases.
Detail
Health indicators across the community are strong, with AreaSearch evaluations of chronic illnesses and mortality highlighting low rates of common medical conditions overall and near-average rates among older, vulnerable cohorts. Private health insurance uptake is notably high, covering approximately 59% of residents (10,251 people). The most frequently reported long-term conditions in the area are mental health challenges (5.5%) and asthma (4.7%), while 82.9% of residents indicated no chronic health ailments, outperforming the Greater Sydney rate of 74.6%. Residents aged 65 and over make up 7.3% of the populace (1,266 people), well under the Greater Sydney proportion of 15.5%.
While senior health outcomes remain favorable compared to general benchmarks, they sit slightly lower on a national ranking scale than the broader local community.
Frequently Asked Questions - Health
68.9% of Macquarie Park residents were born overseas and 64.9% speak a language other than English at home, more culturally diverse than 97% of areas nationally. The largest reported ancestries are Chinese (26.4%) and English (10.8%). Ancestry, language and country of birth are counted only by the Census, so these are 2021 figures.
Detail
The local community showcases high cultural diversity, with 68.9% of residents born abroad and 64.9% speaking a language other than English in the home. Christianity represents the most common religious affiliation at 29.6%, while Hinduism shows a notable local concentration at 10.7%, more than double the Greater Sydney average of 5.2%. Looking at parental country of birth, the three most prominent ancestry groups are Chinese (26.4%, substantially above the 8.4% regional average), Other (19.6%), and English (10.8%, below the 19.0% regional rate). Other notable cultural representations include Indian at 8.9% (versus 3.6% regionally), Korean at 4.4% (versus 1.1% regionally), and Russian at 0.8% (versus 0.4% regionally).
Frequently Asked Questions - Diversity
The median resident of Macquarie Park is 30, younger than 93% of areas nationally. That is 1 year younger than at the 2021 Census. 55.5% of residents are aged 15 to 34. Age cohorts are not raw Census counts: the Census split is re-based to the latest ABS population estimates and state projections.
Detail
The age distribution leans heavily toward younger, pre-family cohorts. AreaSearch estimates for August 2026 show that 49.3% of the community comprises adults aged 25 - 44, compared to 31.4% across Greater Sydney, whereas mature adults and early retirees aged 45 - 64 account for 10.4% versus 22.6% regionally. The estimated median age as at August 2026 is 30, down from 31 at the 2021 Census, sitting 7 years younger than Greater Sydney's 2021 median of 37 and well below the nationwide median of 38 at that Census. The most noticeable demographic shift since the Census is the rise in youth and children aged 0 - 24, growing from 29.0% to an estimated 33.1%.
Long-term projections indicate adults aged 25 - 44 will generate the largest numerical gain by 2041, increasing by 6,783 persons (79%) to 15,336, while the 45 - 64 cohort will expand fastest proportionally, rising 104% to 3,677 residents.
Frequently Asked Questions - Age
Data & MethodBoundaries, Sources & Method for Macquarie Park
9 of 14 data sections on this page were updated within the last 12 months — the newest current to Sep 2026.
Everything is aggregated to the Suburb (SAL) boundary shown above, on a 2021 Census baseline. Only 3 sections — housing, households and cultural diversity — still wait on the 2026 Census.
The ledger — source, cycle and currency by section
| Section | Source & update cycle | Currency |
|---|---|---|
| Updated within the last 12 months 9 sections | ||
| Population | ABS, GNAF, Geoscience Australia Annual (ABS ERP) | Aug 2026 2 months ago headline measures · 2021 Census baseline |
| Re-based to the ABS Estimated Resident Population (June 2025 release) and updated with new dwellings from GNAF address data. Current to Aug 2026, with the 2021 Census supplying the small-area baseline. | ||
| Age profile | ABS, Geoscience Australia, State governments Annual | Aug 2026 2 months ago headline measures · 2021 Census baseline |
| Age cohorts are re-based to the latest ABS population estimates and state projections, current to Aug 2026. Each cohort is held as a Census baseline and a current estimate. | ||
| Development & approvals | ABS, GNAF Monthly (ABS approvals) | Aug 2026 2 months ago headline measures · Jul 2026 baseline |
| Property sales & rents | Valuer General, Rental Board, ABS Weekly sales, quarterly rents | Sep 2026 last month all 21 measures |
| Sales from the state Valuer General register, refreshed weekly, and rents from quarterly rental bond lodgements. Both are read live each time this page loads, current to Sep 2026. | ||
| Infrastructure projects | Infrastructure Australia, State agencies, Local governments Daily | Sep 2026 last month all 36 projects tracked here |
| Project pipeline maintained continuously from Infrastructure Australia, state agencies, local government and public announcements. Records are added and revised daily; this area was last updated Sep 2026. | ||
| Employment | ABS, DEWR, JSA Quarterly (ABS SALM) | Mar 2026 7 months ago headline measures · 2021 Census baseline |
| Unemployment and labour force from ABS Small Area Labour Markets, current to Mar 2026. The growth outlook applies Department of Employment (now Jobs and Skills Australia) forecasts for all 19 industry divisions to the local industry mix, so it measures sector composition rather than local expansion and makes no allowance for population growth. Job demand comes from the same agency via its Internet Vacancy Index; industry and occupation structure from the 2021 Census. | ||
| Education | ABS, ACARA Annual (ACARA) | Sep 2026 last month headline measures · 2021 Census baseline |
| Transport | ABS, State Transport Departments Each timetable release | Jul 2026 3 months ago headline measures · 2021 Census baseline |
| Services & amenities | Provider directories, ACECQA Continuous | Sep 2026 last month all 14 measures |
| Annual and financial-year sources 2 sections | ||
| Income | ABS, ATO Annual (ATO) | FY 2023 3 years ago headline measures · 2021 Census baseline |
| ATO taxable income statistics for FY 2023, indexed forward using the Wage Price Index. Census household income provides the distribution detail. | ||
| Health | ABS, ATO Annual | 2024 2 years ago headline measures · 2021 Census baseline |
| Census-measured — next update: 2026 Census 3 sections No more current small-area source exists for these, so they are labelled as Census-measured rather than implied to be current. | ||
| Housing | ABS 5-yearly (Census) | 2021 Census next update 2026 all 30 measures |
| Households | ABS 5-yearly (Census) | 2021 Census next update 2026 all 18 measures |
| Cultural diversity | ABS, Geoscience Australia 5-yearly (Census) | 2021 Census next update 2026 all 44 measures |
"Currency" is the most recent release feeding that section. Where the Census supplies the structural baseline underneath a current headline figure, the row says so.
How the numbers are built
Population
The Census provides the small-area baseline, aggregated from mesh blocks to this boundary. It is then re-based to the ABS Estimated Resident Population (June 2025 release), and new dwellings built since Census night are counted from address data — 2,168 validated new addresses here. The headline figure is therefore a current estimate for Aug 2026, not a 2021 count (11,071 at the 2021 Census → 17,349 now). Annual growth rates are compound (CAGR), not simple averages.
Age profile
Cohort shares are not raw Census counts. Every cohort is held as a pair — the Census baseline and a current estimate — and the split is re-based using ERP and state population projections, current to Aug 2026. Median age is the Census median plus modelled change since. Charts that show both are labelled "2021 Census vs Current Estimate".
Property sales
Sourced from the state valuation authority's sales register — current, not Census, and refreshed weekly. Medians are calculated from settled transactions in the period shown; periods with very low transaction counts are flagged or suppressed, because a handful of sales can move a median substantially.
Rents
Derived from state rental bond lodgement data, by dwelling type and bedroom count. Bonds are lodged at the start of a new tenancy, so this reflects new lettings, not the whole rented stock.
Development & infrastructure
Building approvals come from current ABS releases; development applications are collected from council and state planning portals; the infrastructure pipeline is compiled from Infrastructure Australia and local government sources. Applications are matched to this boundary by address or coordinates, so very recent lodgements may not yet appear.
Employment & income
Industry and occupation structure comes from the Census, but the headline labour-market indicators do not. Unemployment and labour force are derived from ABS Small Area Labour Markets (quarterly). The employment outlook applies Department of Employment forecasts for all 19 industry divisions to this area's own industry mix (the agency is now Jobs and Skills Australia), as does the Internet Vacancy Index used for job demand. Because it is weighted on industry composition alone, that outlook carries no allowance for local population growth — in fast-growing areas the real rise in local jobs will typically be higher. Income combines Census household income with ATO taxable-income statistics for FY 2023, indexed forward using the Wage Price Index.
Education, transport & amenities
School enrolments, ICSEA and performance come from ACARA's current release, not the Census. Public transport stops and service frequency are derived from GTFS timetable feeds published by state transport departments. Services and amenities are proximity and count scores built from provider directories, refreshed on their own cycle. The Census contributes only the travel-to-work and qualification measures.
Rankings and benchmarks. Where we rank this area, the comparison set is every area of the same boundary type — suburbs against suburbs, SA2s against SA2s. Benchmarks compare this area against its greater capital city region and the national figure for the same measure and period.
Limits worth knowing. Small areas carry larger error margins, and the ABS introduces small random adjustments to Census counts to protect confidentiality — so totals may not sum exactly. Estimates re-based from regional data describe the area's expected trajectory, not a direct count of it. Figures are indicative for research and are not financial, planning or valuation advice.
Cross-check us. The Census baseline for this boundary is at ABS 2021 Census QuickStats (SAL12446). QuickStats reports 2021 only — the figures on this page are more current wherever the ledger shows a later date.