Chart Color Schemes
This analysis uses Suburbs and Localities (SAL) boundaries, which can materially differ from Statistical Areas (SA2) even when sharing the same name.
SAL boundaries are defined by Australia Post and the Australian Bureau of Statistics to represent commonly-known suburb names used in postal addresses.
Statistical Areas (SA2) are designed for census data collection and may combine multiple suburbs or use different geographic boundaries. For comprehensive analysis, consider reviewing both boundary types if available.
est. as @ -- *
2021 Census | -- people


Curious about local property values? Filter the chart to assess the volume and appreciation (including resales) trends and regional comparisons, or scroll to the map below view this information at an individual property level.
Find a Recent Sale

Sales Detail
Gleneagle has an estimated 3,083 residents, up from 2,106 at the 2021 Census — a change of 977 people, or 46.4%. Growth has averaged 7.6% a year over five years, faster than 97% of areas nationally. 422 new addresses have been validated here since Census night. Interstate and internal migration accounts for 87.0% of that increase. Density is about 99 people per square kilometre. Population is estimated from ABS Estimated Resident Population releases and GNAF address data, re-based from the 2021 Census and updated annually.
Detail
As of Aug 2026, the suburb of Gleneagle is estimated to have approximately 3,083 residents, according to AreaSearch evaluations combining broader ABS population updates with 422 validated new addresses recorded since the Census. When measured against the 2021 Census tally of 2,106 people, this represents an expansion of 977 people (46.4%). This demographic trajectory is derived from an estimated resident count of 3,049 determined by AreaSearch after reviewing the ABS June 2025 ERP release. With a population density of 98 persons per square kilometer, the locality offers generous living space alongside capacity for future expansion.
Outpacing both state levels and the national average (9.5%), the 46.4% surge since the 2021 census positions the area as a regional growth leader, driven overwhelmingly by interstate migration which accounted for roughly 87.0% of recent population gains. Demographic projections for the suburb of Gleneagle utilize ABS/Geoscience Australia SA2 modeling published in 2024 using 2022 as a base year, while Queensland State Government SA2 figures released in 2023 (utilizing 2021 data) cover post-2032 horizons or gaps. Because the state forecasts omit age-specific breakdowns, AreaSearch incorporates cohort weighting aligned with the 2023 ABS Greater Capital Region release based on 2022 data. Overall, the locality is projected to experience population expansion slightly beneath the median across benchmarked statistical territories, adding 248 persons to 2041 across aggregated SA2 estimates, which translates to a total rise of 6.9% across the 16 years.
Frequently Asked Questions - Population
314 new dwellings have been approved in Gleneagle over the past five years, an average of 62 a year. That places the area in the 94th percentile for residential development activity nationally, about 20 approvals per 1,000 residents a year. Of the 60 dwellings approved in the latest reporting year, 92% were detached houses and the rest townhouses or apartments. Approvals are currently running at an annualised 77, broadly in line with that longer-run average. Figures come from ABS building approvals aggregated to this Suburb (SAL) boundary and are updated monthly as the ABS releases them.
Detail
Residential building approval patterns compiled by AreaSearch from ABS statistical area figures show that Gleneagle averages approximately 62 approved dwellings annually. Across the preceding 5 financial years (between FY-21 and FY-25), an estimated 314 homes received approval, alongside 77 approvals recorded during FY-25 to date. An average yearly influx of 3.2 new residents per built dwelling across the past 5 financial years (between FY-21 and FY-25) indicates that housing demand outstrips newly approved stock, a condition that typically fuels buyer competition and upward pricing pressure. New residential construction generates an average expected construction cost of $397,000, aligning with regional standards, while commercial development approvals totaling $7.1 million this financial year underscore the predominantly residential focus of the market.
Per-capita residential construction in Gleneagle outpaces Greater Brisbane by 52.0%, presenting prospective purchasers with abundant options while demonstrating strong developer commitment well ahead of nationwide norms. Detached houses comprise 92.0% of upcoming development compared to 8.0% for attached dwellings, sustaining a low-density urban footprint tailored to buyers seeking spacious living environments. With approximately 26 people per approval, the locality displays the hallmarks of an active development corridor. Projections based on the most recent AreaSearch quarterly estimate indicate that Gleneagle will add 214 residents through to 2041. Ongoing construction momentum suggests residential supply will readily accommodate projected demand, maintaining advantageous market conditions for purchasers and creating capacity for expansion beyond anticipated population levels.
Frequently Asked Questions - Development
Development applications around Gleneagle
Loading development applications…
| Lodged | Address | Description | Type | Distance | Status |
|---|
SOURCE: Planning portals and council registers, compiled by AreaSearch. Distance & bearing measured from the suburb midpoint.
AreaSearch tracks one current infrastructure or development project inside Gleneagle, worth an estimated $80 million. A further 55 sit in the immediately surrounding suburbs, taking the tracked pipeline within reach of the area to $157.5 billion. 24 are already under construction and 18 are due for completion within three years. The pipeline spans communities, precincts & urban renewal, residential development and transport & logistics. Records are compiled from Infrastructure Australia, state agencies, council planning portals and public announcements, reviewed and updated daily, then ranked by proximity, construction stage, completion horizon and project scale.
Detail
Infrastructure investments, major developments, and regional planning initiatives are key drivers of local performance, with AreaSearch tracking 4 notable projects positioned to influence the surrounding district. These critical undertakings comprise Spring Creek Estate, Glenlogan Rise Estate, Tullamore Downs, and Beaumoor Estate.
Professional plan users can use the search below to filter and access additional projects.
INFRASTRUCTURE SEARCH
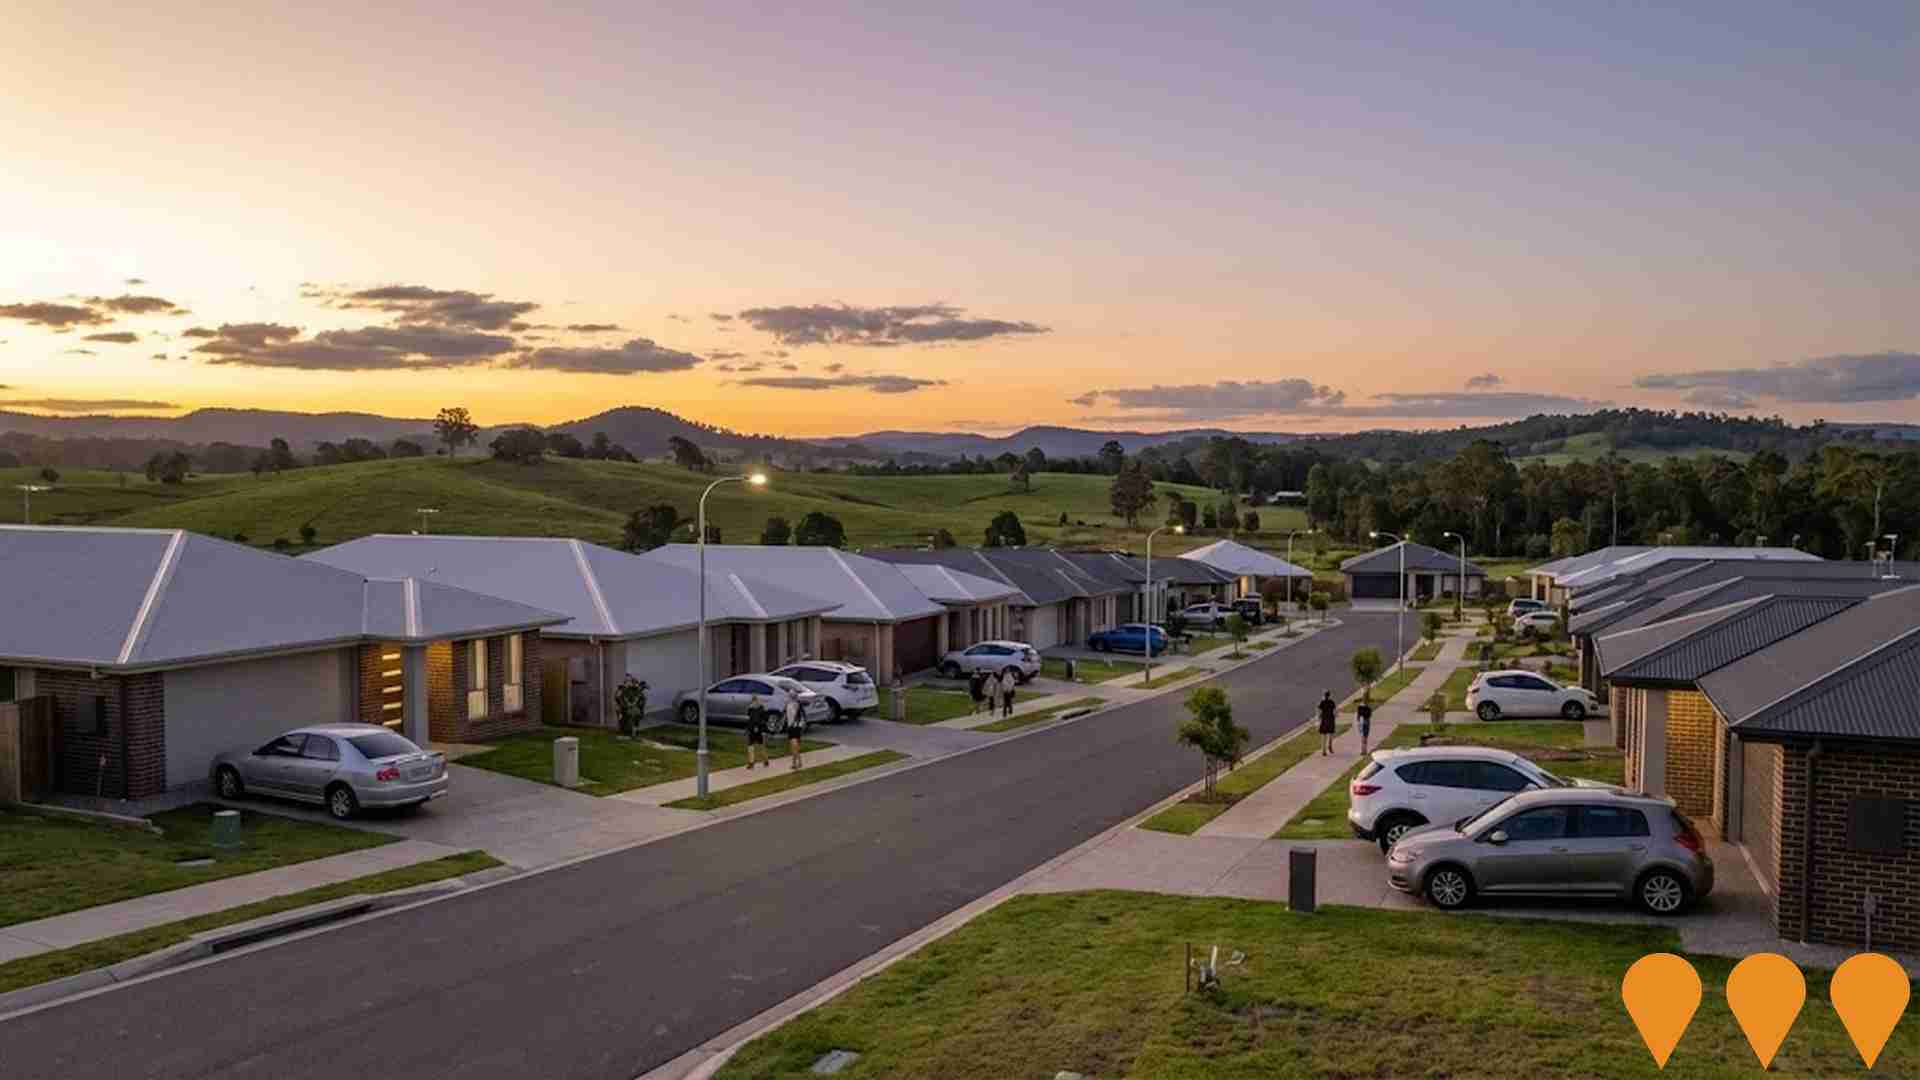
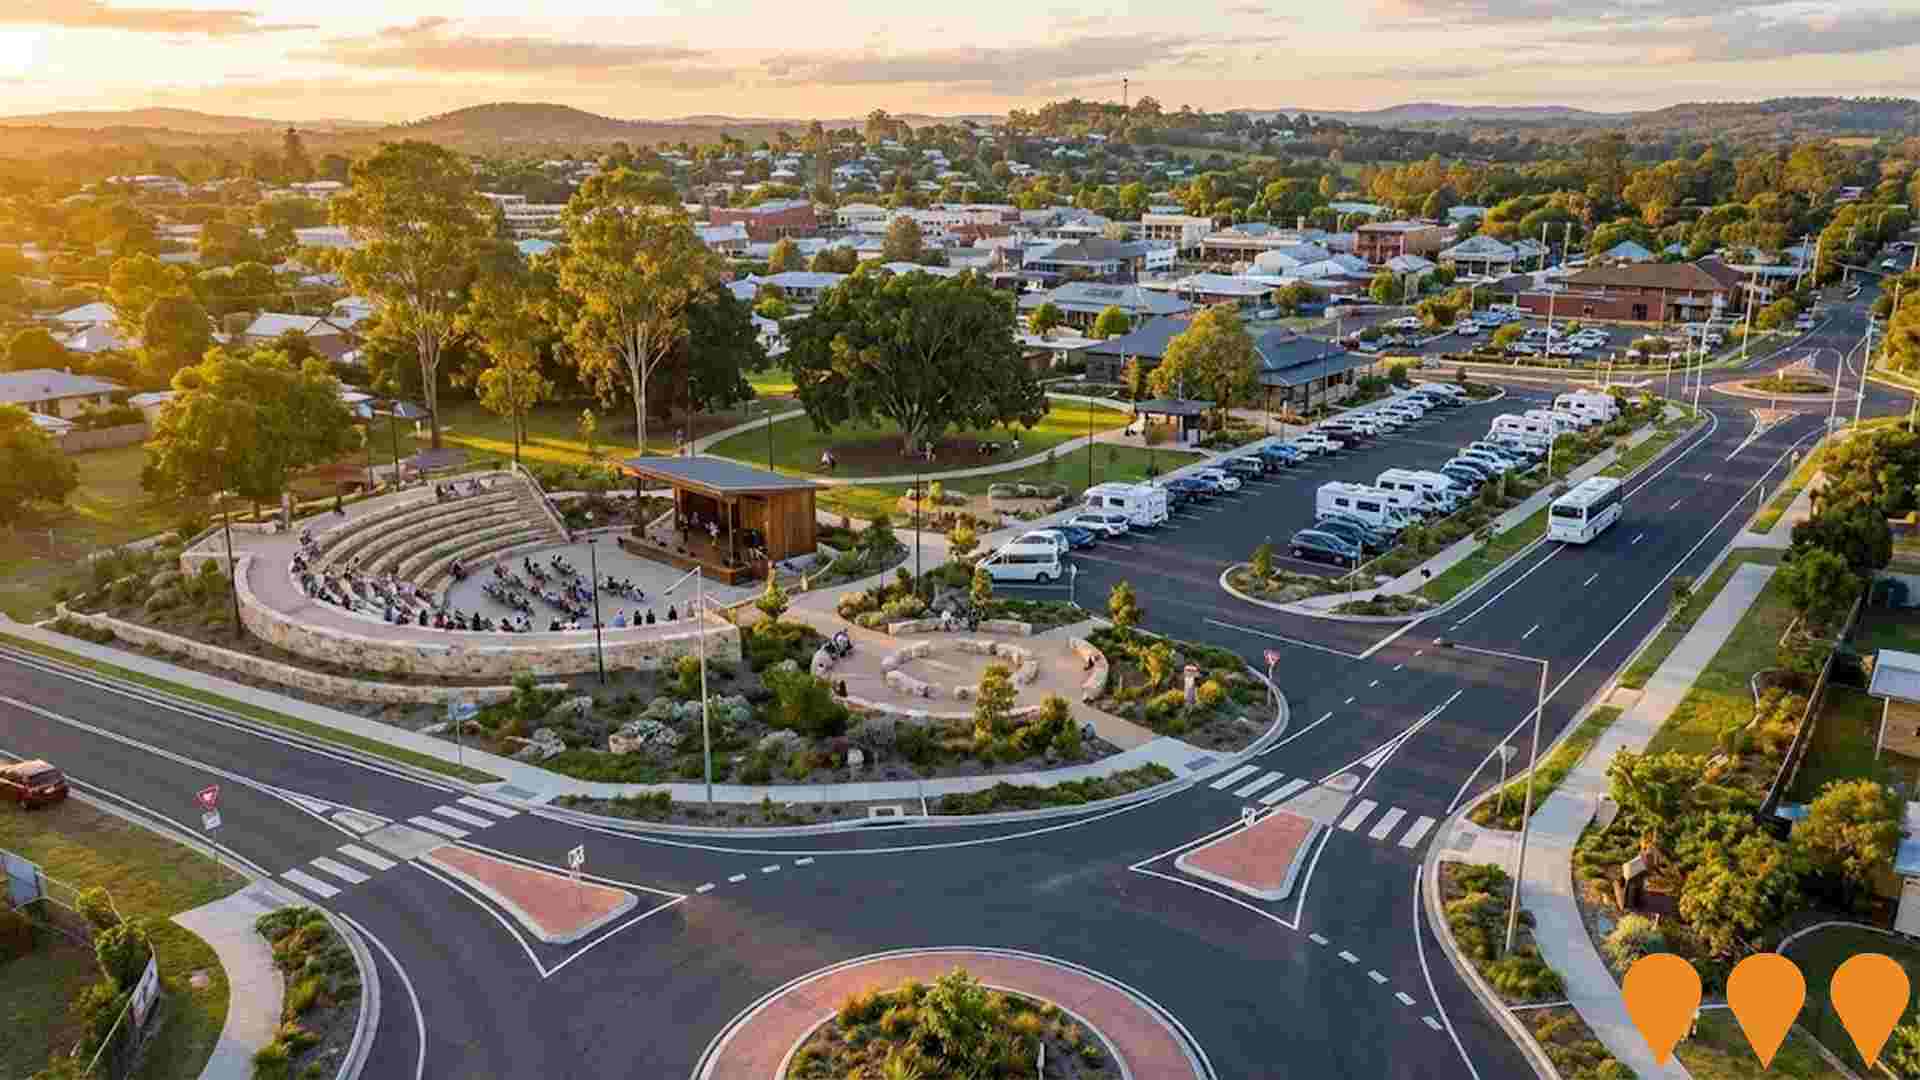
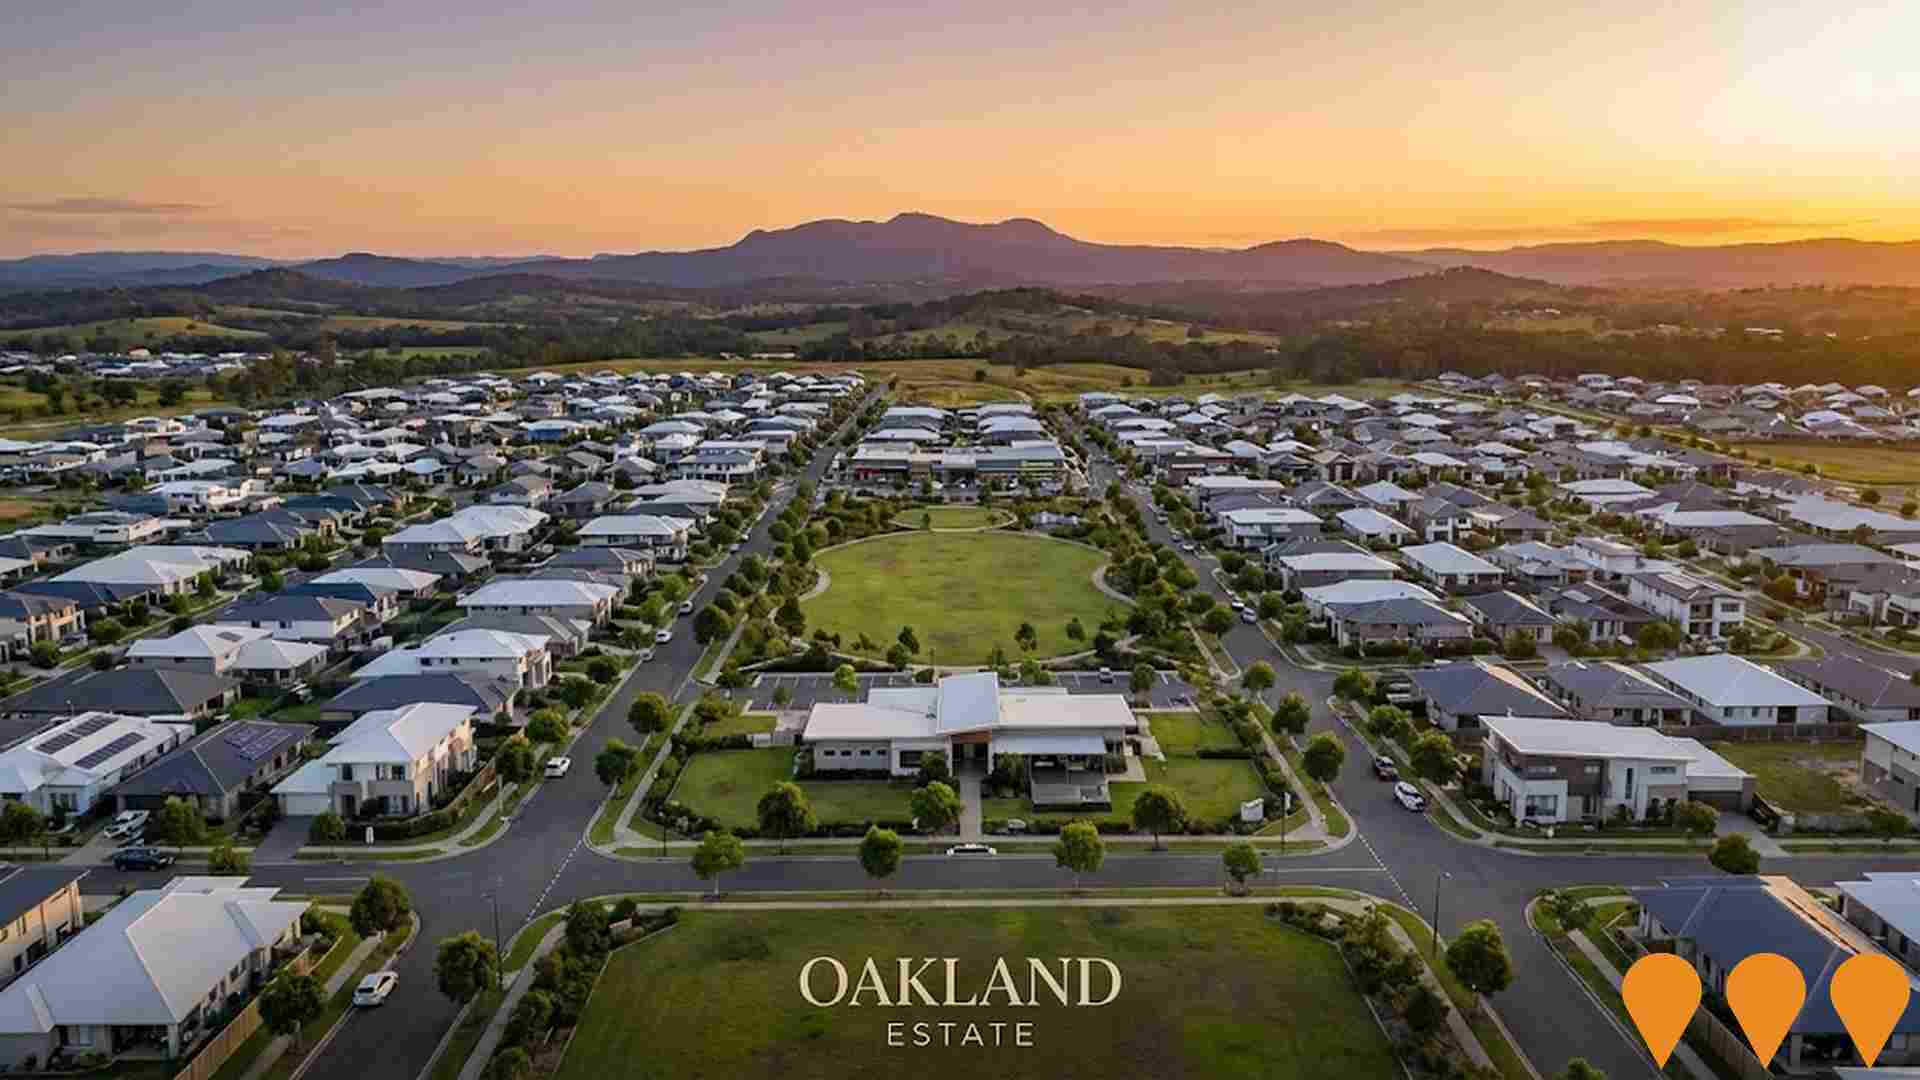
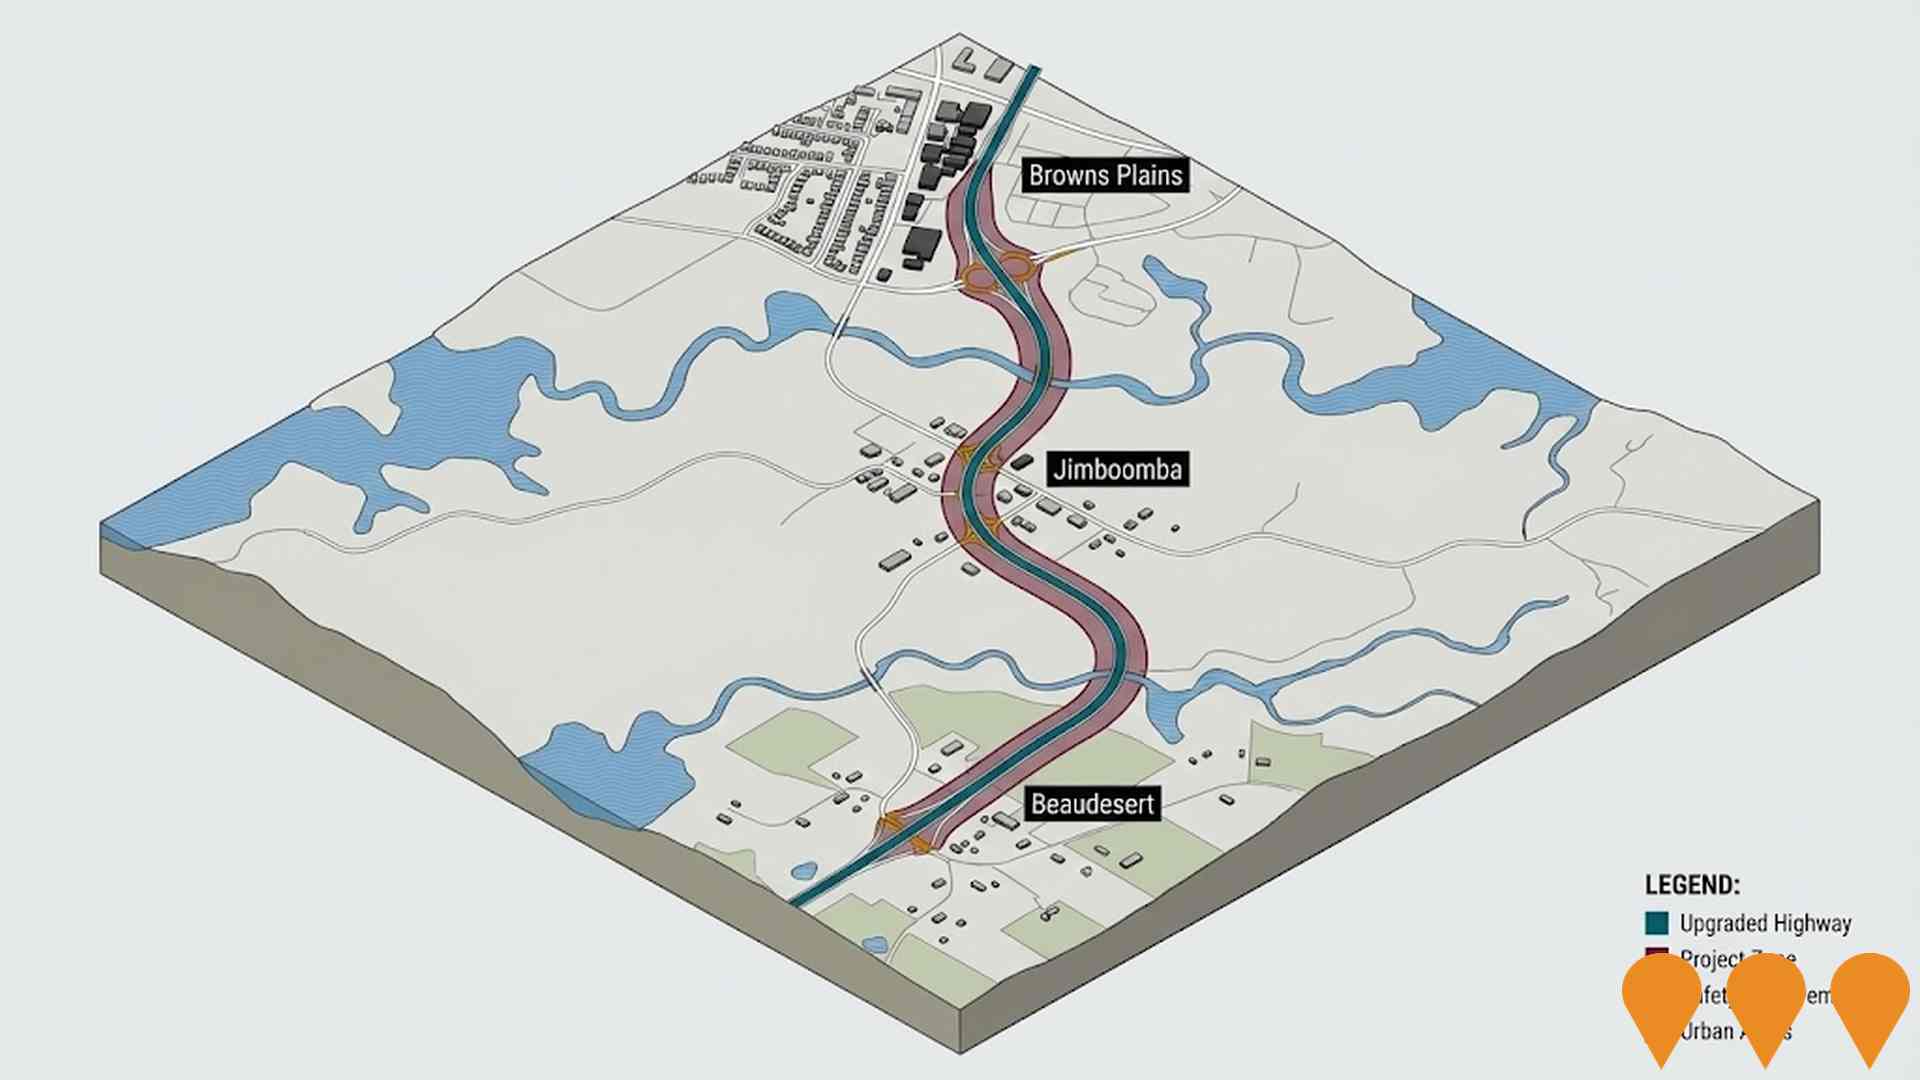
 Denotes AI-based impression for illustrative purposes only, not to be taken as definitive under any circumstances. Please follow links and conduct other investigations from the project's source for actual imagery. Developers and project owners wishing us to use original imagery please Contact Us and we will do so.
Frequently Asked Questions - Infrastructure
Tullamore Downs
Established residential development located 4km north of Beaudesert. Also known as Country Club Estate. Features duplex and single dwelling options. Part of town's recent growth expansion.
Beaudesert Town Centre Revitalisation
Multi-stage upgrade of Beaudesert's CBD delivering safer streets, major drainage upgrades, new roundabouts and crossings, expanded parking (including caravan and bus bays), and the Gateway Precinct at Davidson Park with an amphitheatre, events stage, yarning circles, public amenities and landscaped open space.
Oakland Estate
Oakland Estate is a 339 hectare masterplanned community on the eastern edge of Beaudesert in the Scenic Rim, planned to deliver around 2,000 homesites over 15 years and effectively double the size of the township. Stage 1 is sold out and Stage 2 lots are now selling, with a 2026 land release on the waitlist and Stage 3 in planning. The precinct is anchored by the Oakland Shopping Centre (now operating as Jones & Co IGA with specialty retail, a bottle shop and takeaway), McAuley Catholic College, an Ampol service centre with a Red Rooster outlet, and parks and pocket reserves.Within the estate, Ingenia Lifestyle operates Millers Glen, a land lease over 50s community (formerly known as Oakland Village). Club Millers, a wellness and sports precinct featuring a heated pool and spa, two lane bowling green and pickleball courts, opened in 2025, and Ingenia lodged a development application with Scenic Rim Regional Council in late 2024 to add a further 211 homes and additional community facilities. A 23.9 hectare balance parcel covering Stages 3 to 5 (concept plan for around 210 lots) was offered for sale by Colliers in 2024 to support continued delivery.
Beaudesert Enterprise Precinct
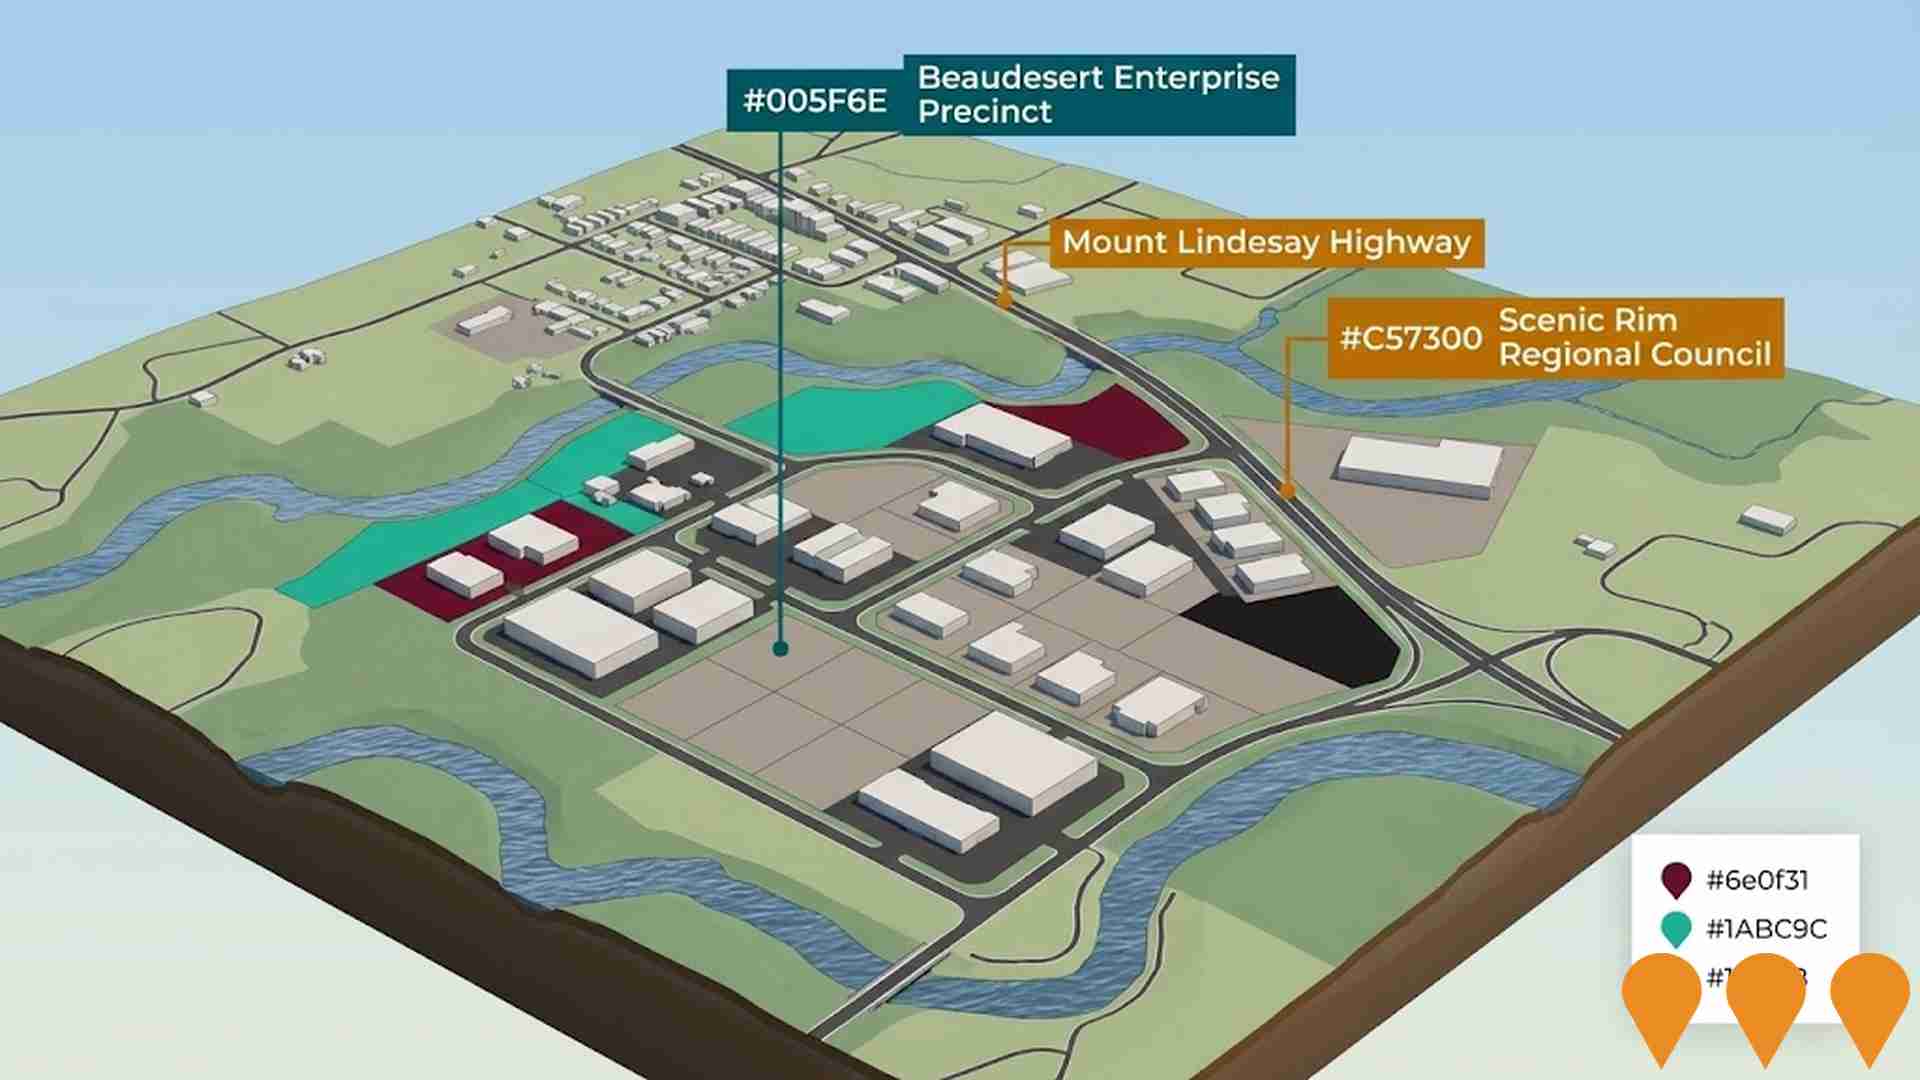
A 30-lot modern industrial business park on an 11-hectare site at Enterprise Drive, Beaudesert, delivered by Scenic Rim Regional Council with Building Our Regions grant funding. The precinct provides fully serviced small-to-medium industrial lots with power, water, sewer and telecommunications. The final (30th) lot was sold in February 2026, with multiple businesses now open and operating. The precinct supports local employment growth and strengthens the broader Scenic Rim economy.
Brayford Estate
Established residential development located 2km east of Beaudesert town centre. Well-laid-out residential area contributing to town's growth. Includes larger acreage-style properties with natural surroundings.
Jimboomba Woods Estate
A sold-out acreage community of large residential lots, set on 1,200 acres of former cattle grazing land, offering a blend of rural living with city comforts like NBN and town water in Jimboomba, South East Queensland. Features include established trees, walking trails, and community facilities. The project is completed and sold out.
Petbarn and Large Format Retail, Jimboomba
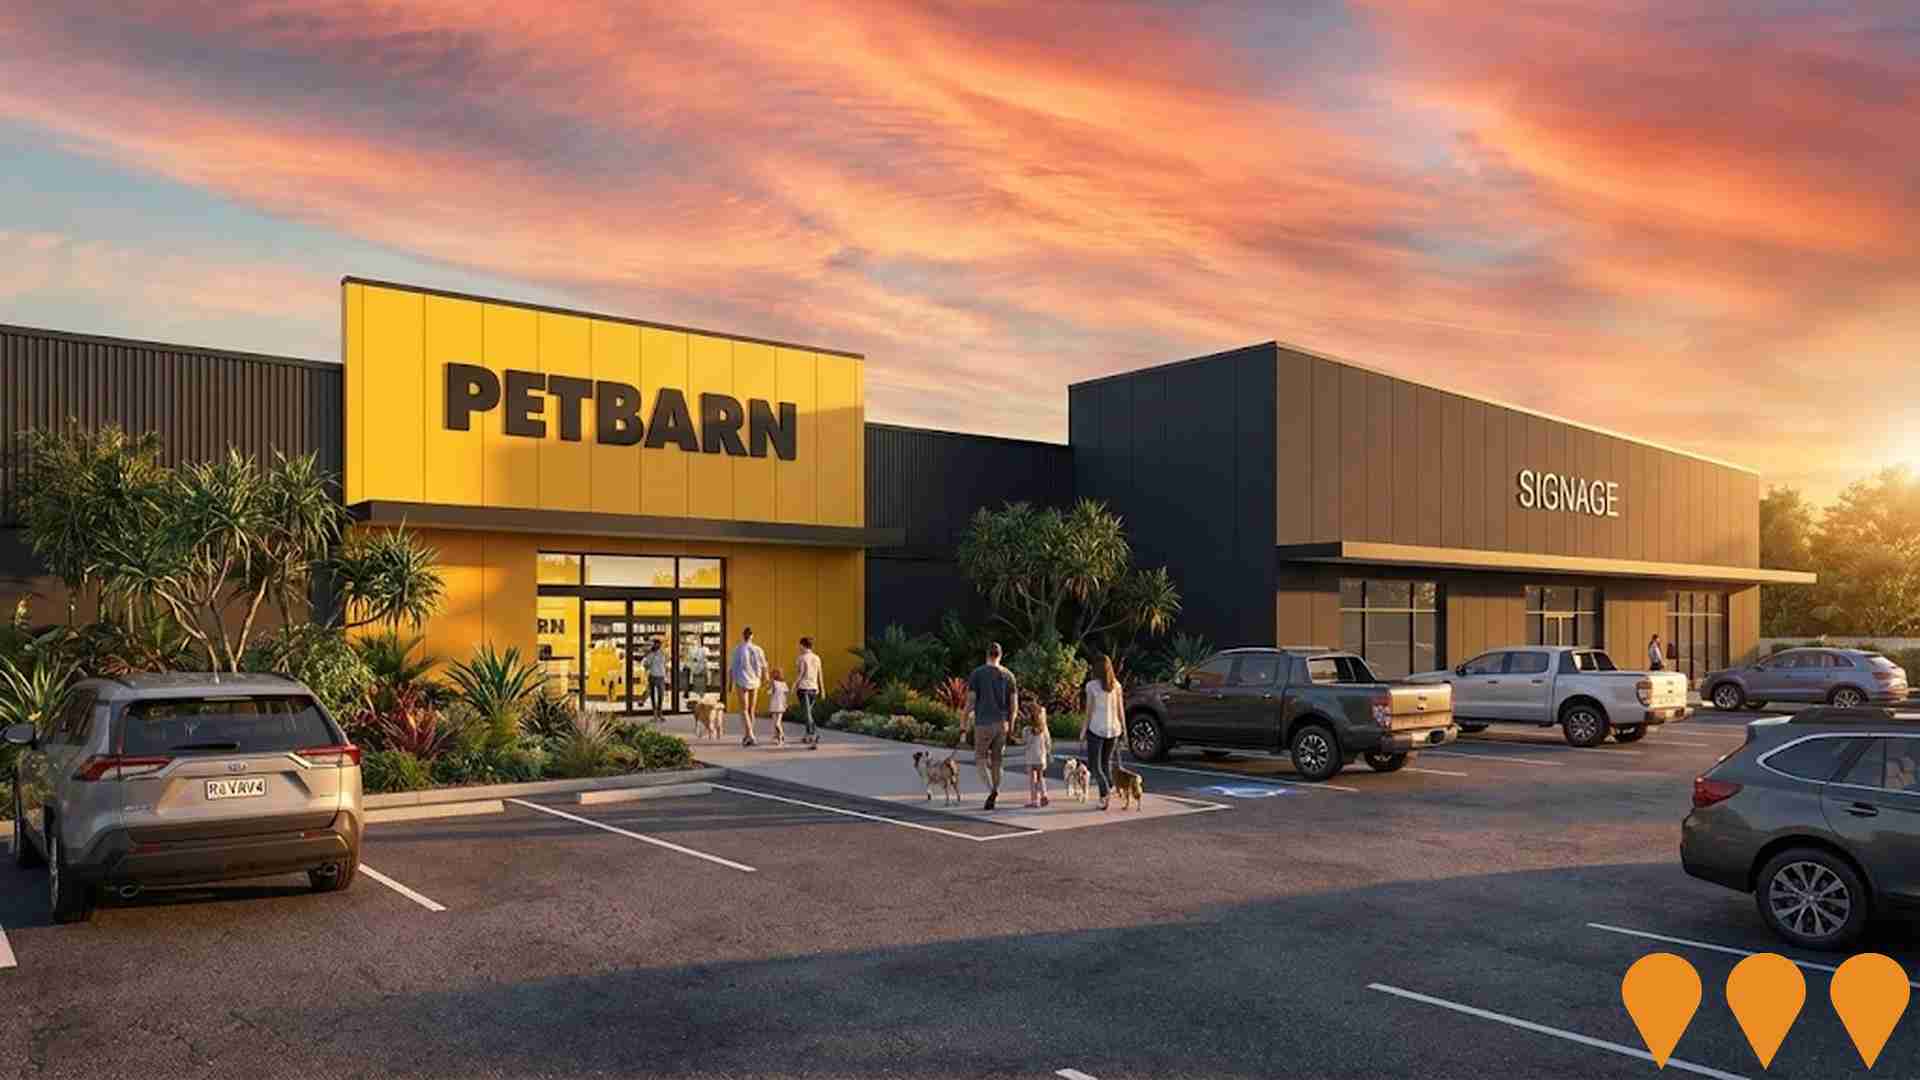
A single-story commercial development featuring two large-format retail tenancies: a 940sqm Petbarn and a second 900sqm showroom. The project includes 46 parking spaces, a shared loading bay, and extensive landscaping. It is designed with articulated facades to complement the adjacent Mitre 10 and provides a new through-road connection between Spring Street and Anders Street to improve local traffic flow.
Elridge Estate
A boutique 157-lot house and land community in Jimboomba, combining rural tranquility with city convenience. The estate is fully sold out and features parklands, walking trails, a dedicated nature corridor, and preserved open spaces to maintain its semi-rural character. A significant component includes 40 affordable homes delivered via the 'Everyone's Place' consortium, a partnership between KDL Property Group, Tetris Capital, and the Queensland Government's Housing Investment Fund.

1,341 residents of Gleneagle are employed, from a labour force of 1,477. Unemployment sits at 9.2%, with participation at 62.3%. Weighted for its industry mix, the area's sectors are forecast to grow about 6.0% nationally over five years. That reflects industry composition only and makes no allowance for local population growth, so in an area growing as fast as this one it understates the likely rise in local jobs. The working-day population is estimated at 2,459, about 80% of the resident population, so more people leave the area for work than travel in. Unemployment and labour force come from ABS Small Area Labour Markets, updated quarterly; the industry and occupation profile is from the 2021 Census.
Detail
Statistical area aggregations from AreaSearch indicate that Gleneagle maintains an employment profile balanced between blue and white collar roles, marked by high concentration in construction alongside an estimated annual jobs growth of 2.1% and an unemployment rate of 9.2%. By March 2026, employed residents reached 1,341, though the jobless rate sits 4.9% higher than the Greater Brisbane benchmark of 4.3%, and labor force participation of 62.3% trails the regional figure of 70.1%. Census records showed that only 11.5% of workers operated from home, a metric shaped by Covid-19 restrictions. Local workforce participation is centered predominantly within retail trade, construction, and health care & social assistance.
The construction sector displays an exceptional local footprint, employing 1.5 times the regional proportion, whereas professional & technical disciplines account for just 3.2% of local workers compared to 8.9% regionally. Comparisons between resident workers and Census workplace figures suggest that local job opportunities within the immediate area remain constrained. According to ABS and SALM statistical aggregations from AreaSearch, the 12 months to March 2026 saw local employment expand by 2.1% alongside a 2.7% increase in the labor force, which lifted the unemployment rate by 0.5 percentage points; in Greater Brisbane, employment rose by 3.2%, the labor force grew 3.4%, and joblessness increased by 0.1 percentage points. Looking ahead, Jobs and Skills Australia national projections from Mar-26 outline broader employment trajectories of 6.6% over five years and 13.7% over ten years. When adjusted for Gleneagle's unique industry concentration through simple weighting extrapolation (excluding local population projections), local employment is modeled to rise by 6.0% over five years and 12.7% over ten years.
Frequently Asked Questions - Employment
Median household income in Gleneagle is $1,490 a week (about $77,000 a year), with median personal income at $711 a week. ATO records put median taxable income at $57,474 a year against an average of $68,947. Household income is from the 2021 Census; taxable income is from ATO Taxation Statistics for the latest financial year available, indexed forward using the ABS Wage Price Index.
Detail
ATO postcode statistics for financial year 2023 aggregated by AreaSearch indicate that taxpayers in Gleneagle recorded a median income of $57,474 and an average of $68,947, sitting slightly above the national norm while comparing to $58,236 and $72,799 in Greater Brisbane. Factoring in Wage Price Index movement of 11.36% since financial year 2023 yields estimated values of $64,003 (median) and $76,779 (average) as of March 2026. Across personal, family, and household levels, Census earnings sit modestly within the 30th to 35th percentiles. The primary earnings cohort is the $1,500 - 2,999 band, capturing 33.5% of residents (1,032 people) versus 33.3% across the metropolitan area.
Severe housing affordability constraints leave residents with 82.1% of income remaining, placing the area at the 33rd percentile.
Frequently Asked Questions - Income
Gleneagle had 713 occupied dwellings at the 2021 Census, 90% detached houses and 0% apartments. 37% are owned with a mortgage, 36% rented and 27% owned outright. At that Census the median rent was $335 a week and the median mortgage repayment $1,733 a month. Rent absorbs 22.5% of household income here and mortgage repayments 26.8%. Dwelling stock, tenure and housing costs are 2021 Census measures — the only source that counts dwellings at this boundary size.
Detail
According to the latest Census, separate houses represent 89.5% of Gleneagle's residential landscape with 10.5% consisting of other dwellings such as apartments and semi-detached properties, contrasting with Brisbane metro where houses account for 73.5% and alternative dwellings 26.5%. Outright home ownership matches the metropolitan level at 27.4%, while mortgaged properties make up 37.1% and rented dwellings account for 35.5%. Typical monthly mortgage costs stand at $1,733, coming in lower than the Brisbane metro figure of $1,863 and the Australian average of $1,863. Median weekly rent is $335, sitting notably beneath Brisbane metro's $380 and the national benchmark of $375.
Frequently Asked Questions - Housing
Gleneagle counted 713 households at the 2021 Census, an estimated 1,044 today, averaging 2.8 people each. 32% are couples with children, against 29% couples without children. 18% of households are people living alone, and families average 1.9 children. Household and family composition is measured only by the Census, so these are 2021 figures.
Detail
Families constitute 79.4% of local households, encompassing couples with children at 32.0%, childless couples at 28.8%, and single parent families at 17.4%. Non-family living arrangements account for the remaining 20.6%, formed by single-person residences at 17.7% and group households at 3.4%. The typical household size is 2.8 people, exceeding the Greater Brisbane benchmark of 2.6.
Frequently Asked Questions - Households
9.6% of adults in Gleneagle hold a university qualification, including 7.0% with a bachelor degree and 1.7% with postgraduate qualifications, lower than 86% of areas nationally. A further 34.1% hold a vocational qualification. 1 school serves the area, with 216 enrolment places and an average ICSEA of 936 against a national benchmark of 1,000. Qualifications come from the 2021 Census; school enrolments, ICSEA and results come from ACARA's current release.
Detail
Higher education qualifications in the locality are comparatively low, with university completion sitting at 9.6% against 30.5% across Greater Brisbane, highlighting clear scope for targeted educational support. Among tertiary degree holders, bachelor degrees represent 7.0%, postgraduate credentials account for 1.7%, and graduate diplomas stand at 0.9%. Conversely, vocational and technical training is widely held, with 43.9% of residents aged 15+ possessing trade credentials, including certificates (34.1%) and advanced diplomas (9.8%). Academic participation is strong across the community, with 30.2% of the population enrolled in educational programs. This student cohort comprises 11.7% in primary schooling, 10.6% in secondary education, and 2.4% undertaking tertiary studies.
Frequently Asked Questions - Education
Schools Detail
Getting around Gleneagle means driving: households keep an average of 1.8 vehicles, and no scheduled public transport appears in the current timetable feeds. Service data is built from operators' published GTFS timetables; vehicle ownership is from the 2021 Census.
Frequently Asked Questions - Transport
Transport Stops Detail
63.2% of residents in Gleneagle report no long-term health condition, a less healthy profile than 84% of areas nationally. 7.4% need daily assistance with core activities, and 54.5% hold private health cover. The standardised death rate runs at 6.1 per 1,000 residents. Health conditions, assistance needs and insurance are 2021 Census measures; the death rate comes from current ABS releases.
Detail
AreaSearch evaluations of chronic condition incidence and mortality statistics point to meaningful health challenges in Gleneagle across younger and older demographics alike, alongside a relatively high private health insurance rate encompassing approximately 55% of the total population (~1,680 people). Mental health conditions and arthritis represent the most prevalent diagnosed ailments locally, impacting 11.1 and 9.7% of residents, while 63.2% of residents reported having no medical conditions compared to 69.2% across Greater Brisbane. Working-age residents experience heightened rates of chronic illness, and seniors aged 65 and over make up 17.7% of the population (545 people), higher than the 15.0% observed in Greater Brisbane, with senior health indicators showing challenges that track above nationwide averages.
Frequently Asked Questions - Health
Gleneagle is largely Australian-born, at 87.5% of residents, with 3.7% speaking a language other than English at home. The largest reported ancestries are English (32.1%) and Australian (30.1%). 4.0% of residents identify as Aboriginal and/or Torres Strait Islander. Ancestry, language and country of birth are counted only by the Census, so these are 2021 figures.
Detail
Cultural diversity metrics for Gleneagle sit beneath broader averages, with 87.5% of residents born in Australia, 90.5% holding citizenship, and 96.3% speaking exclusively English at home. Christianity forms the predominant religious affiliation at 48.8% of the local population, compared to 47.8% throughout Greater Brisbane. Parental heritage data shows English ancestry leading at 32.1% of the population (above the 26.8% regional mark), followed by Australian ancestry at 30.1% (compared to 23.2% regionally), and Irish at 8.2%. Other distinct representations include German ancestry at 6.2% against 4.2% regionally, New Zealand heritage at 0.9% compared to 1.0%, and Maori ancestry at 0.7% versus 1.1%.
Frequently Asked Questions - Diversity
The median resident of Gleneagle is 35, younger than 76% of areas nationally. 25.7% of residents are aged 15 to 34. Age cohorts are not raw Census counts: the Census split is re-based to the latest ABS population estimates and state projections.
Detail
Gleneagle maintains a relatively youthful age structure, with children and young adults (0 - 24) representing 35.6% of the population as at August 2026, compared to 31.8% across Greater Brisbane, while young to middle aged adults (25 - 44) account for 23.9% against a regional share of 30.6%. The median age is estimated at 35 as at August 2026, matching the 2021 Census level and sitting 1 year below the Greater Brisbane figure of 36 recorded at that Census. Since the Census, elderly and retiree cohorts (65+) expanded from 14.7% to an estimated 17.7% of residents, and by 2041 this 65+ demographic is anticipated to drive growth by adding 197 residents (36%) to reach 743, while cohorts of young to middle aged adults and children and young adults are forecast to decrease.
Frequently Asked Questions - Age
Data & MethodBoundaries, Sources & Method for Gleneagle
8 of 14 data sections on this page were updated within the last 12 months — the newest current to Aug 2026.
Everything is aggregated to the Suburb (SAL) boundary shown above, on a 2021 Census baseline. Only 3 sections — housing, households and cultural diversity — still wait on the 2026 Census.
The ledger — source, cycle and currency by section
| Section | Source & update cycle | Currency |
|---|---|---|
| Updated within the last 12 months 8 sections | ||
| Population | ABS, GNAF, Geoscience Australia Annual (ABS ERP) | Aug 2026 last month headline measures · 2021 Census baseline |
| Re-based to the ABS Estimated Resident Population (June 2025 release) and updated with new dwellings from GNAF address data. Current to Aug 2026, with the 2021 Census supplying the small-area baseline. | ||
| Age profile | ABS, Geoscience Australia, State governments Annual | Aug 2026 last month headline measures · 2021 Census baseline |
| Age cohorts are re-based to the latest ABS population estimates and state projections, current to Aug 2026. Each cohort is held as a Census baseline and a current estimate. | ||
| Development & approvals | ABS, GNAF Monthly (ABS approvals) | Aug 2026 last month headline measures · Jun 2026 baseline |
| Property sales & rents | Valuer General, Rental Board, ABS Weekly sales, quarterly rents | Aug 2026 last month all 21 measures |
| Sales from the state Valuer General register, refreshed weekly, and rents from quarterly rental bond lodgements. Both are read live each time this page loads, current to Aug 2026. | ||
| Employment | ABS, DEWR, JSA Quarterly (ABS SALM) | Mar 2026 6 months ago headline measures · 2021 Census baseline |
| Unemployment and labour force from ABS Small Area Labour Markets, current to Mar 2026. The growth outlook applies Department of Employment (now Jobs and Skills Australia) forecasts for all 19 industry divisions to the local industry mix, so it measures sector composition rather than local expansion and makes no allowance for population growth. Job demand comes from the same agency via its Internet Vacancy Index; industry and occupation structure from the 2021 Census. | ||
| Education | ABS, ACARA Annual (ACARA) | Aug 2026 last month headline measures · 2021 Census baseline |
| Transport | ABS, State Transport Departments Each timetable release | Jul 2026 2 months ago headline measures · 2021 Census baseline |
| Services & amenities | Provider directories, ACECQA Continuous | Jul 2026 2 months ago all 14 measures |
| Annual and financial-year sources 3 sections | ||
| Infrastructure projects | Infrastructure Australia, State agencies, Local governments Daily | Jul 2025 about a year ago all 1 projects tracked here |
| Project pipeline maintained continuously from Infrastructure Australia, state agencies, local government and public announcements. Records are added and revised daily; this area was last updated Jul 2025. | ||
| Income | ABS, ATO Annual (ATO) | FY 2023 3 years ago headline measures · 2021 Census baseline |
| ATO taxable income statistics for FY 2023, indexed forward using the Wage Price Index. Census household income provides the distribution detail. | ||
| Health | ABS, ATO Annual | 2024 2 years ago headline measures · 2021 Census baseline |
| Census-measured — next update: 2026 Census 3 sections No more current small-area source exists for these, so they are labelled as Census-measured rather than implied to be current. | ||
| Housing | ABS 5-yearly (Census) | 2021 Census next update 2026 all 30 measures |
| Households | ABS 5-yearly (Census) | 2021 Census next update 2026 all 18 measures |
| Cultural diversity | ABS, Geoscience Australia 5-yearly (Census) | 2021 Census next update 2026 all 44 measures |
"Currency" is the most recent release feeding that section. Where the Census supplies the structural baseline underneath a current headline figure, the row says so.
How the numbers are built
Population
The Census provides the small-area baseline, aggregated from mesh blocks to this boundary. It is then re-based to the ABS Estimated Resident Population (June 2025 release), and new dwellings built since Census night are counted from address data — 422 validated new addresses here. The headline figure is therefore a current estimate for Aug 2026, not a 2021 count (2,106 at the 2021 Census → 3,083 now). Annual growth rates are compound (CAGR), not simple averages.
Age profile
Cohort shares are not raw Census counts. Every cohort is held as a pair — the Census baseline and a current estimate — and the split is re-based using ERP and state population projections, current to Aug 2026. Median age is the Census median plus modelled change since. Charts that show both are labelled "2021 Census vs Current Estimate".
Property sales
Sourced from the state valuation authority's sales register — current, not Census, and refreshed weekly. Medians are calculated from settled transactions in the period shown; periods with very low transaction counts are flagged or suppressed, because a handful of sales can move a median substantially.
Rents
Derived from state rental bond lodgement data, by dwelling type and bedroom count. Bonds are lodged at the start of a new tenancy, so this reflects new lettings, not the whole rented stock.
Development & infrastructure
Building approvals come from current ABS releases; development applications are collected from council and state planning portals; the infrastructure pipeline is compiled from Infrastructure Australia and local government sources. Applications are matched to this boundary by address or coordinates, so very recent lodgements may not yet appear.
Employment & income
Industry and occupation structure comes from the Census, but the headline labour-market indicators do not. Unemployment and labour force are derived from ABS Small Area Labour Markets (quarterly). The employment outlook applies Department of Employment forecasts for all 19 industry divisions to this area's own industry mix (the agency is now Jobs and Skills Australia), as does the Internet Vacancy Index used for job demand. Because it is weighted on industry composition alone, that outlook carries no allowance for local population growth — in fast-growing areas the real rise in local jobs will typically be higher. Income combines Census household income with ATO taxable-income statistics for FY 2023, indexed forward using the Wage Price Index.
Education, transport & amenities
School enrolments, ICSEA and performance come from ACARA's current release, not the Census. Public transport stops and service frequency are derived from GTFS timetable feeds published by state transport departments. Services and amenities are proximity and count scores built from provider directories, refreshed on their own cycle. The Census contributes only the travel-to-work and qualification measures.
Rankings and benchmarks. Where we rank this area, the comparison set is every area of the same boundary type — suburbs against suburbs, SA2s against SA2s. Benchmarks compare this area against its greater capital city region and the national figure for the same measure and period.
Limits worth knowing. Small areas carry larger error margins, and the ABS introduces small random adjustments to Census counts to protect confidentiality — so totals may not sum exactly. Estimates re-based from regional data describe the area's expected trajectory, not a direct count of it. Figures are indicative for research and are not financial, planning or valuation advice.
Cross-check us. The Census baseline for this boundary is at ABS 2021 Census QuickStats (SAL31158). QuickStats reports 2021 only — the figures on this page are more current wherever the ledger shows a later date.