Chart Color Schemes
This analysis uses Suburbs and Localities (SAL) boundaries, which can materially differ from Statistical Areas (SA2) even when sharing the same name.
SAL boundaries are defined by Australia Post and the Australian Bureau of Statistics to represent commonly-known suburb names used in postal addresses.
Statistical Areas (SA2) are designed for census data collection and may combine multiple suburbs or use different geographic boundaries. For comprehensive analysis, consider reviewing both boundary types if available.
est. as @ -- *
2021 Census | -- people


Curious about local property values? Filter the chart to assess the volume and appreciation (including resales) trends and regional comparisons, or scroll to the map below view this information at an individual property level.
Find a Recent Sale

Sales Detail
Brighton East has an estimated 17,758 residents, up from 16,757 at the 2021 Census — a change of 1,001 people, or 6.0%. Growth has averaged 0.5% a year over five years. Overseas migration accounts for 100.0% of that increase. That puts 3,132 residents on each square kilometre. Population is estimated from ABS Estimated Resident Population releases and GNAF address data, re-based from the 2021 Census and updated annually.
Detail
Drawing on ABS demographic revisions across the wider district alongside newly validated addresses recorded by AreaSearch following the Census, the resident count in the suburb of Brighton East is approximated at 17,758 as of Aug 2026. This marks an expansion of 1,001 people (6.0%) above the 16,757 people documented during the 2021 Census. Such movement stems from an estimated resident pool of 17,703 determined by AreaSearch after assessing the June 2025 ABS ERP release, supplemented by 86 validated new addresses logged post-Census. With 3,131 persons per square kilometer, the local density places the suburb of Brighton East within the highest national quartile analyzed by AreaSearch.
Furthermore, the 6.0% expansion since the Census trails the broader SA4 region (8.2%) by only 2.2 percentage points, highlighting solid underlying demographic momentum. Net overseas arrivals served as the primary contributor, accounting for virtually all recent local population additions. Projections generated by ABS/Geoscience Australia in 2024 using 2022 baseline figures have been integrated by AreaSearch across SA2 boundaries. Wherever SA2 coverage is absent, figures from the 2023 VIC State Government Regional/LGA dataset are utilized through a population-weighted aggregation technique transitioning LGA metrics down to SA2 zones. These cohort-specific expansion trajectories are likewise applied to all locations for the period covering 2032 to 2041. Looking ahead, the suburb of Brighton East is anticipated to track above the national median for statistical regions, adding 2,750 persons by 2041 under consolidated SA2 projections, which represents a cumulative 16-year increase of 15.2%.
Frequently Asked Questions - Population
754 new dwellings have been approved in Brighton East over the past five years, an average of 150 a year. That places the area in the 75th percentile for residential development activity nationally, about 8 approvals per 1,000 residents a year. Of the 151 dwellings approved in the latest reporting year, 21% were detached houses and the rest townhouses or apartments. Approvals are currently running at an annualised 94, well below that longer-run average. Figures come from ABS building approvals aggregated to this Suburb (SAL) boundary and are updated monthly as the ABS releases them.
Detail
According to ABS residential building consent metrics compiled by AreaSearch, residential building approvals across the area have averaged around 150 each year, tallying an estimated 754 approved dwellings over the 5 financial years spanning FY-21 and FY-25, with 94 recorded in FY-25 to date. An average inflow of just 0.6 new residents annually per approved home throughout the 5 financial years between FY-21 and FY-25 points to supply comfortably matching or outpacing demand, expanding opportunities for purchasers and creating capacity for demographic gains exceeding baseline forecasts. At an average construction cost of $960,000 per dwelling, new residential projects clearly target the premium, high-end market.
Meanwhile, commercial construction activity remains modest, with $6.2 million in commercial approvals registered during the current financial year. The residential development pipeline is heavily weighted toward medium and high-density formats (79.0%), whereas detached houses represent 21.0%. This transition toward higher-density dwelling options provides more accessible pricing structures tailored to first-home buyers, investors, and downsizers. It contrasts sharply with the established residential base of 68.0% houses, reflecting tighter land constraints alongside shifting lifestyle habits and affordability considerations. Additionally, registering around 97 people per dwelling approval indicates typical low-density structural attributes. Demographic projections indicate the local community is on track to add 2,695 residents by 2041 relative to the latest quarterly calculations from AreaSearch. Sustaining the current pace of home building will ensure incoming demand is smoothly accommodated, supporting favorable purchasing conditions while enabling population growth beyond projected numbers.
Frequently Asked Questions - Development
Development applications around Brighton East
SOURCE: Planning portals and council registers, compiled by AreaSearch. Distance & bearing measured from the suburb midpoint.
AreaSearch tracks 11 current infrastructure and development projects inside Brighton East, worth an estimated $309 million. A further 113 sit in the immediately surrounding suburbs, taking the tracked pipeline within reach of the area to $9.29 billion. 32 are already under construction and 42 are due for completion within three years. The pipeline spans residential development, communities and communities, precincts & urban renewal. Records are compiled from Infrastructure Australia, state agencies, council planning portals and public announcements, reviewed and updated daily, then ranked by proximity, construction stage, completion horizon and project scale.
Detail
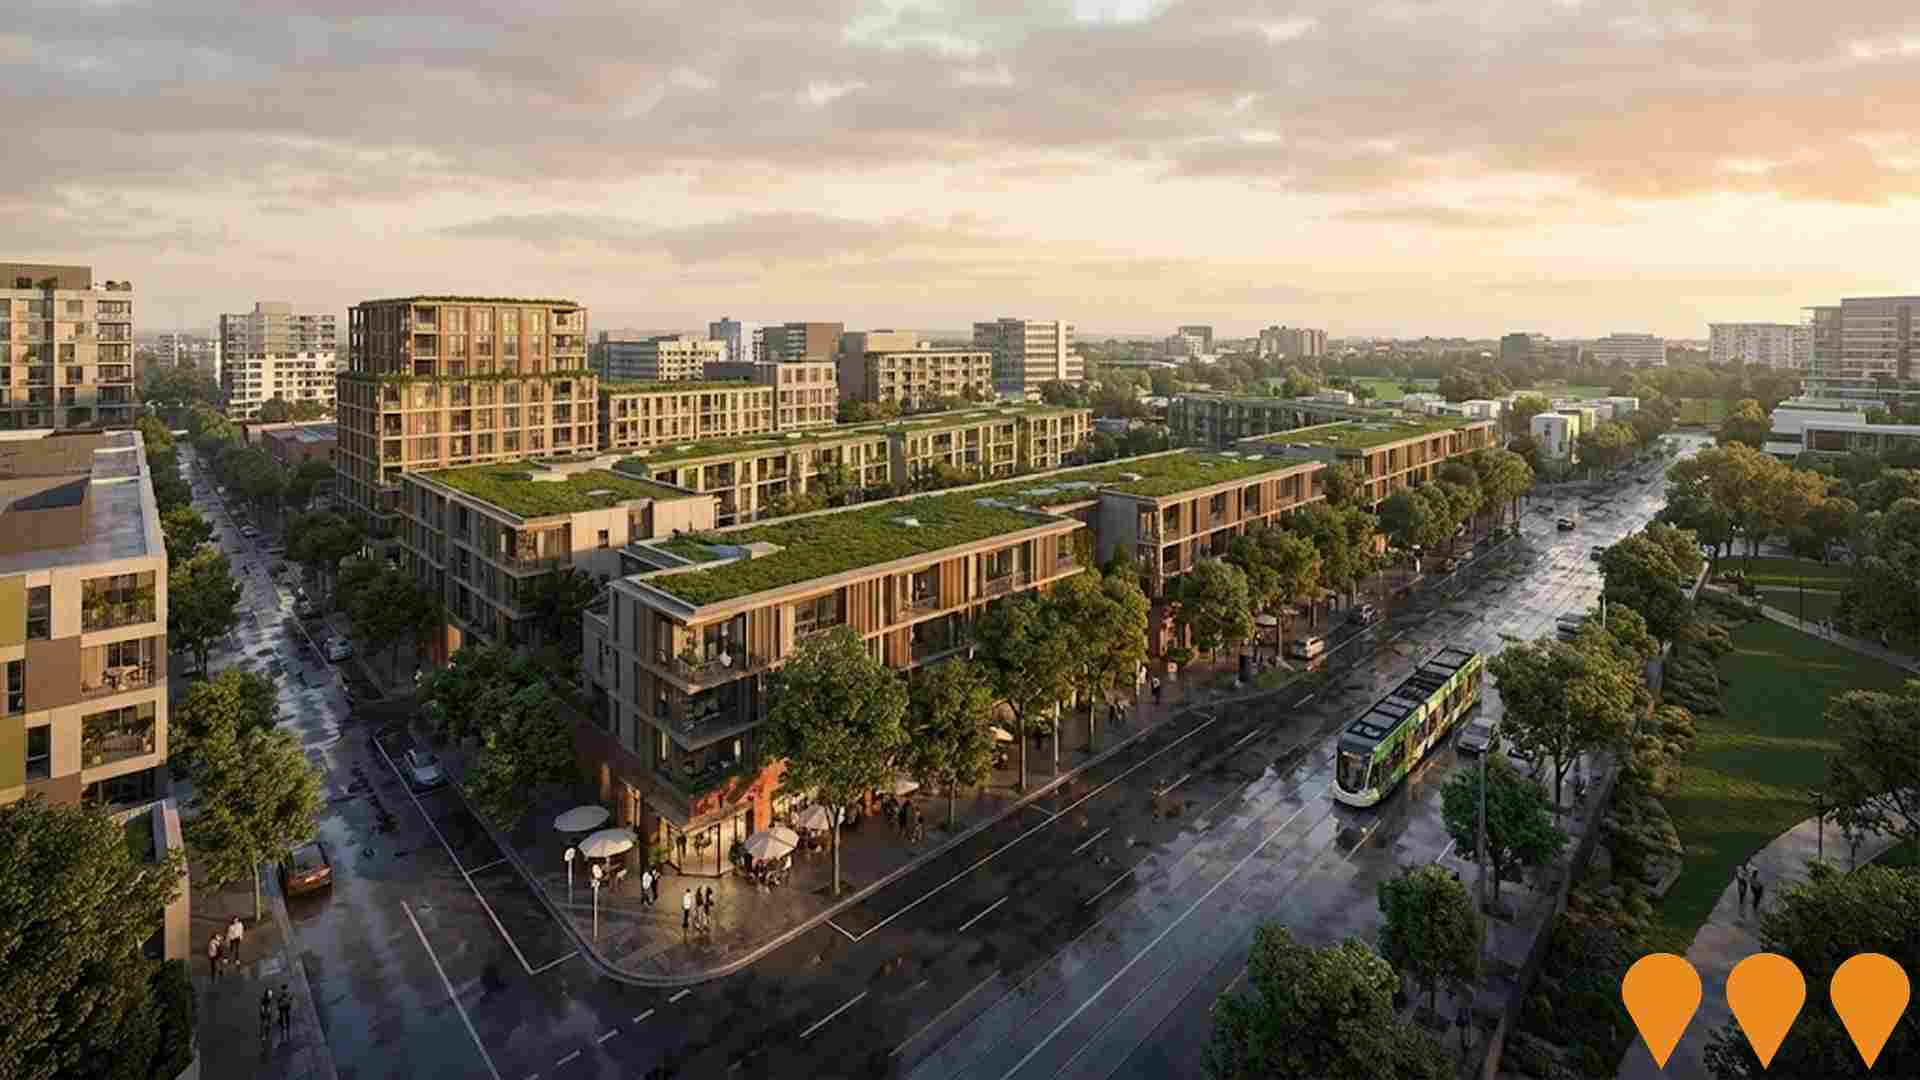
Community development and regional outcomes are closely shaped by capital infrastructure works, major projects, and town planning initiatives. A total of 42 significant initiatives have been tracked by AreaSearch as having a probable influence on the local catchment, including Ormond Station Development (Ormond Place), Bayside Gallery Building Works, Milli Brighton East, and Bluff Road Hampton East Housing Development, with key projects summarized below.
Professional plan users can use the search below to filter and access additional projects.
INFRASTRUCTURE SEARCH
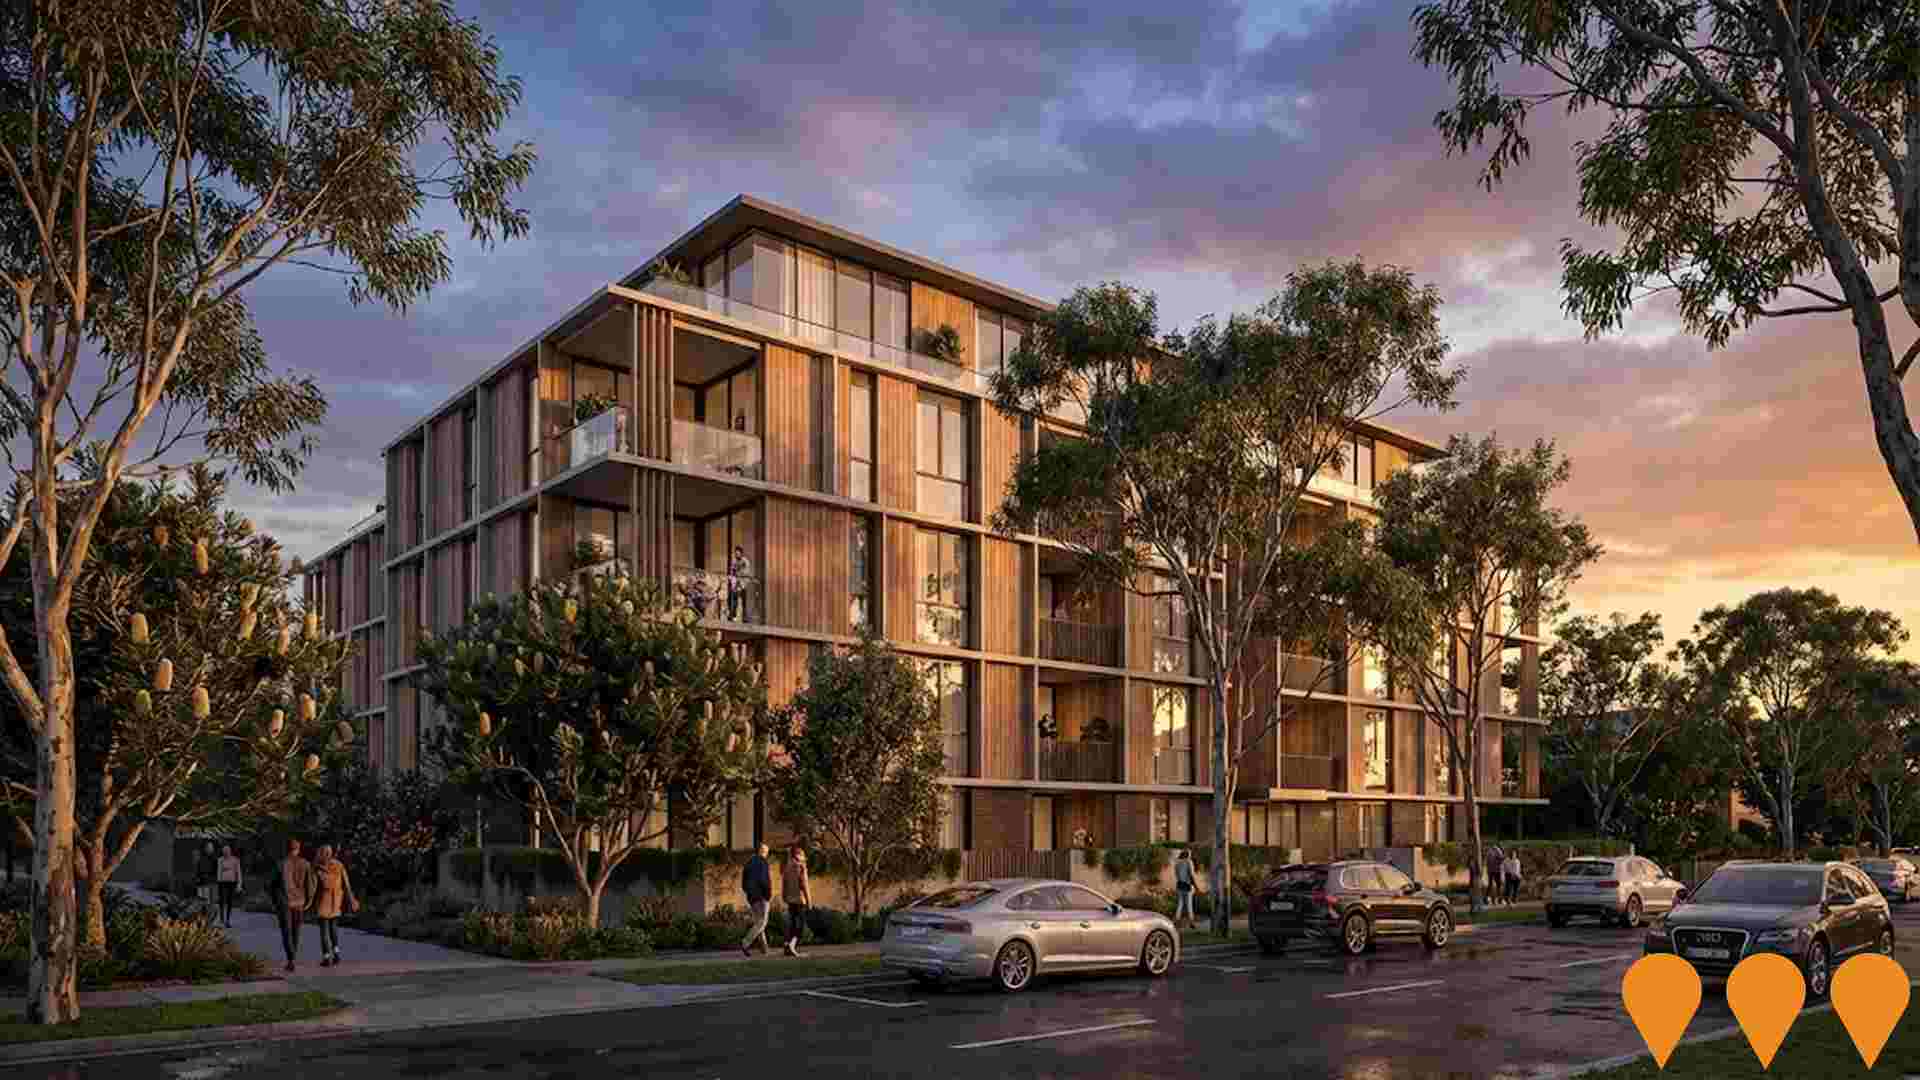
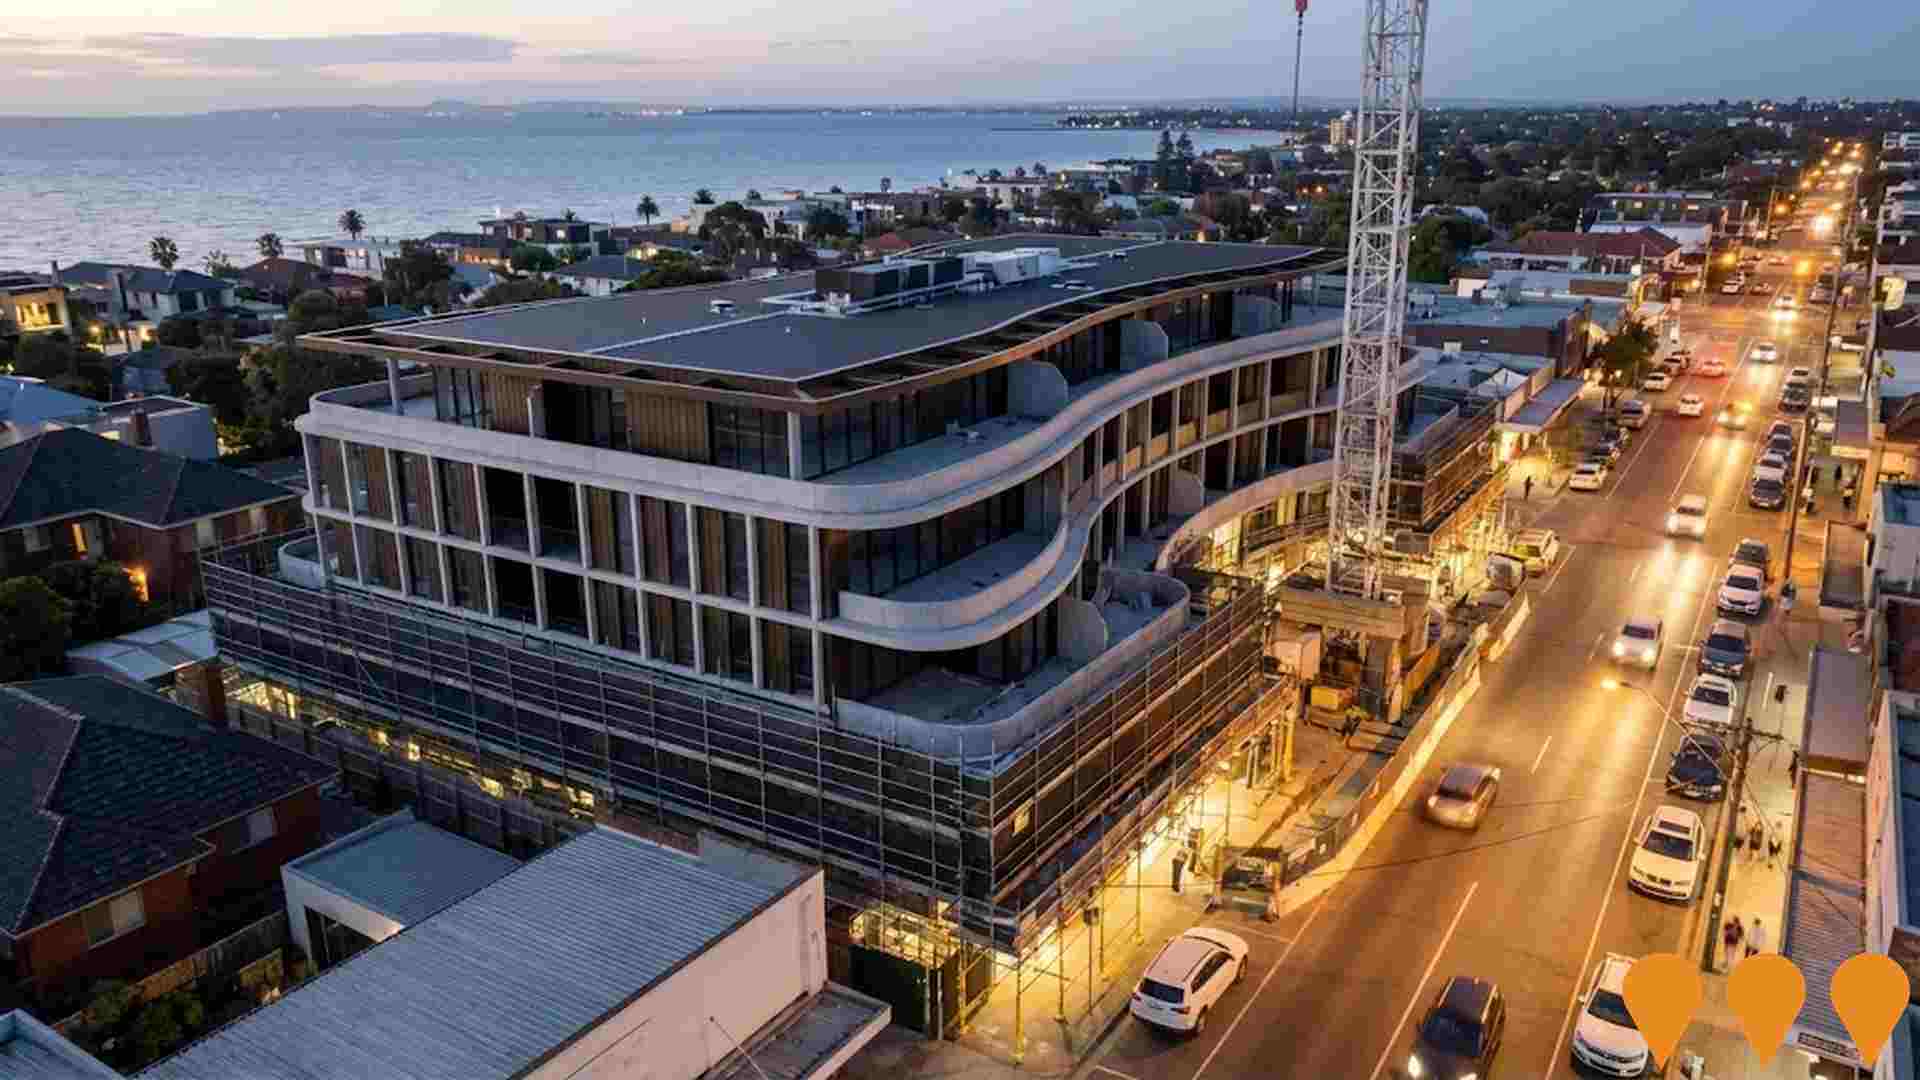
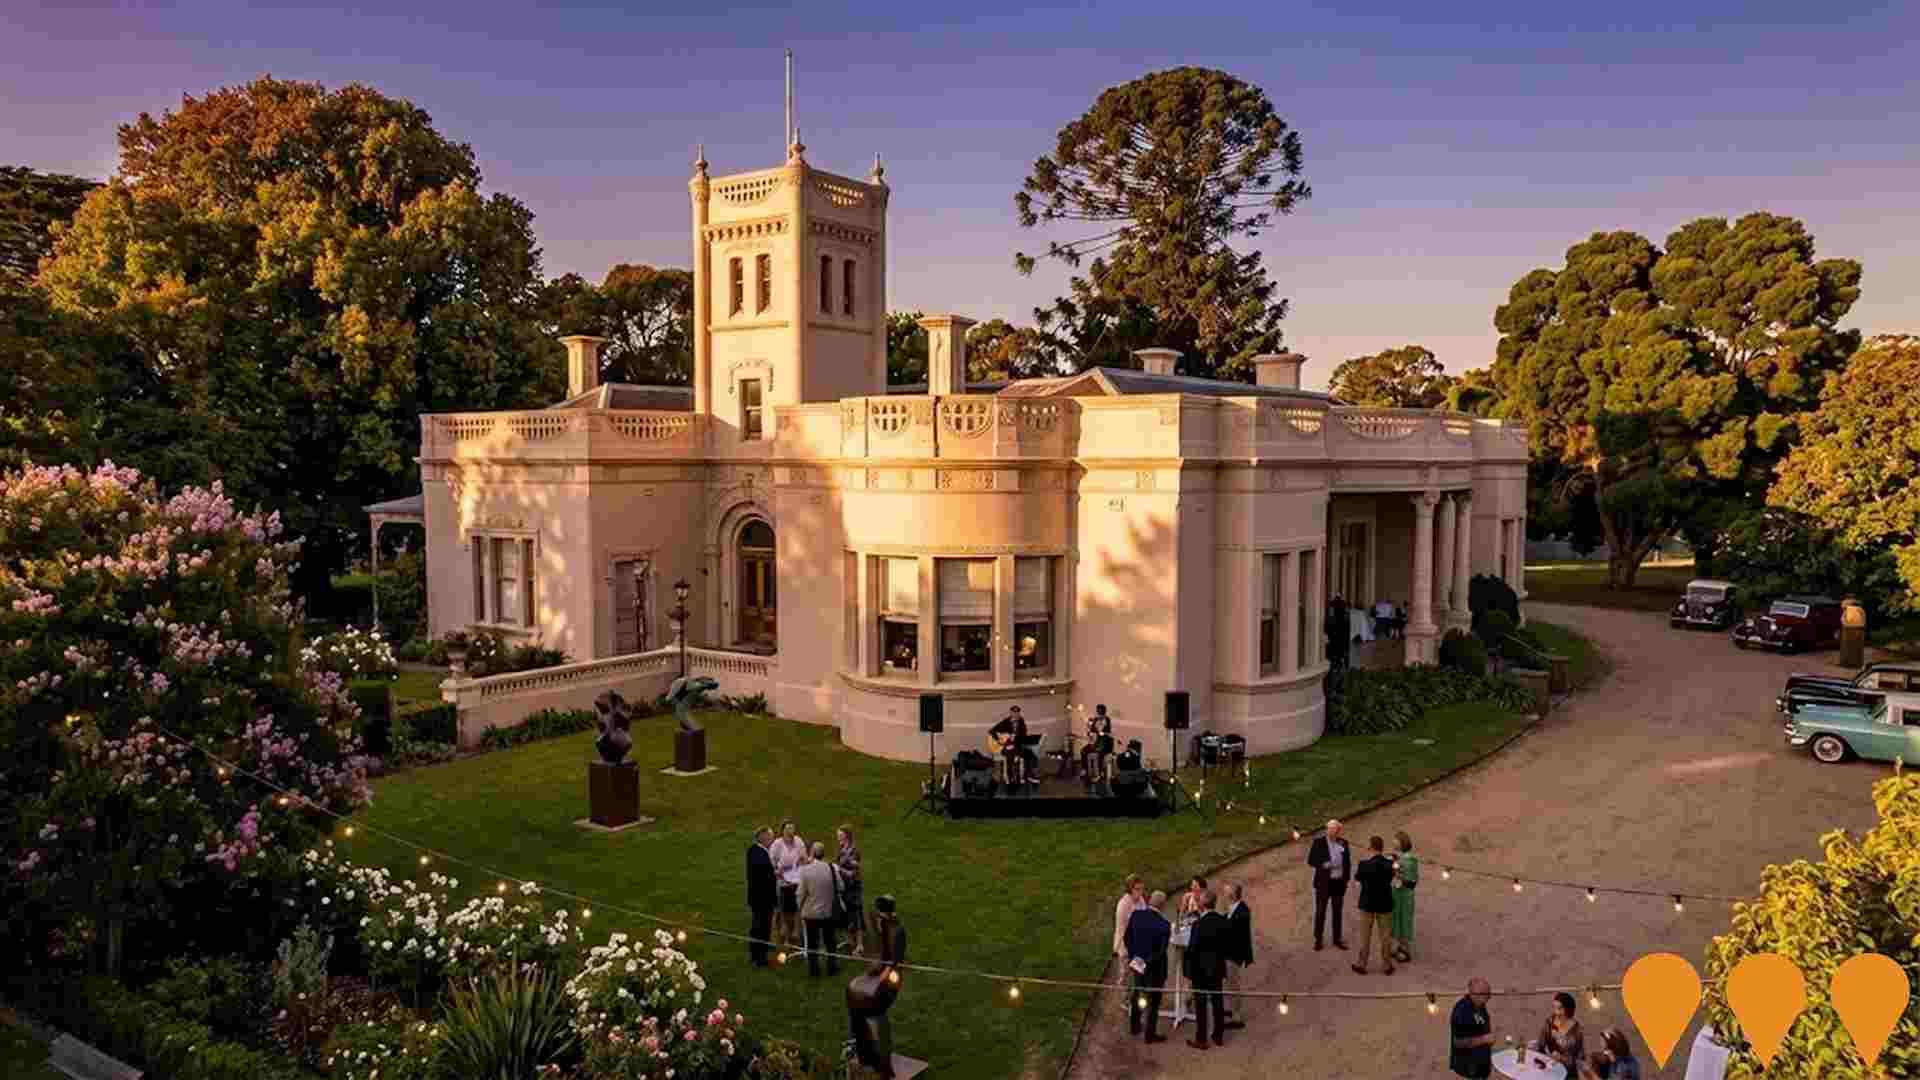
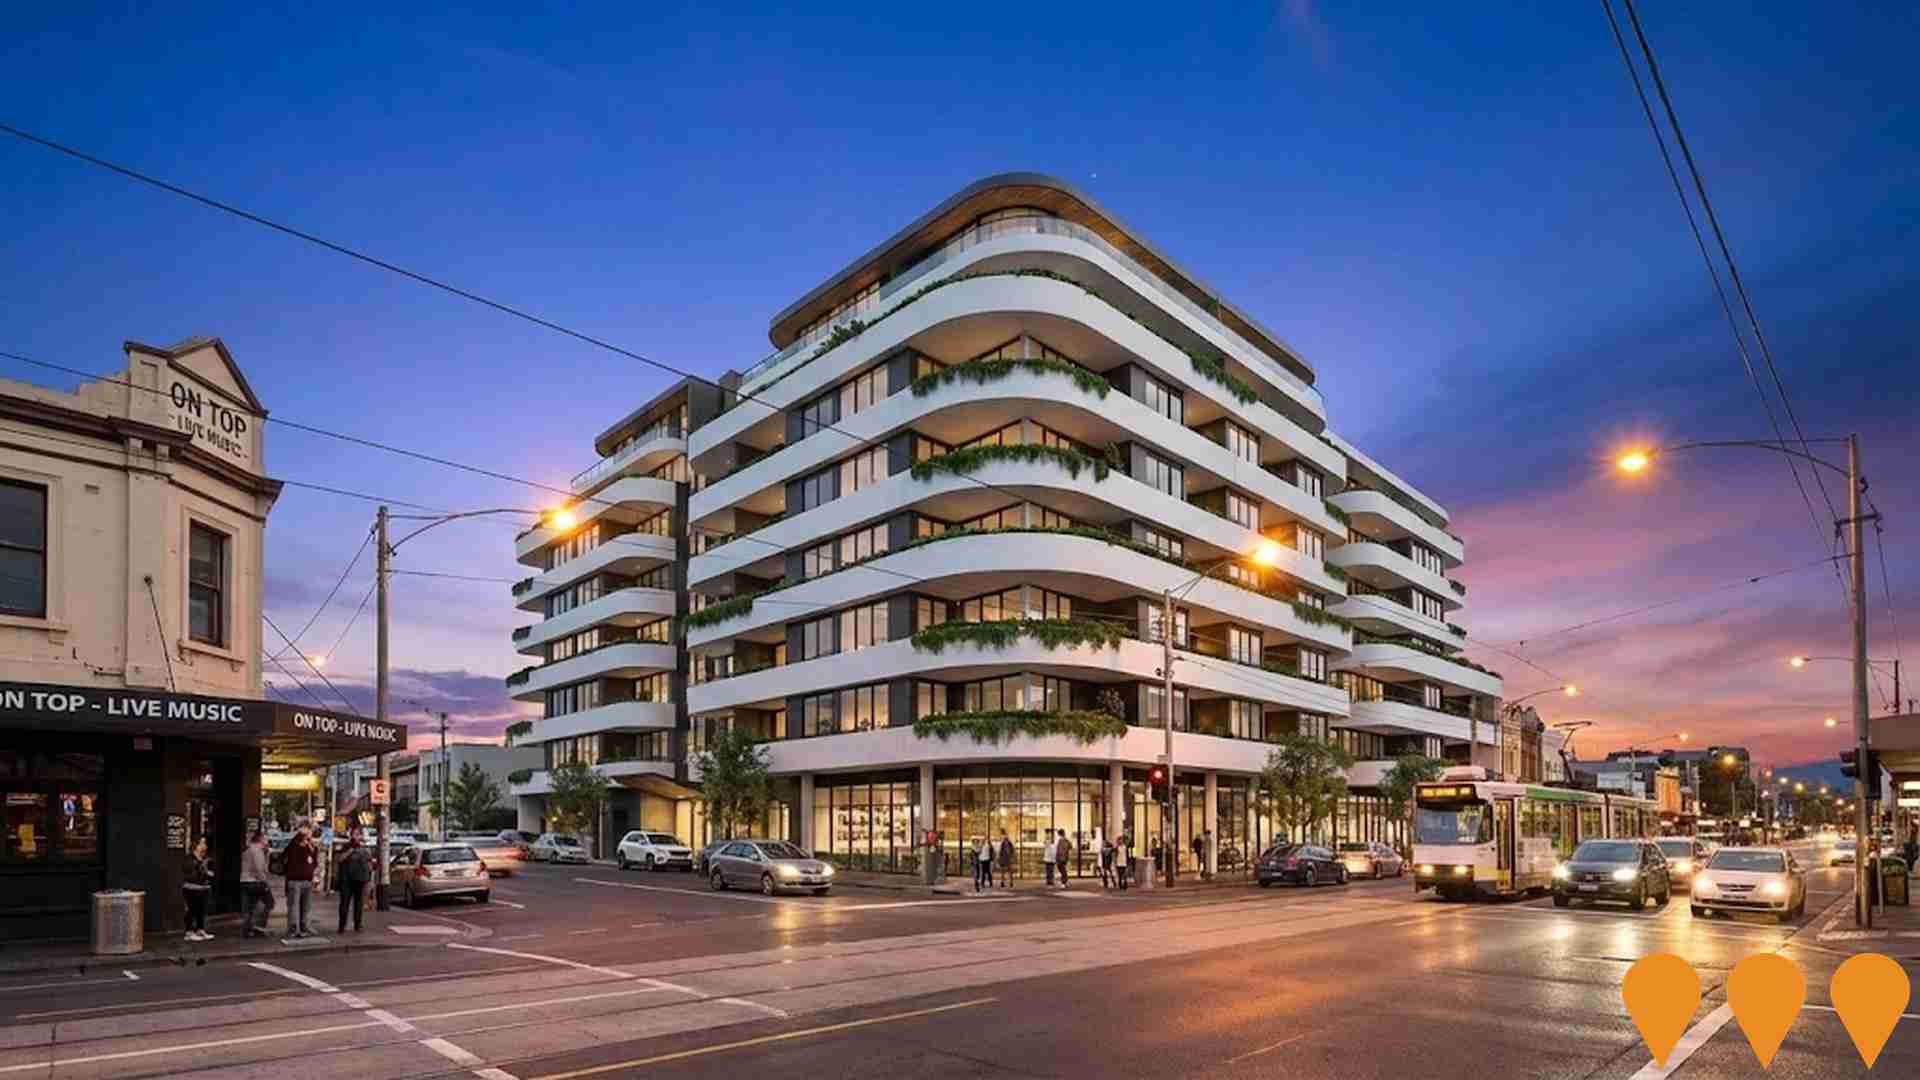
 Denotes AI-based impression for illustrative purposes only, not to be taken as definitive under any circumstances. Please follow links and conduct other investigations from the project's source for actual imagery. Developers and project owners wishing us to use original imagery please Contact Us and we will do so.
Frequently Asked Questions - Infrastructure
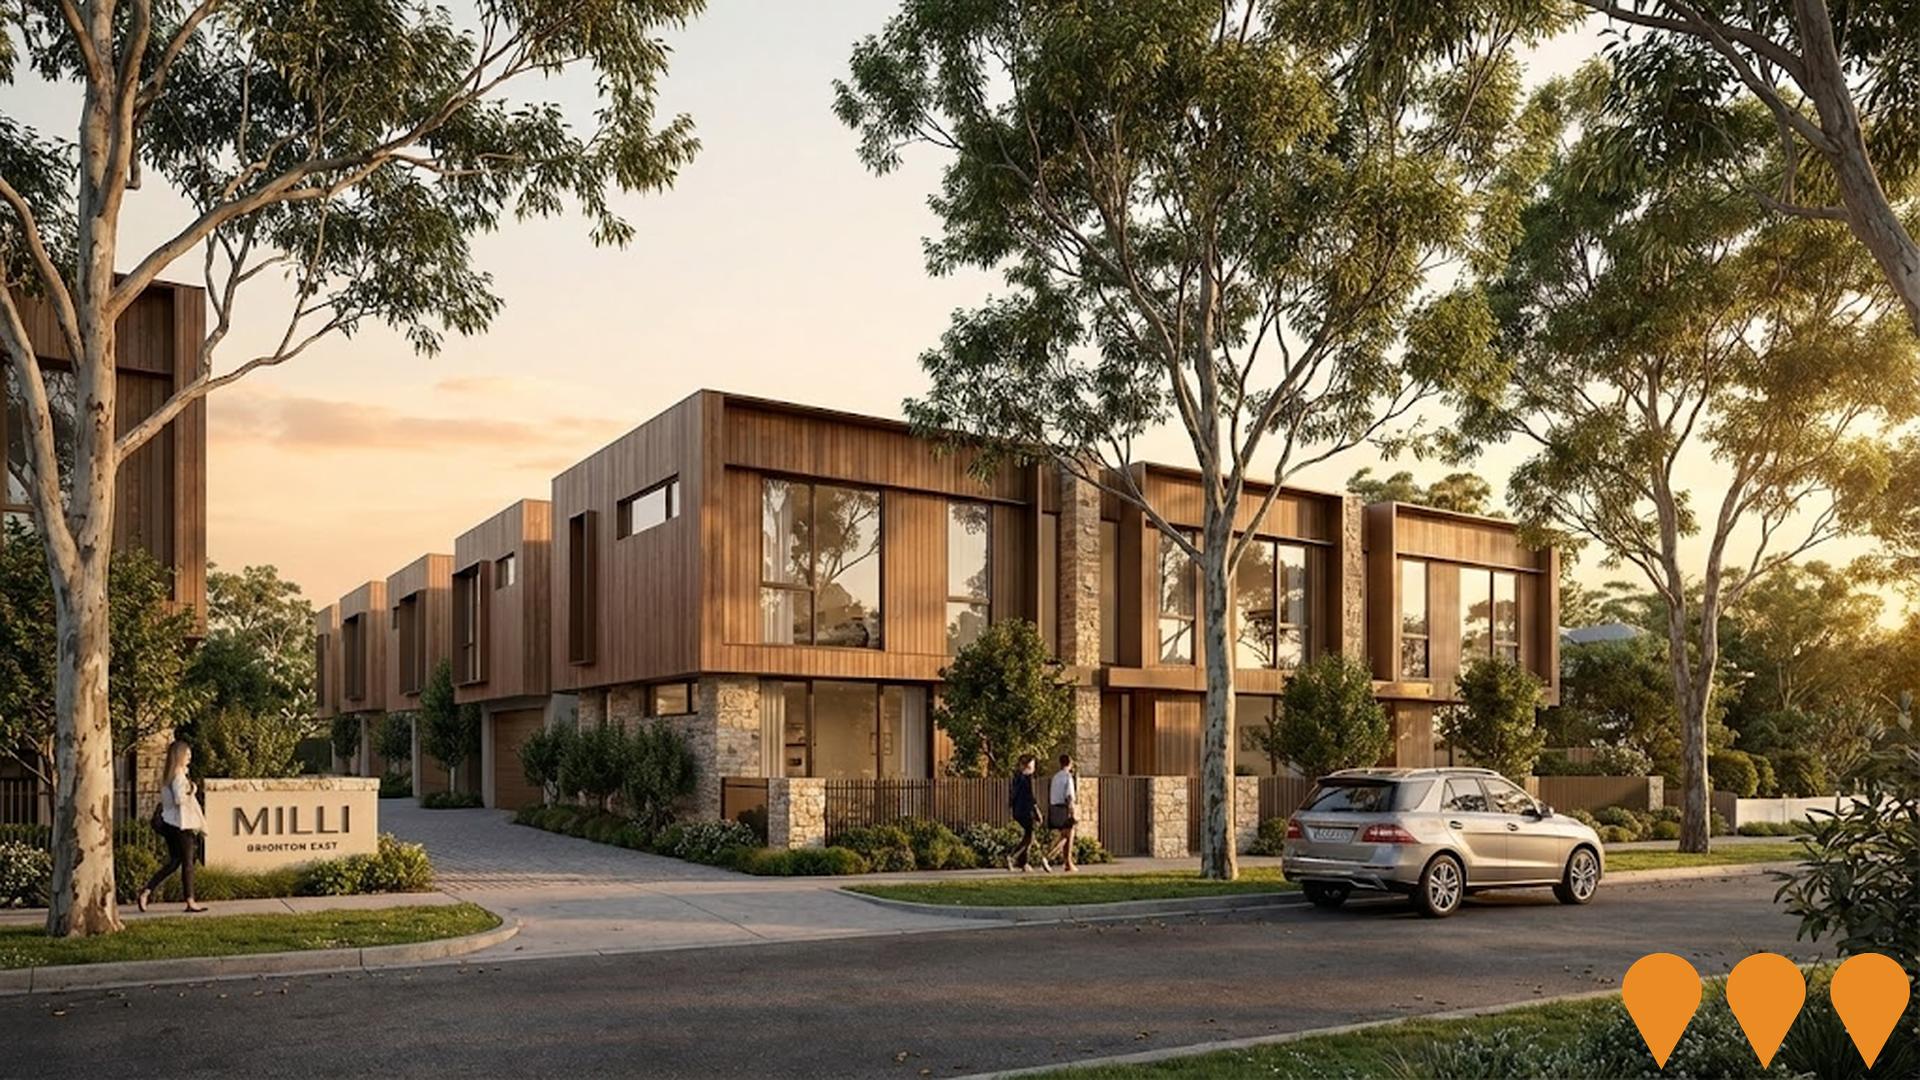
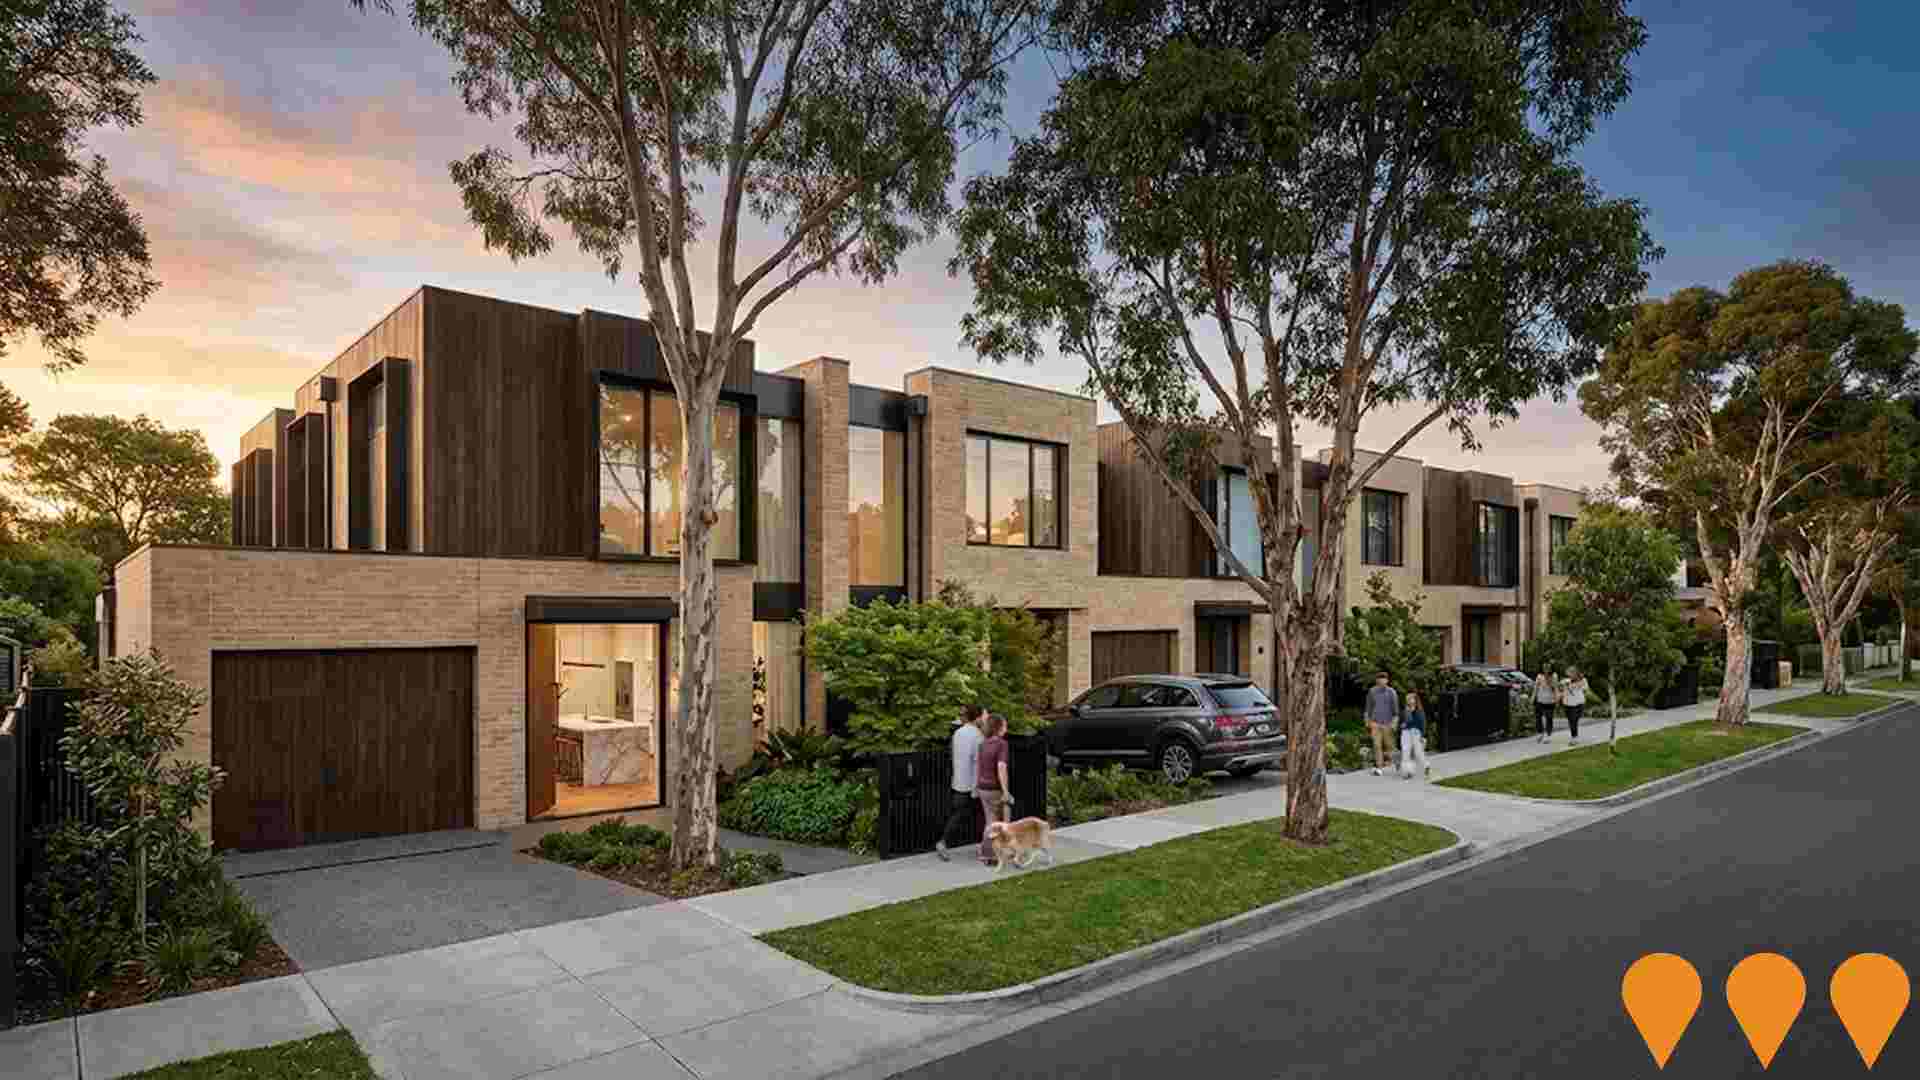
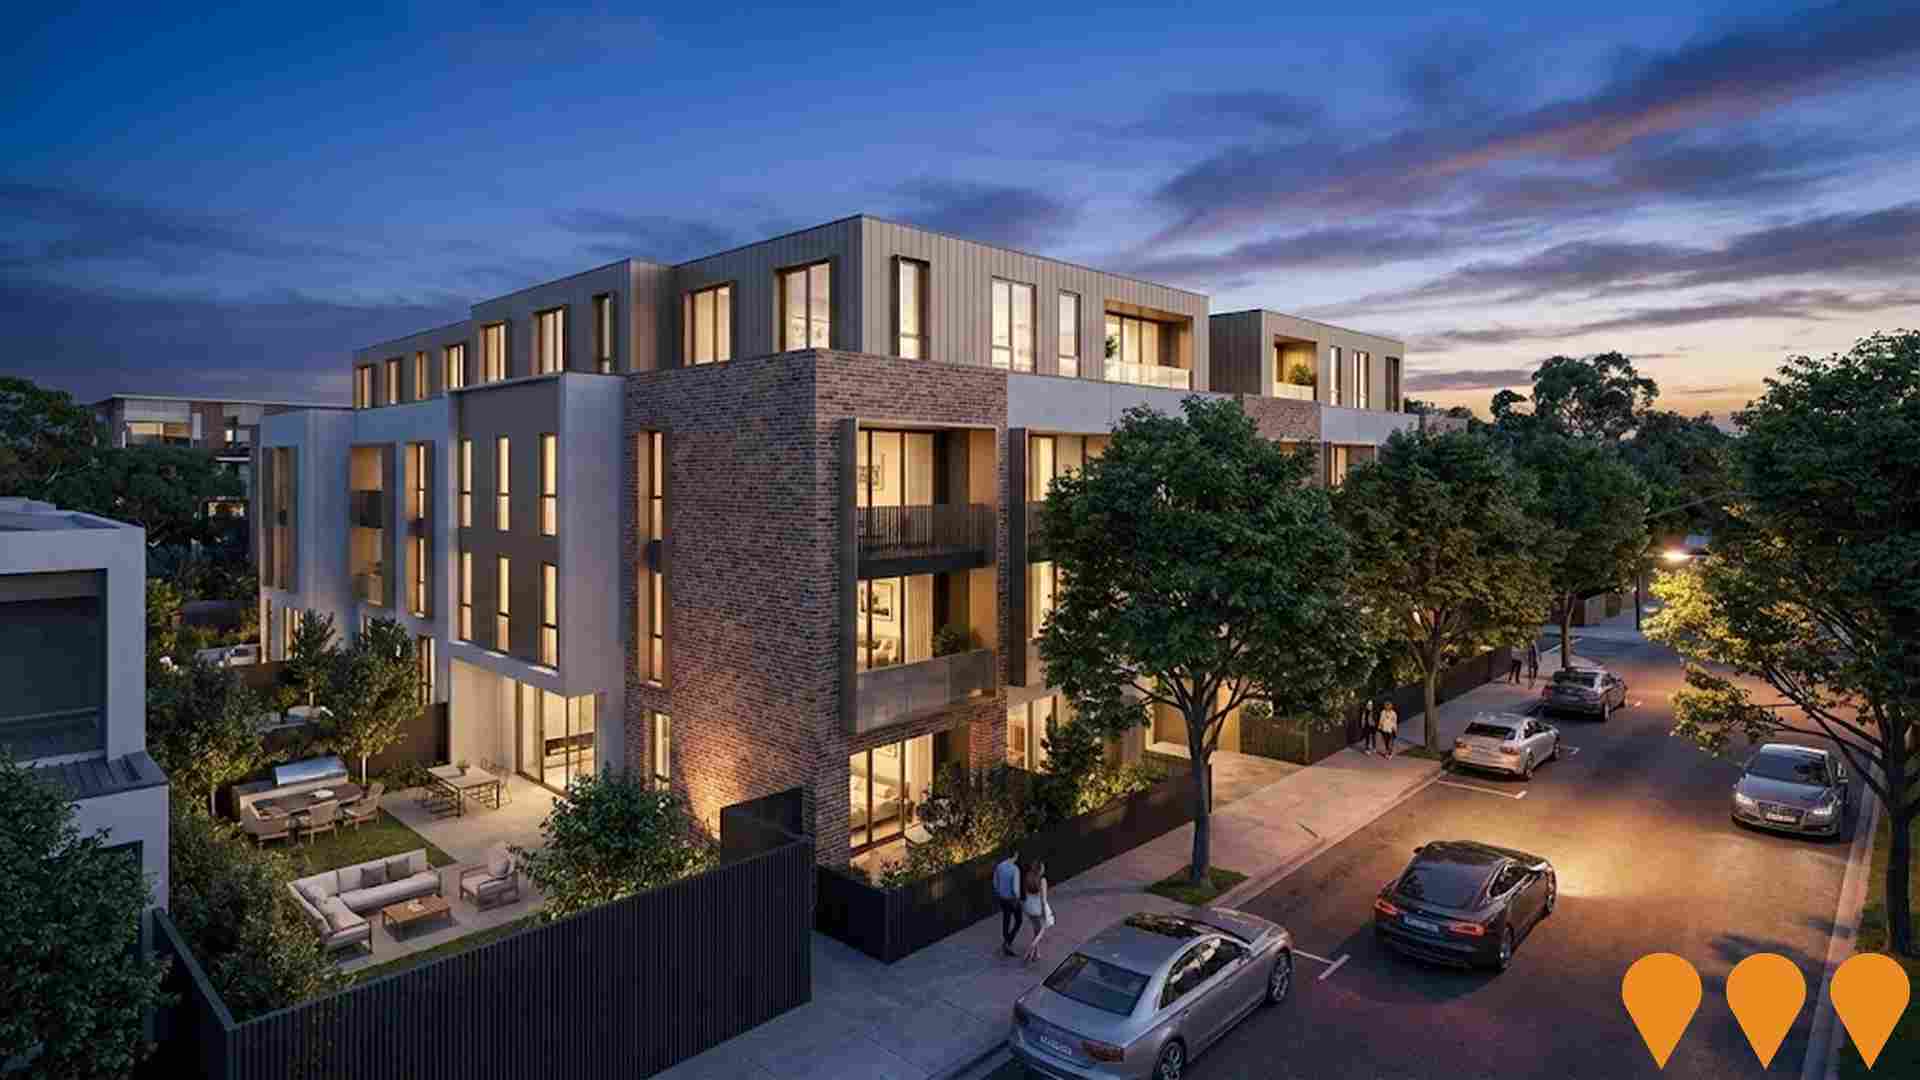
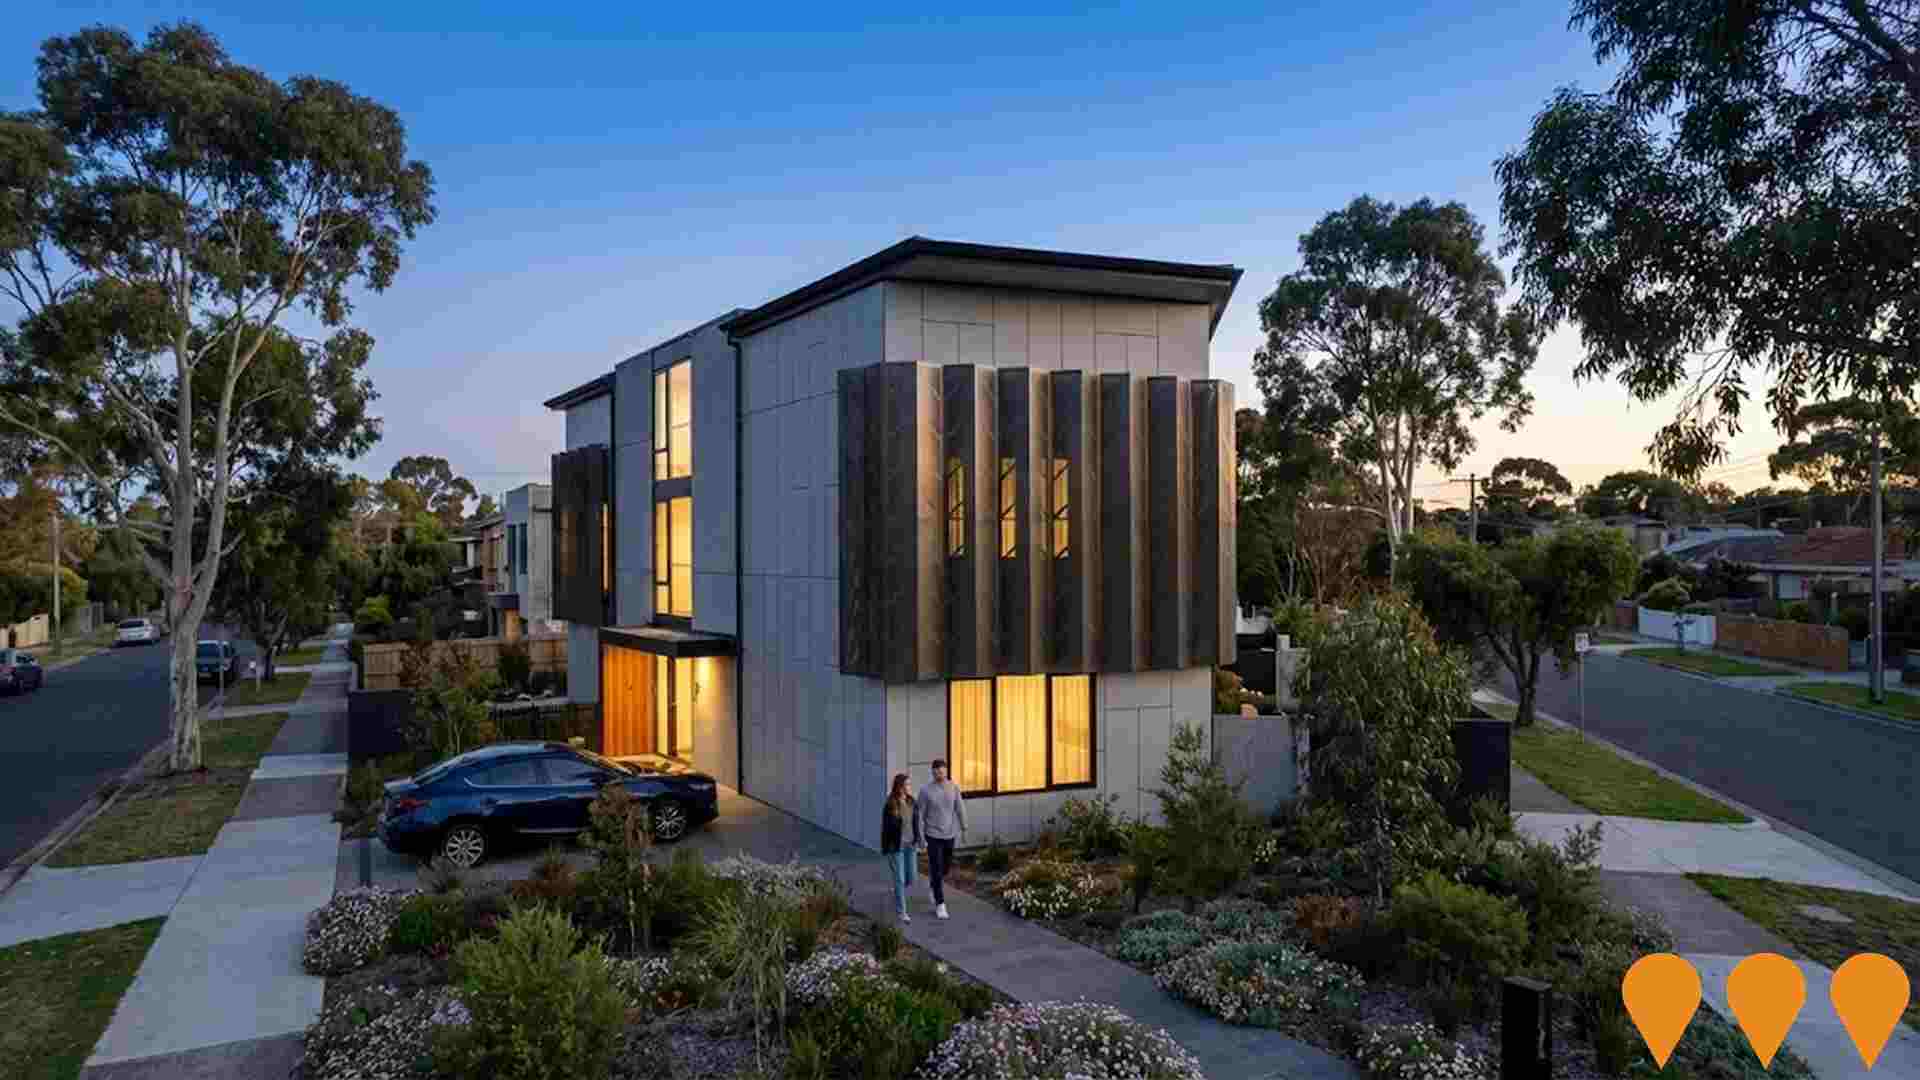
Milli Brighton East
Contemporary village of 28 exclusive townhomes in Brighton East designed by Cera Stribley Architects and DM Property. Features 3 and 4-bedroom residences with open-plan living, inspired by natural rhythms and textures of the bay. Development includes established trees, parklands, and leafy streetscapes with proximity to Brighton Beach.
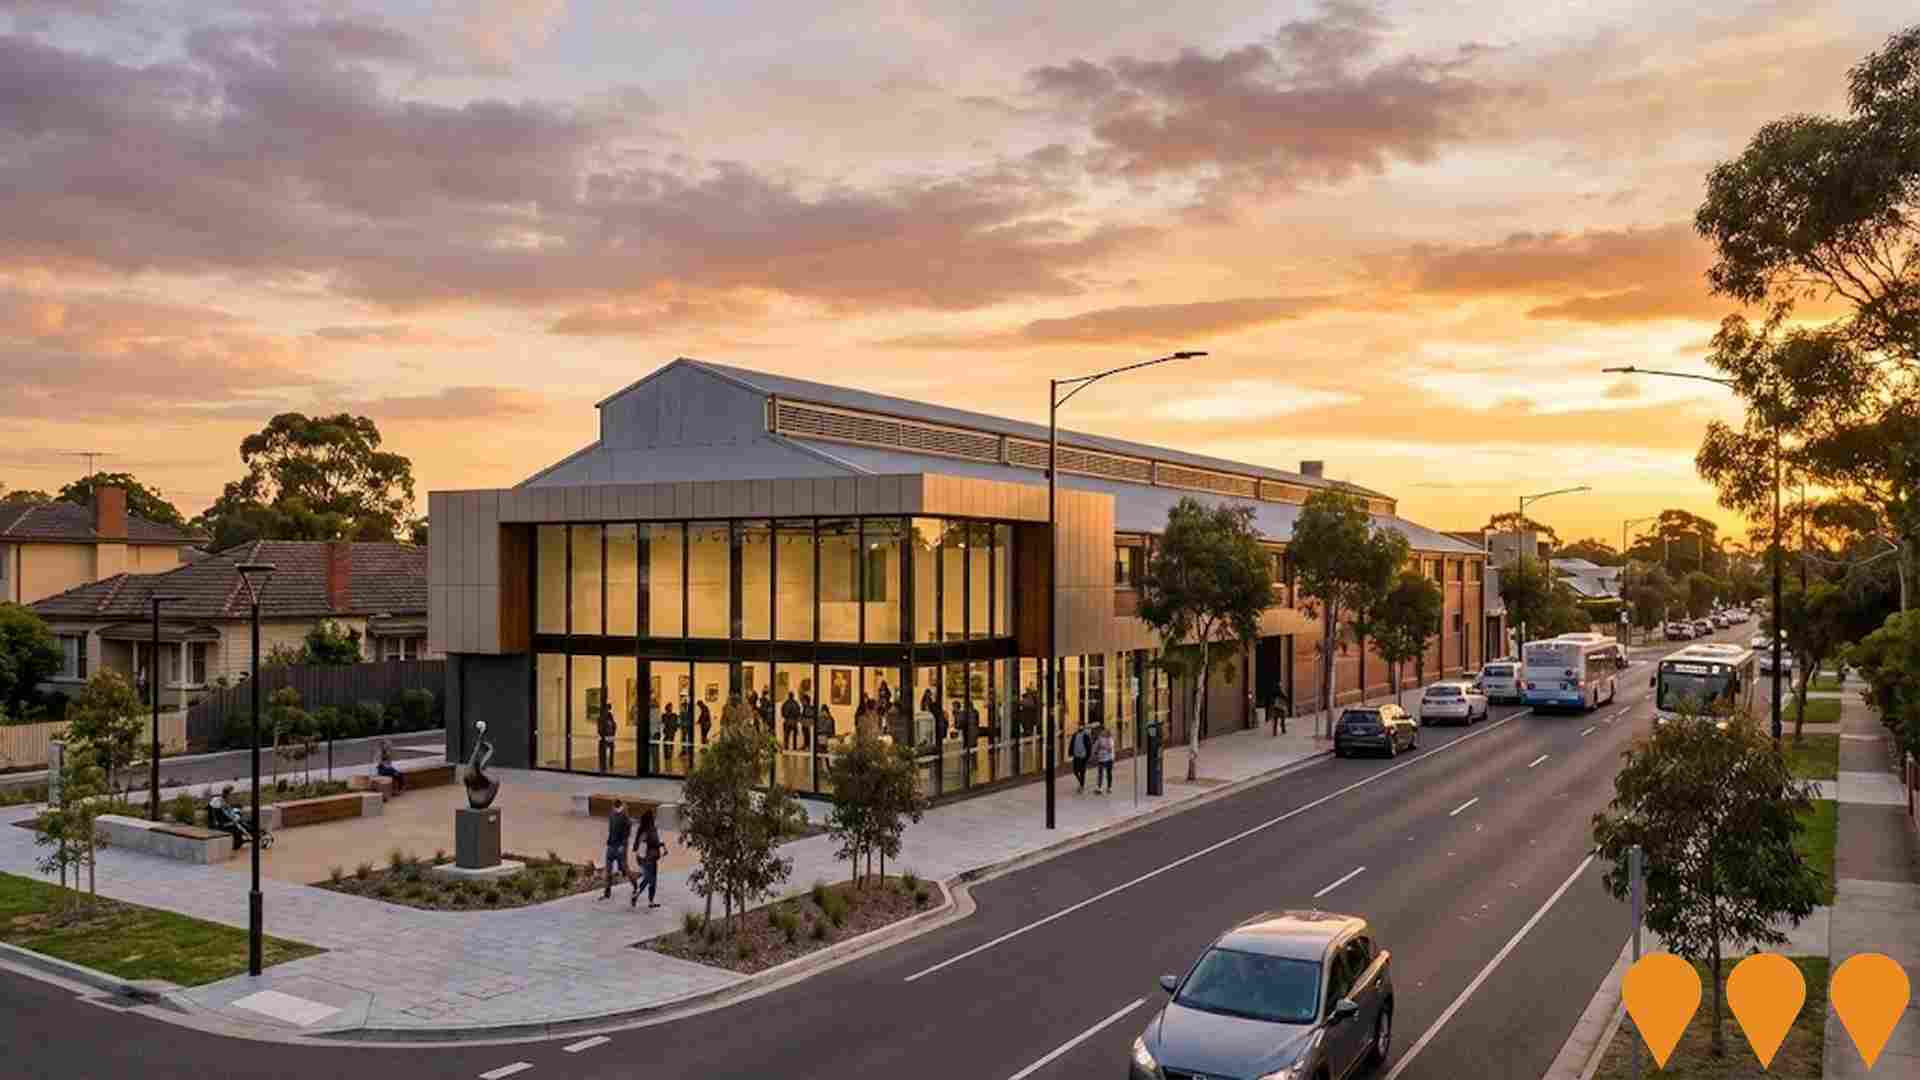
Bayside Gallery Building Works
Renovation and expansion works for the Bayside Gallery, enhancing the cultural facilities and exhibition spaces. The project includes modernization of gallery spaces, improved accessibility, and enhanced visitor amenities.
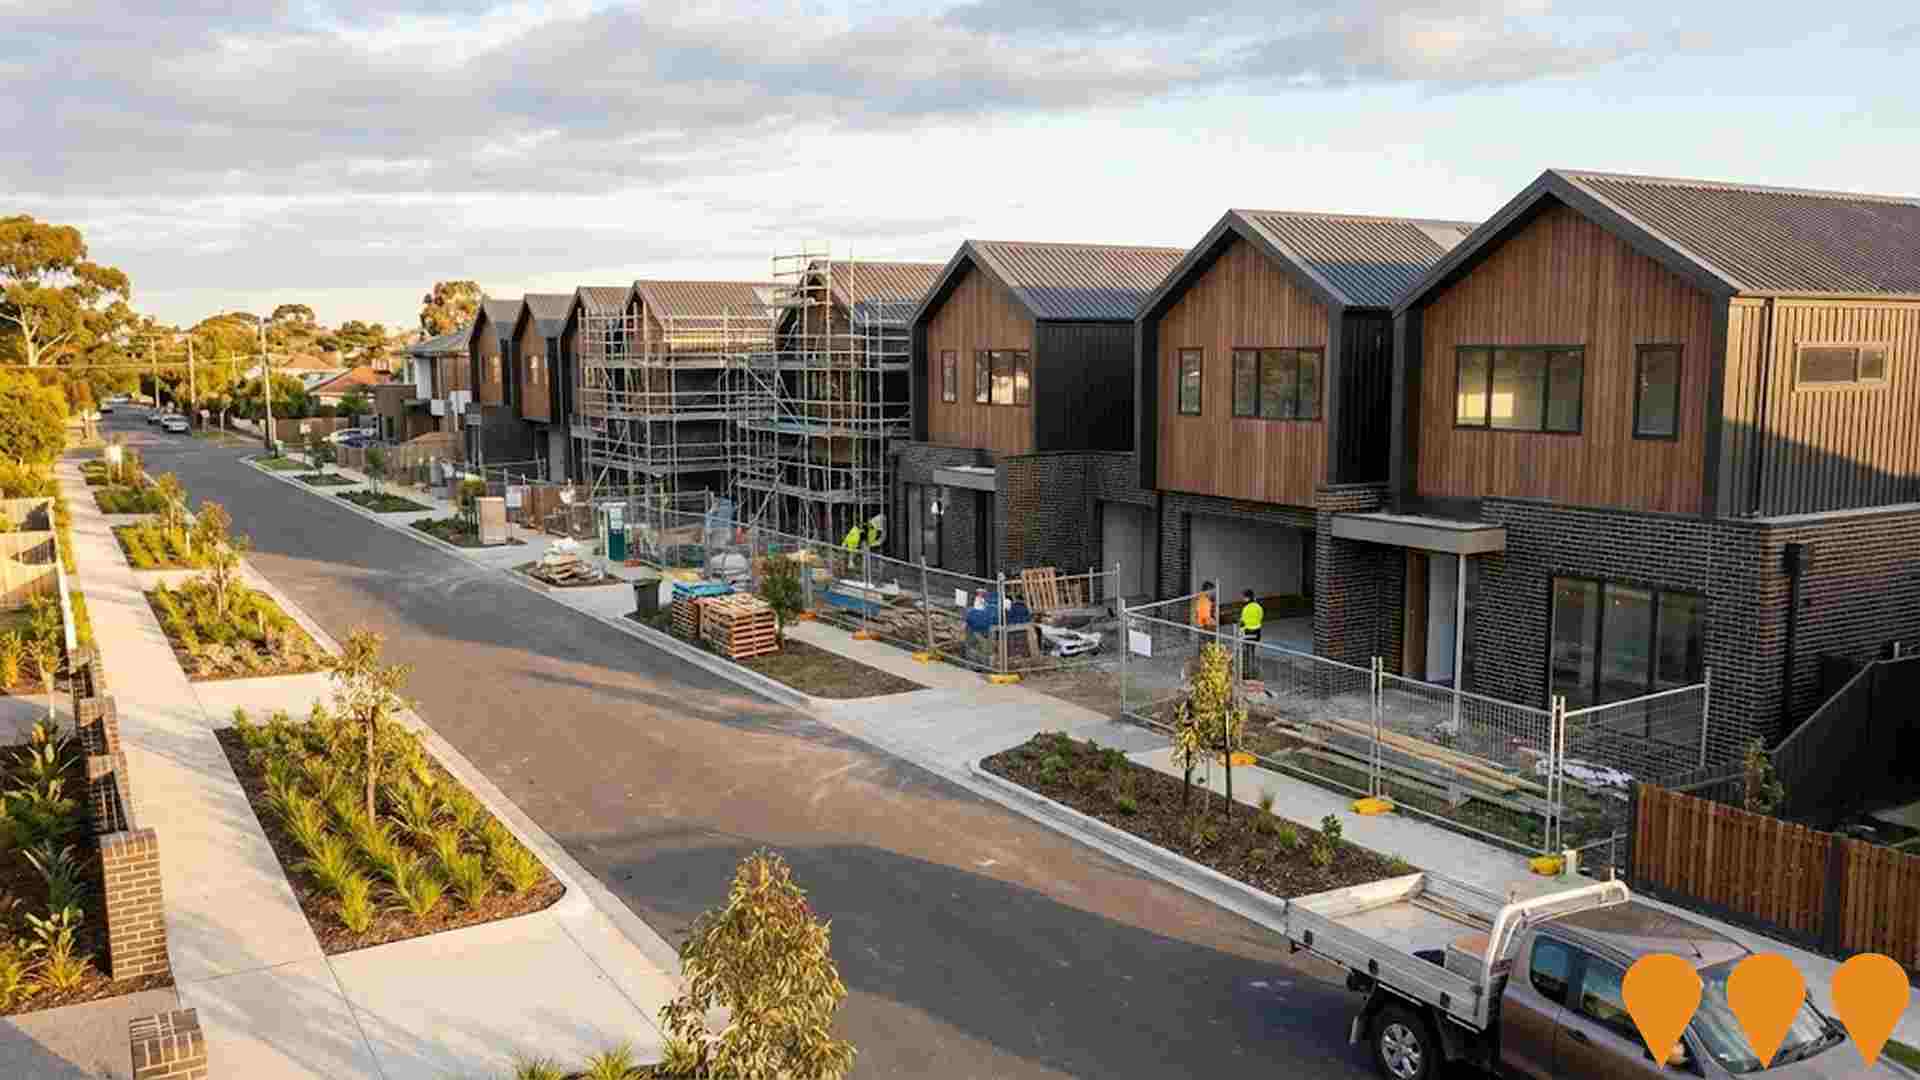
Laurel, Bentleigh (Bentleigh Club Redevelopment)
Redevelopment of the former Bentleigh Club site into Laurel, a Metro Property Development townhome project in Bentleigh. Now under construction and nearing completion, the project delivers 35 all-electric family townhomes across 4 and 5 bedroom layouts with two living zones, street frontage, deep backyards, double glazing, 7.5-star NatHERS ratings and 4.4kW solar systems. Architecture is by ClarkeHopkinsClarke with landscapes by MDG Landscape Architects, and the project is marketed by Marshall White Projects. Homes are priced from $1,595,000 with move-in expected in spring 2026.
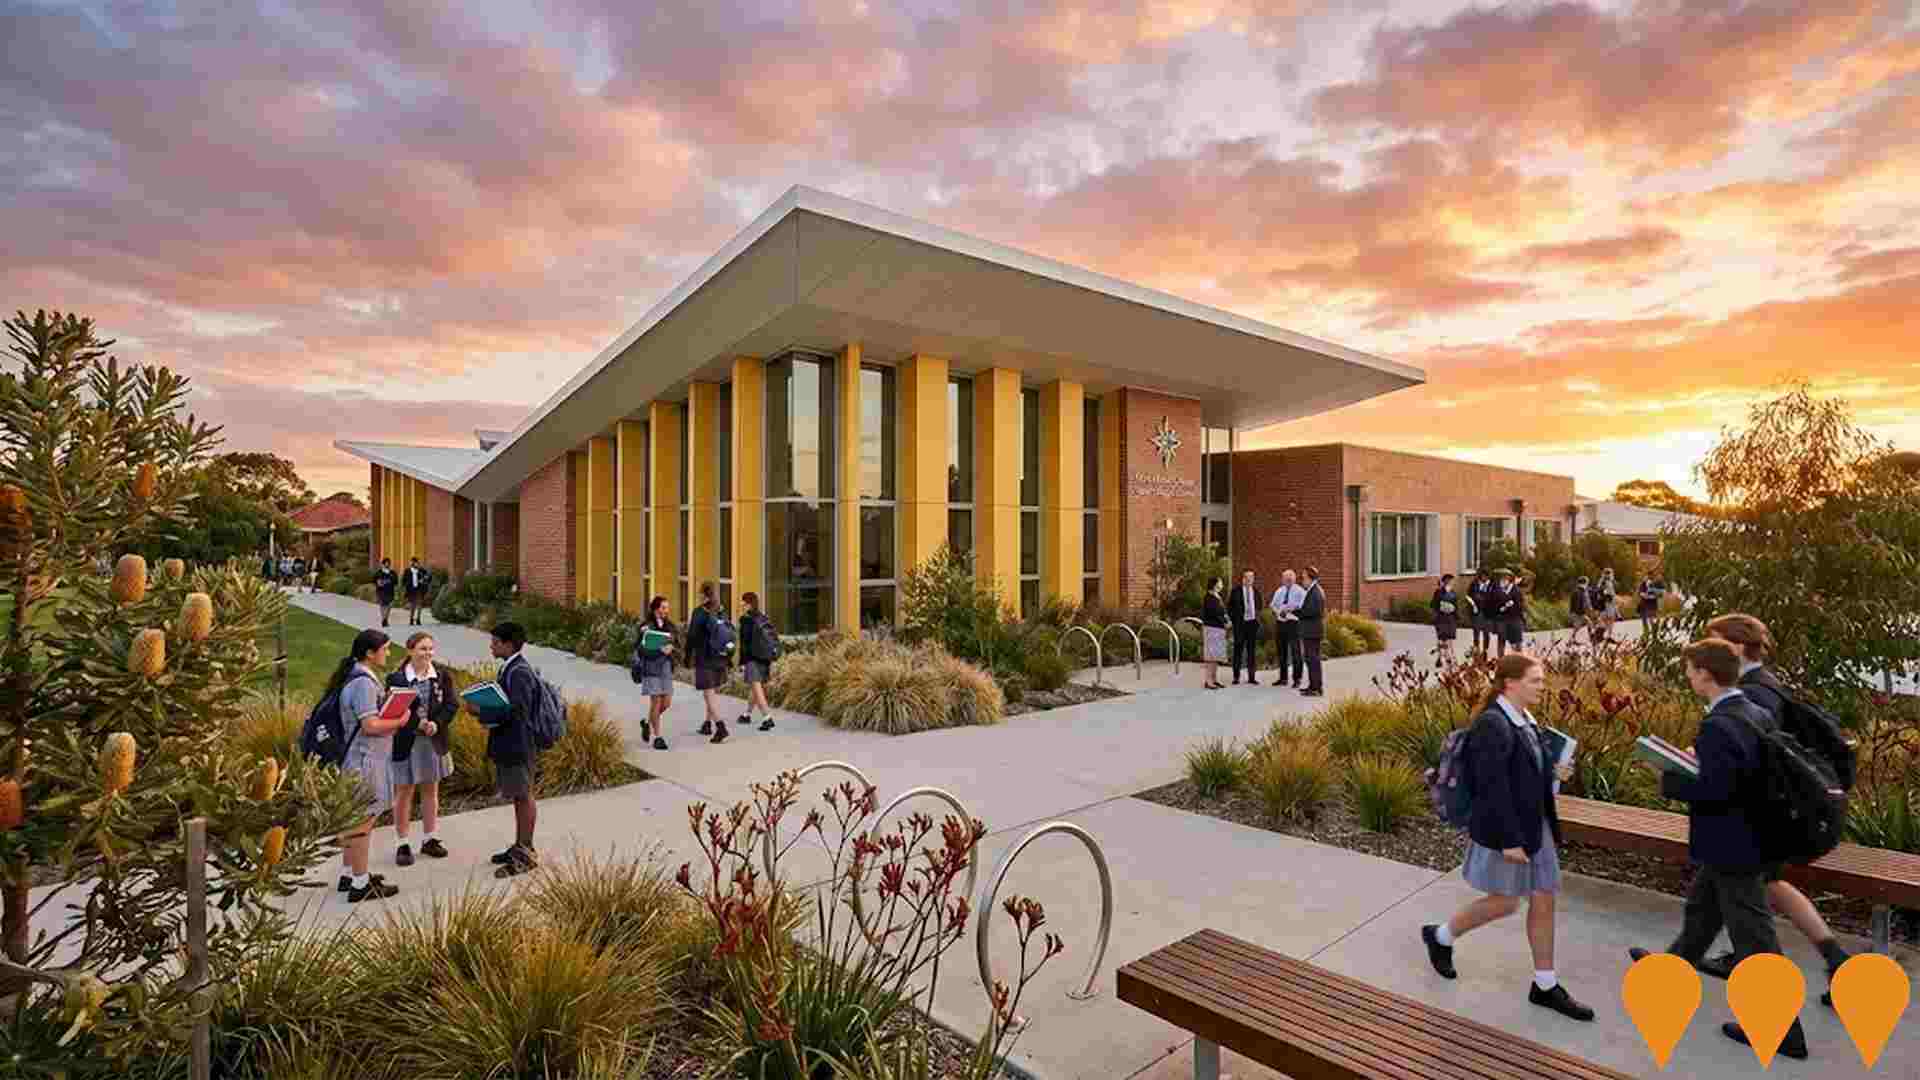
Star of the Sea College Nano Nagle Centre
Construction of the Nano Nagle Centre as the next stage of the Star of the Sea College Master Plan. The redevelopment replaces Sebastian Hall with a modern multi-level education and community facility including two full-sized basketball courts, 900 retractable seats, flexible learning spaces, student social areas and future stages incorporating a new library and cafe. Construction commenced in 2025 with Stage 1 progressing and targeted for completion by the end of 2026.
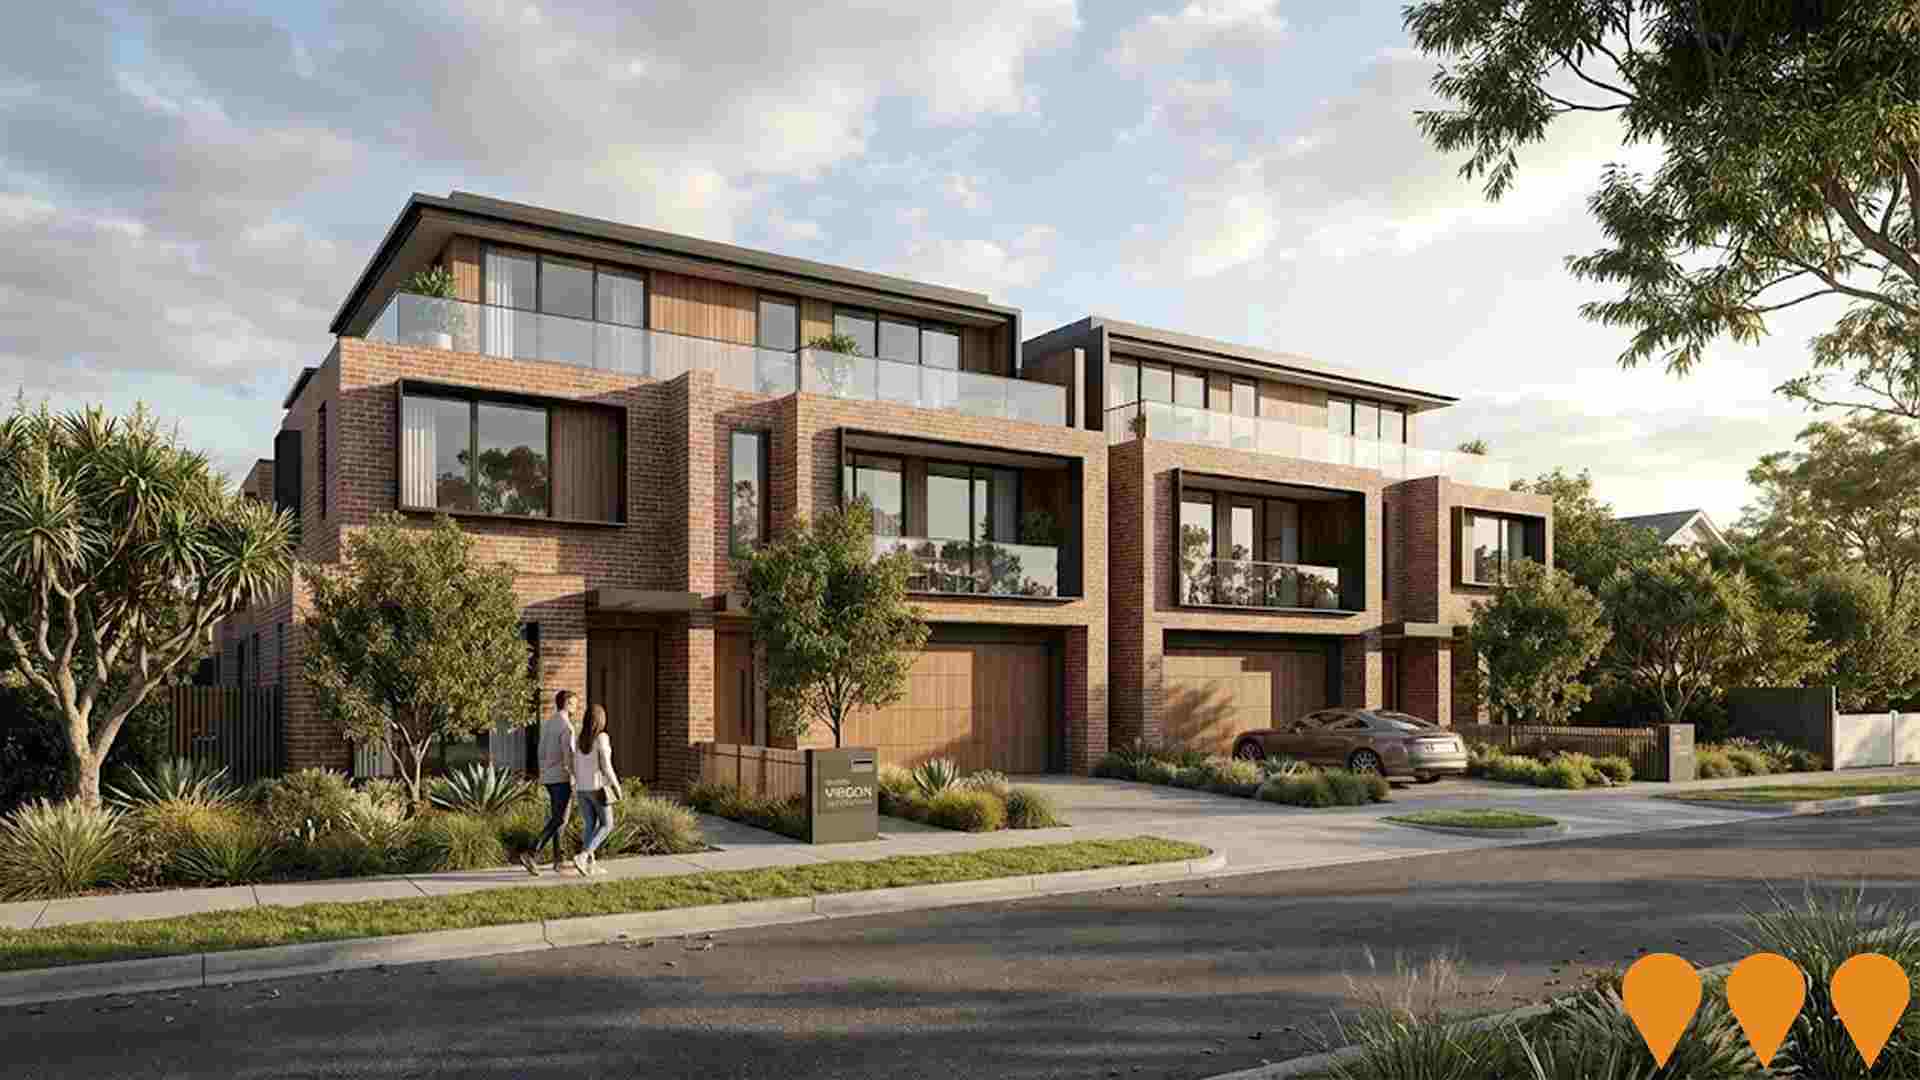
111 Carpenter Brighton Townhomes
Boutique development of seven two and three-level townhomes by Sloane Property, with architecture by Megowan and landscaping by John Patrick. Builder is Virgon Construction. Homes feature north-facing terraces, double garages and crafted interiors. Site is walking distance to North Brighton Station, Church Street and Brighton Beach. Works are underway with completion targeted for late 2025.
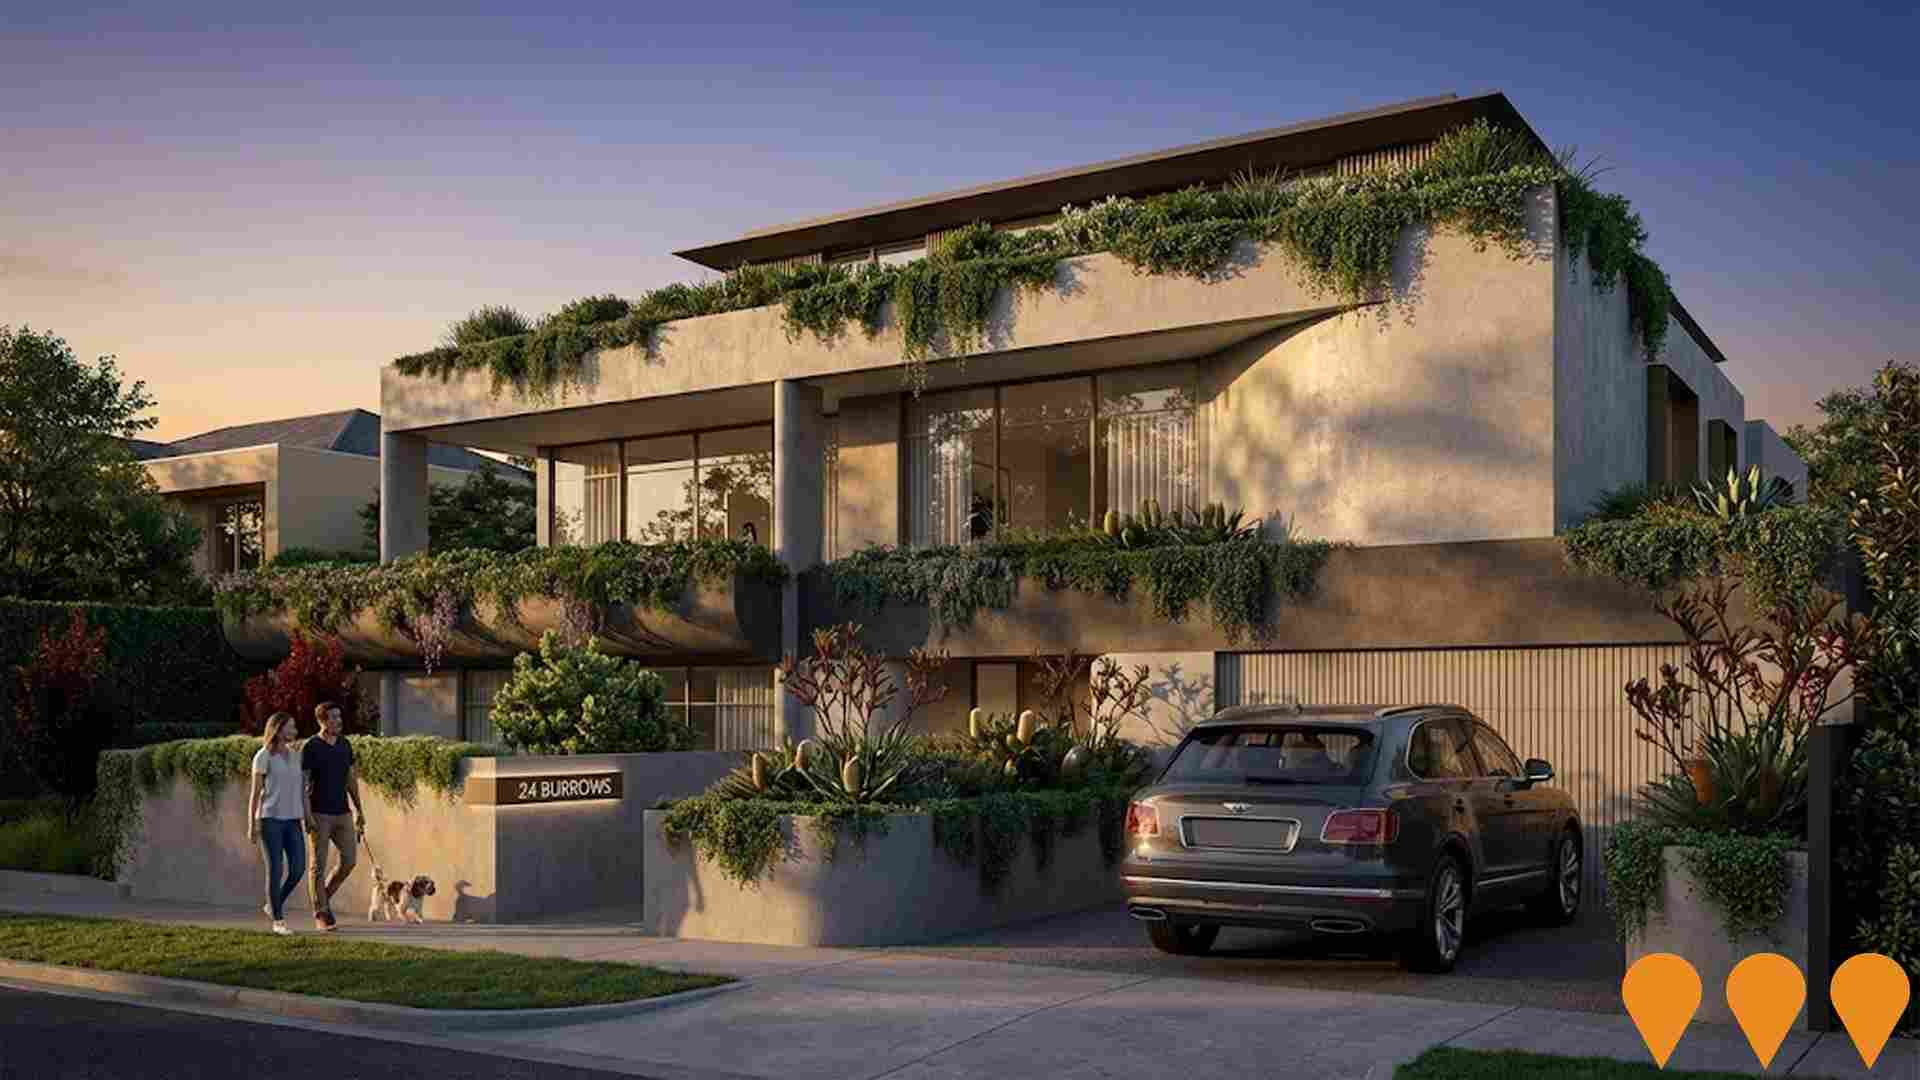
24 Burrows Street Brighton
A premium boutique development comprising six luxury residences in Brighton, offering high-end finishes including natural marble, custom joinery, and premium appliances. Designed for discerning buyers, featuring private terraces, spas, and proximity to amenities and transport.
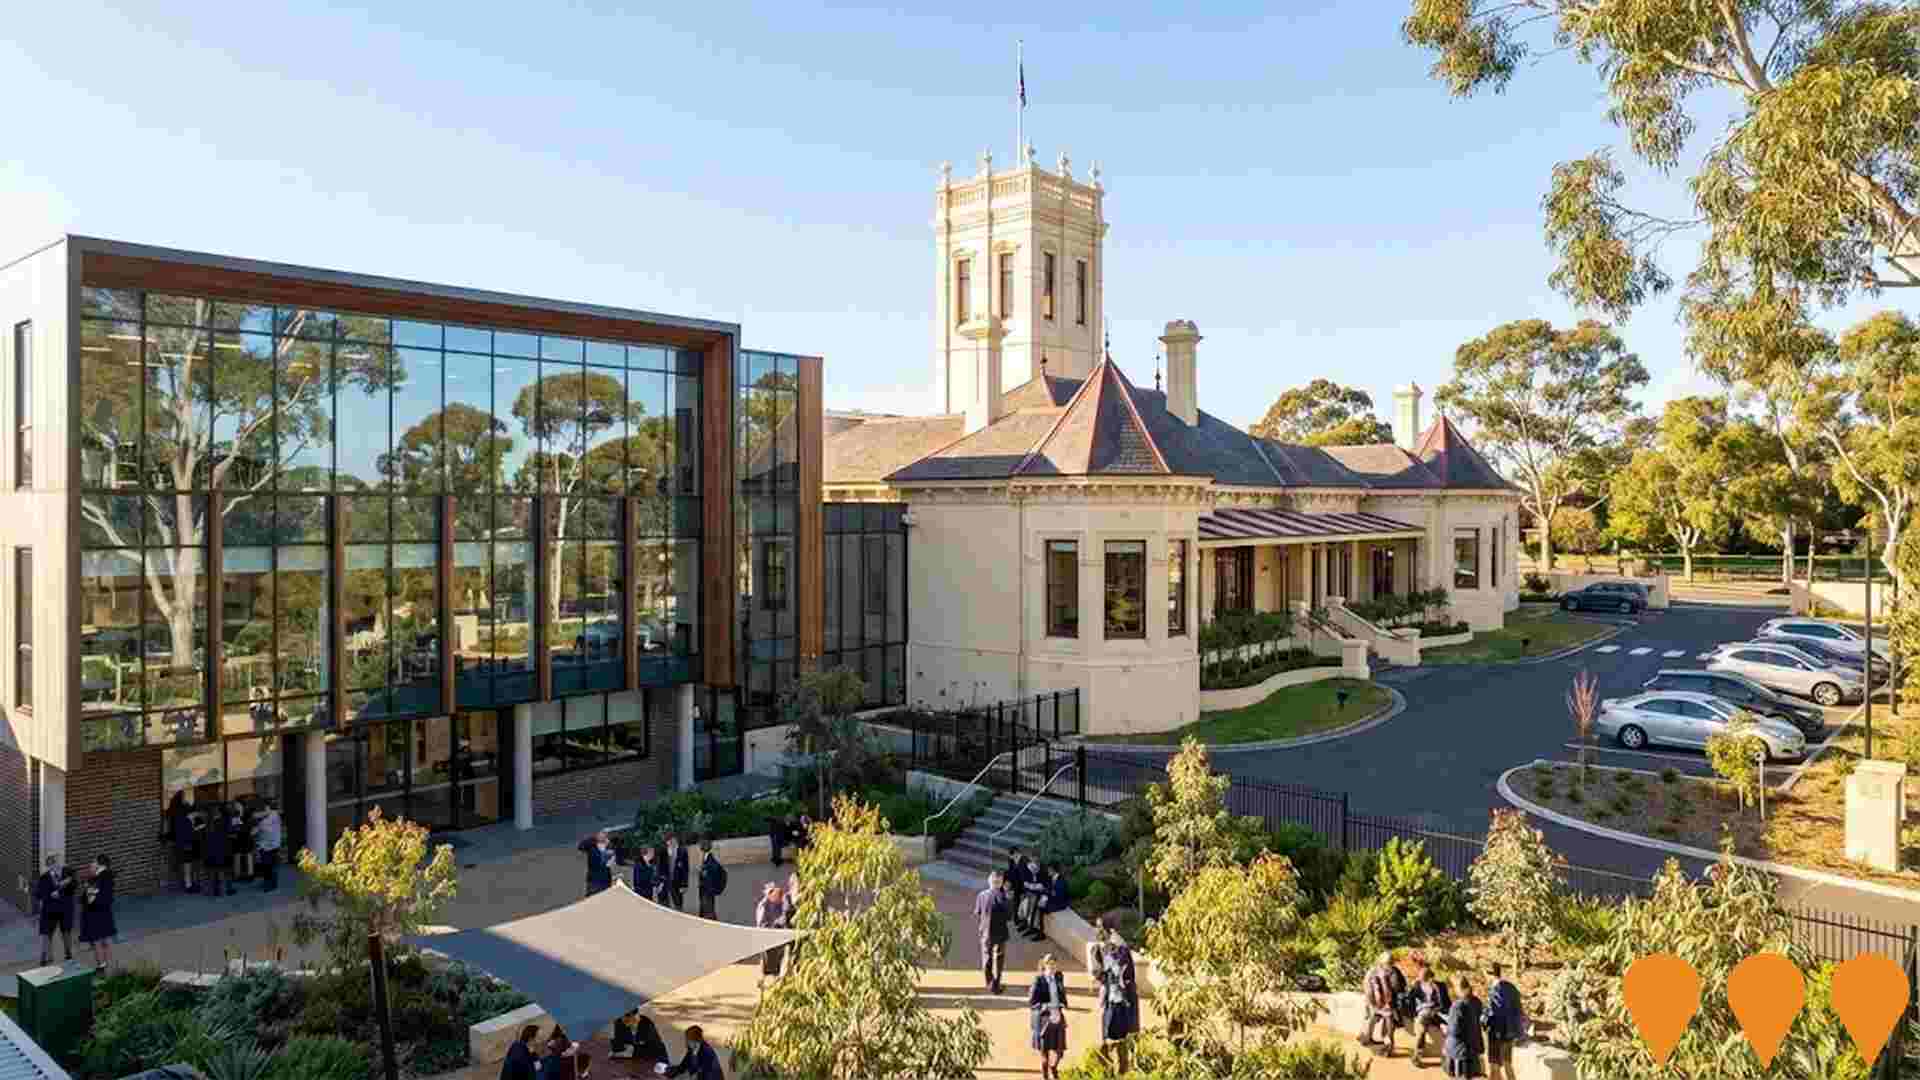
St Leonards College Expansion
Expansion of St Leonards College through the adaptive reuse of adjacent properties as an Education Centre, providing additional administration and classroom facilities within existing buildings together with new staff car and bicycle parking. The ministerial planning permit was approved in March 2024 and subsequent permit amendments were approved in February and April 2026 to refine campus works including a gatehouse, pool reception improvements, bicycle facilities and flood-related design changes.
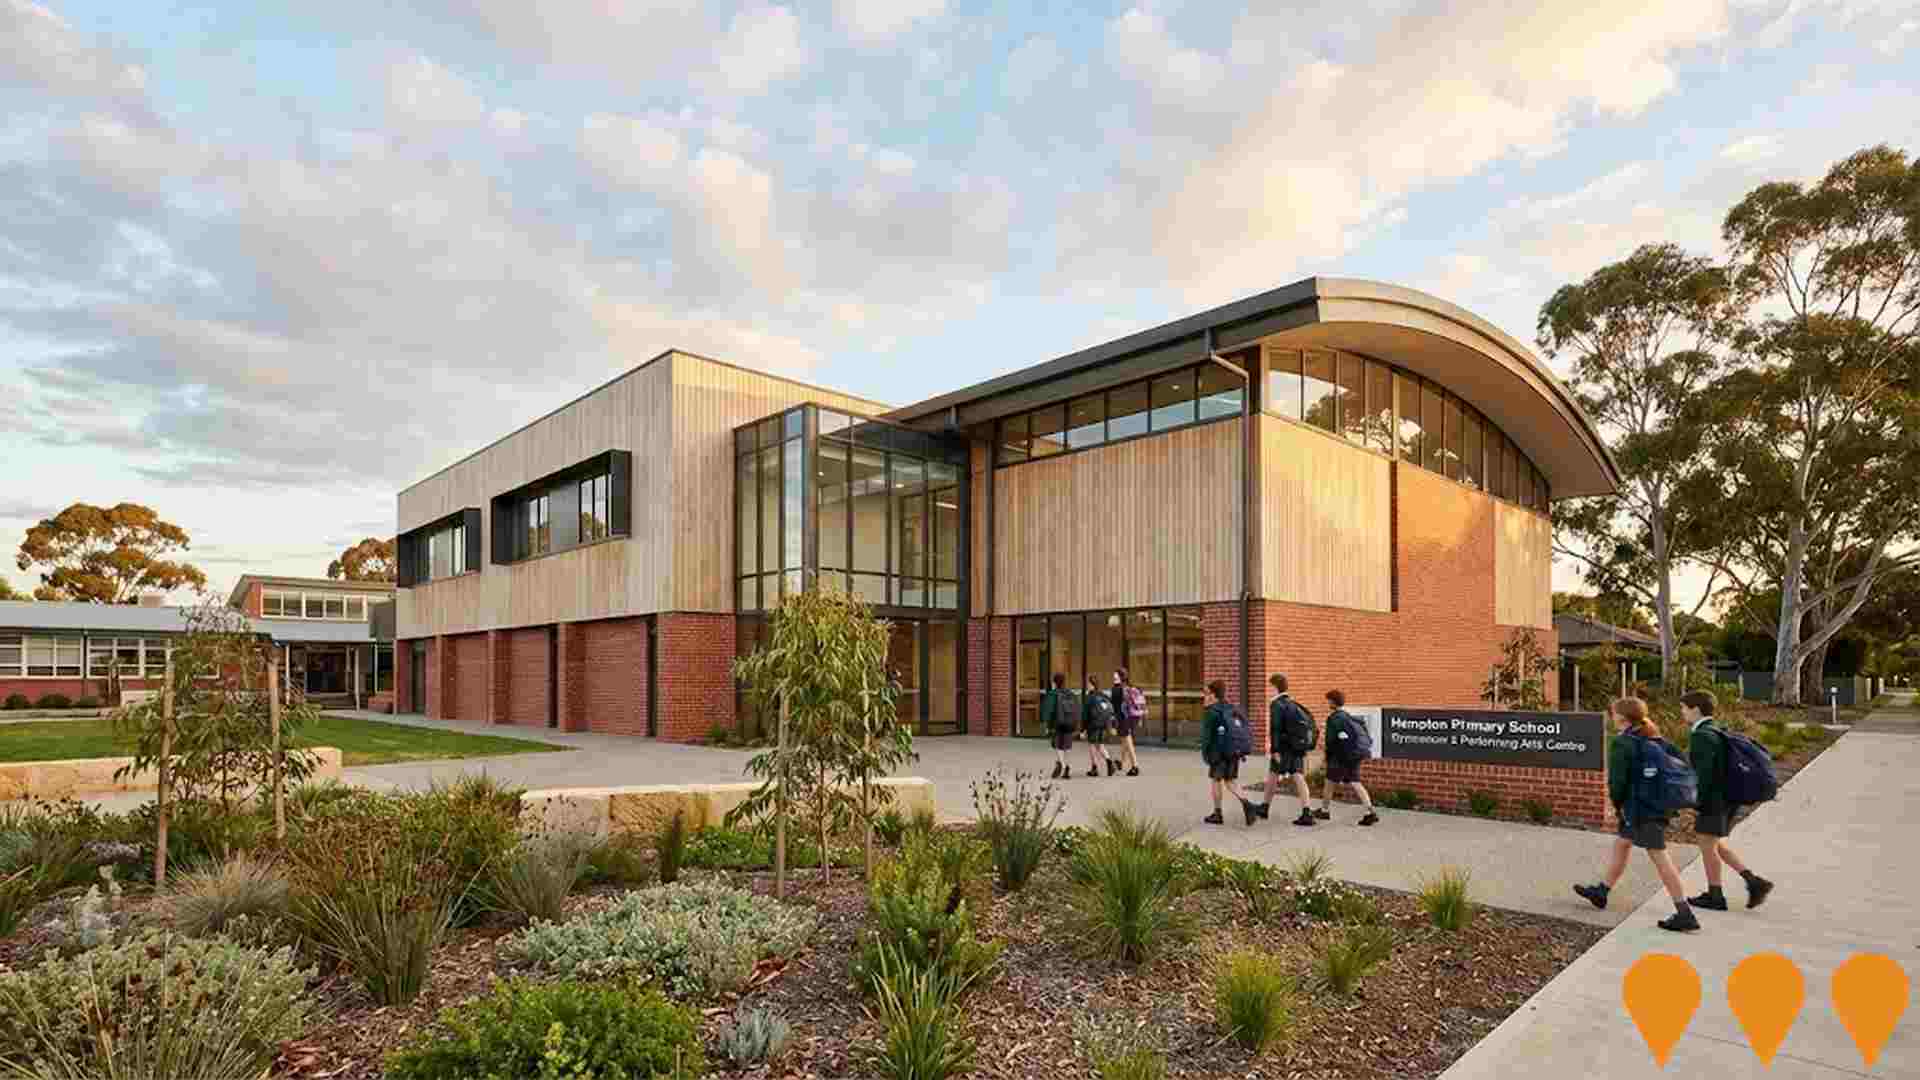
Hampton Primary School Upgrade and Modernisation
Victorian School Building Authority upgrade comprising a new gymnasium, performing arts centre, additional classrooms, relocation of an existing modular building and associated site works to modernise Hampton Primary School. Construction is underway with completion forecast for Q2 2027. Total project funding announced is AUD 9.8 million including earlier planning funding.
9,240 residents of Brighton East are employed, from a labour force of 9,536. Unemployment sits at 3.1%, with participation at 64.1%. Weighted for its industry mix, the area's sectors are forecast to grow about 7.1% nationally over five years. That reflects industry composition only and makes no allowance for local population growth. The working-day population is estimated at 14,966, about 84% of the resident population, so more people leave the area for work than travel in. Unemployment and labour force come from ABS Small Area Labour Markets, updated quarterly; the industry and occupation profile is from the 2021 Census.
Detail
The local labour market is characterized by substantial educational attainment, an established professional services footprint, a low unemployment rate of 3.1%, and steady employment conditions over the preceding twelve months according to aggregated statistical indicators. As of March 2026, 9,240 residents are actively working, with the jobless rate tracking 1.7% lower than the 4.8% seen across Greater Melbourne. However, local labour force engagement sits at 64.1%, falling notably behind the metropolitan benchmark of 70.1%. At the time of the Census, 49.1% of workers indicated working remotely, although pandemic-related restrictions during that period must be noted.
Resident employment is primarily concentrated across professional & technical services, health care & social assistance, and retail trade. Specialisation is particularly pronounced in professional & technical services, where the local representation reaches 1.5 times the metropolitan standard. Conversely, transport, postal & warehousing represents just 2.4% of resident jobs, below the 5.2% recorded across Greater Melbourne. Comparing Census workplace data against resident counts reveals limited employment opportunities within this predominantly residential district. Analysis of combined SALM and ABS statistical releases shows that during the 12 months leading to March 2026, the local labour force contracted by 0.4% as resident employment fell by 0.3%, holding the overall jobless rate virtually steady. In contrast, Greater Melbourne registered a 2.1% increase in employment alongside a 2.3% labour pool expansion and a 0.2 percentage points rise in unemployment. Looking to long-term trends, national forecasts released by Jobs and Skills Australia in Mar-26 provide context for local employment prospects over five- and ten-year horizons. Across the country, total employment is projected to rise by 6.6% across five years and 13.7% over ten years, with sectoral outcomes varying widely. Applying these industry growth profiles to the local occupational baseline suggests resident employment could expand by 7.1% over five years and 14.3% over ten years (representing an unadjusted weighted extrapolation for illustrative purposes that excludes localised demographic modeling).
Frequently Asked Questions - Employment
Median household income in Brighton East is $2,544 a week (about $132,000 a year), with median personal income at $1,036 a week. ATO records put median taxable income at $63,051 a year against an average of $109,274. The average runs 73% above the median, a wider spread than most areas and a sign of a concentrated group of high earners. Household income is from the 2021 Census; taxable income is from ATO Taxation Statistics for the latest financial year available, indexed forward using the ABS Wage Price Index.
Detail
ATO postcode taxation statistics for financial year 2023 place individual earnings in the suburb of Brighton East among the highest percentiles across Australia, featuring a median income of $63,051 and an average of $109,274. These figures comfortably outpace the Greater Melbourne benchmarks of $57,688 (median) and $75,164 (average). Accounting for a 9.62% increase in the Wage Price Index since financial year 2023, updated figures reach approximately $69,117 for the median and $119,786 for the average as of March 2026. The 2021 Census confirmed high earning power, with personal, family, and household incomes sitting within the 81st to 91st percentiles nationally.
Some 33.8% of individuals (6,002 individuals) receive upwards of $4000+, diverging from the broader metropolitan pattern where 32.8% sit in the $1,500 - 2,999 bracket. Robust financial conditions are further highlighted by 44.9% of households generating over $3,000 per week, reinforcing strong purchasing capacity. Although accommodation costs absorb 15.7% of earnings, solid incomes keep disposable income at the 90th percentile, placing the district within the 9th decile on the SEIFA income scale.
Frequently Asked Questions - Income
Brighton East had 6,009 occupied dwellings at the 2021 Census, 68% detached houses and 8% apartments. 36% are owned with a mortgage, 21% rented and 43% owned outright. At that Census the median rent was $600 a week and the median mortgage repayment $3,300 a month, a total housing cost higher than 92% of areas nationally. Rent absorbs 23.6% of household income here and mortgage repayments 29.9%. Dwelling stock, tenure and housing costs are 2021 Census measures — the only source that counts dwellings at this boundary size.
Detail
At the latest Census, the local housing landscape was divided between 67.9% standalone houses and 32.1% other dwellings such as apartments and semi-detached units, mirroring the wider Melbourne metro breakdown of 67.9% houses and 32.1% other dwellings. Outright homeownership was substantially higher locally at 43.2% compared to the metropolitan norm, while 36.3% of homes carried a mortgage and 20.5% were occupied by renters. Monthly mortgage commitments averaged a median of $3,300, well above the Melbourne metro figure of $2,000 and the Australian standard of $1,863. Similarly, median weekly rental costs stood at $600, outstripping both the metropolitan level of $390 and the national benchmark of $375.
Frequently Asked Questions - Housing
Brighton East counted 6,009 households at the 2021 Census, an estimated 6,368 today, averaging 2.6 people each. 40% are couples with children, more than in 79% of areas nationally, against 24% couples without children. 24% of households are people living alone, and families average 1.6 children. Household and family composition is measured only by the Census, so these are 2021 figures.
Detail
Family arrangements represent the predominant living structure, accounting for 74.0% of households, consisting of couples with children (39.8%), couples without children (23.8%), and single parent families (9.8%). Non-family living situations account for the other 26.0%, driven mainly by lone person residences (24.1%) along with group living arrangements (1.9%). The median household size stands at 2.6 people, aligning precisely with the Greater Melbourne standard.
Frequently Asked Questions - Households
49.2% of adults in Brighton East hold a university qualification, including 32.6% with a bachelor degree and 12.1% with postgraduate qualifications, higher than 99% of areas nationally. A further 9.6% hold a vocational qualification. 8 schools serve the area, with 3,477 enrolment places and an average ICSEA of 1,152 against a national benchmark of 1,000. Qualifications come from the 2021 Census; school enrolments, ICSEA and results come from ACARA's current release.
Detail
Tertiary qualification levels in the local area far exceed broader averages, with 49.2% of persons aged 15+ possessing a higher education degree, compared against 33.4% statewide in VIC and 30.4% across Australia. This concentration of advanced learning provides a solid foundation for knowledge-intensive sectors. Bachelor degree holders constitute the largest cohort at 32.6%, followed by postgraduate qualifications at 12.1% and graduate diplomas at 4.5%. Furthermore, vocational education accounts for 20.7% of credentials among individuals aged 15+, divided between advanced diplomas (11.1%) and certificates (9.6%). A high rate of academic engagement is evident locally, with 32.1% of the resident population actively participating in education.
This proportion comprises 10.5% attending secondary schools, 10.3% in primary education, and 6.5% enrolled in tertiary institutions.
Frequently Asked Questions - Education
Schools Detail
Public transport in Brighton East reaches 61 stops on 10 routes, timetabled for about 4,300 services a week. The typical home sits about 200 m from its nearest stop. Buses carry the largest share of public transport commuters. Households keep an average of 1.4 vehicles. Stop and service counts are built from operators' published GTFS timetables and refresh with each timetable release; vehicle ownership is from the 2021 Census.
Detail
Local public transport infrastructure includes 61 operating boarding points across the suburb, incorporating a combination of lightrail and bus networks. These facilities are connected by 10 separate transit lines that provide a collective 4,310 passenger journeys each week. Overall transit connectivity is strong, with typical walking distances to the nearest stop measuring 201 meters. Reflecting the area's residential role, outward journeys dominate, with passenger vehicles making up 86% of travel and rail transit accounting for 6%. Household car ownership averages 1.4 vehicles per dwelling. Meanwhile, 49.1% of resident workers reported working remotely during the 2021 Census, a figure potentially influenced by COVID-19 settings.
Transit services maintain a collective operating volume of 615 trips per day across the network, translating to an average of approximately 70 departures per week for each transit stop.
Frequently Asked Questions - Transport
Transport Stops Detail
71.7% of residents in Brighton East report no long-term health condition. 6.1% need daily assistance with core activities, and 69.8% hold private health cover. The standardised death rate runs at 4.7 per 1,000 residents. Health conditions, assistance needs and insurance are 2021 Census measures; the death rate comes from current ABS releases.
Detail
Evaluations of local public health indicators by AreaSearch show favorable health outcomes, with general mortality and chronic illness rates remaining subdued across the broad community, despite elevated prevalence within older cohorts. Private medical coverage is exceptionally common, encompassing approximately 70% of all residents (12,395 people), well above the Greater Melbourne benchmark of 56.7% and the nationwide proportion of 55.7%. Arthritis and mental health conditions represent the most frequently reported ailments, recorded among 7.6 and 6.4% of the population, respectively, while 71.7% of residents reported having no long-term medical conditions, comparable to 72.6% across Greater Melbourne.
The working-age population maintains solid health with minimal chronic issues. Individuals aged 65 and over constitute 21.7% of the locality (3,853 people), exceeding the Greater Melbourne share of 15.1%, though positioning lower against broader national cohorts.
Frequently Asked Questions - Health
30.7% of Brighton East residents were born overseas and 21.6% speak a language other than English at home. The largest reported ancestries are English (23.4%) and Australian (20.1%). Ancestry, language and country of birth are counted only by the Census, so these are 2021 figures.
Detail
The local population displays greater cultural diversity than most comparable suburban settings, with 30.7% of residents born abroad and 21.6% utilizing a non-English language in their domestic environment. Christianity is the leading religious affiliation, observed by 45.2% of people in the community. Judaism exhibits a distinct local concentration at 9.7% of residents, markedly higher than the 1.0% recorded across Greater Melbourne. Examining parental countries of birth reveals English (23.4%), Australian (20.1%), and Other (10.9%) as the top three ancestral backgrounds within the community. Distinct overrepresentations are also evident among specific communities, with Polish heritage accounting for 2.5% locally compared to 0.8% across the wider region, Russian ancestry at 1.6% versus 0.4%, and Hungarian background at 0.5% against 0.3%.
Frequently Asked Questions - Diversity
The median resident of Brighton East is 45, older than 80% of areas nationally. 23.0% of residents are aged 15 to 34. Age cohorts are not raw Census counts: the Census split is re-based to the latest ABS population estimates and state projections.
Detail
The local demographic structure skews older than the broader metropolitan standard. Updated figures to August 2026 indicate that senior and retired groups (65+) comprise 21.7% of the population, compared to 15.1% across Greater Melbourne, whereas young to middle-aged adults (25 - 44) account for 18.4% versus 32.1% regionally. The estimated median age reaches 45 as at August 2026, remaining unchanged from the 2021 Census level and sitting 8 years above the Greater Melbourne median of 37 at that Census, as well as exceeding the national median of 38 recorded at that time.
Projections to 2041 indicate that elderly and retiree demographics will capture the majority of local growth, expanding by 1,322 residents (34%) to a total of 5,175.
Frequently Asked Questions - Age
Data & MethodBoundaries, Sources & Method for Brighton East
9 of 14 data sections on this page were updated within the last 12 months — the newest current to Oct 2026.
Everything is aggregated to the Suburb (SAL) boundary shown above, on a 2021 Census baseline. Only 3 sections — housing, households and cultural diversity — still wait on the 2026 Census.
The ledger — source, cycle and currency by section
| Section | Source & update cycle | Currency |
|---|---|---|
| Updated within the last 12 months 9 sections | ||
| Population | ABS, GNAF, Geoscience Australia Annual (ABS ERP) | Aug 2026 2 months ago headline measures · 2021 Census baseline |
| Re-based to the ABS Estimated Resident Population (June 2025 release) and updated with new dwellings from GNAF address data. Current to Aug 2026, with the 2021 Census supplying the small-area baseline. | ||
| Age profile | ABS, Geoscience Australia, State governments Annual | Aug 2026 2 months ago headline measures · 2021 Census baseline |
| Age cohorts are re-based to the latest ABS population estimates and state projections, current to Aug 2026. Each cohort is held as a Census baseline and a current estimate. | ||
| Development & approvals | ABS, GNAF Monthly (ABS approvals) | Aug 2026 2 months ago headline measures · Jul 2026 baseline |
| Property sales & rents | Valuer General, Rental Board, ABS Weekly sales, quarterly rents | Oct 2026 this month headline measures · Sep 2026 baseline |
| Sales from the state Valuer General register, refreshed weekly, and rents from quarterly rental bond lodgements. Both are read live each time this page loads, current to Oct 2026. | ||
| Infrastructure projects | Infrastructure Australia, State agencies, Local governments Daily | Nov 2025 11 months ago all 11 projects tracked here |
| Project pipeline maintained continuously from Infrastructure Australia, state agencies, local government and public announcements. Records are added and revised daily; this area was last updated Nov 2025. | ||
| Employment | ABS, DEWR, JSA Quarterly (ABS SALM) | Mar 2026 7 months ago headline measures · 2021 Census baseline |
| Unemployment and labour force from ABS Small Area Labour Markets, current to Mar 2026. The growth outlook applies Department of Employment (now Jobs and Skills Australia) forecasts for all 19 industry divisions to the local industry mix, so it measures sector composition rather than local expansion and makes no allowance for population growth. Job demand comes from the same agency via its Internet Vacancy Index; industry and occupation structure from the 2021 Census. | ||
| Education | ABS, ACARA Annual (ACARA) | Sep 2026 last month headline measures · 2021 Census baseline |
| Transport | ABS, State Transport Departments Each timetable release | Jul 2026 3 months ago headline measures · 2021 Census baseline |
| Services & amenities | Provider directories, ACECQA Continuous | Sep 2026 last month all 14 measures |
| Annual and financial-year sources 2 sections | ||
| Income | ABS, ATO Annual (ATO) | FY 2023 3 years ago headline measures · 2021 Census baseline |
| ATO taxable income statistics for FY 2023, indexed forward using the Wage Price Index. Census household income provides the distribution detail. | ||
| Health | ABS, ATO Annual | 2024 2 years ago headline measures · 2021 Census baseline |
| Census-measured — next update: 2026 Census 3 sections No more current small-area source exists for these, so they are labelled as Census-measured rather than implied to be current. | ||
| Housing | ABS 5-yearly (Census) | 2021 Census next update 2026 all 30 measures |
| Households | ABS 5-yearly (Census) | 2021 Census next update 2026 all 18 measures |
| Cultural diversity | ABS, Geoscience Australia 5-yearly (Census) | 2021 Census next update 2026 all 44 measures |
"Currency" is the most recent release feeding that section. Where the Census supplies the structural baseline underneath a current headline figure, the row says so.
How the numbers are built
Population
The Census provides the small-area baseline, aggregated from mesh blocks to this boundary. It is then re-based to the ABS Estimated Resident Population (June 2025 release), and new dwellings built since Census night are counted from address data — 86 validated new addresses here. The headline figure is therefore a current estimate for Aug 2026, not a 2021 count (16,757 at the 2021 Census → 17,758 now). Annual growth rates are compound (CAGR), not simple averages.
Age profile
Cohort shares are not raw Census counts. Every cohort is held as a pair — the Census baseline and a current estimate — and the split is re-based using ERP and state population projections, current to Aug 2026. Median age is the Census median plus modelled change since. Charts that show both are labelled "2021 Census vs Current Estimate".
Property sales
Sourced from the state valuation authority's sales register — current, not Census, and refreshed weekly. Medians are calculated from settled transactions in the period shown; periods with very low transaction counts are flagged or suppressed, because a handful of sales can move a median substantially.
Rents
Derived from state rental bond lodgement data, by dwelling type and bedroom count. Bonds are lodged at the start of a new tenancy, so this reflects new lettings, not the whole rented stock.
Development & infrastructure
Building approvals come from current ABS releases; development applications are collected from council and state planning portals; the infrastructure pipeline is compiled from Infrastructure Australia and local government sources. Applications are matched to this boundary by address or coordinates, so very recent lodgements may not yet appear.
Employment & income
Industry and occupation structure comes from the Census, but the headline labour-market indicators do not. Unemployment and labour force are derived from ABS Small Area Labour Markets (quarterly). The employment outlook applies Department of Employment forecasts for all 19 industry divisions to this area's own industry mix (the agency is now Jobs and Skills Australia), as does the Internet Vacancy Index used for job demand. Because it is weighted on industry composition alone, that outlook carries no allowance for local population growth — in fast-growing areas the real rise in local jobs will typically be higher. Income combines Census household income with ATO taxable-income statistics for FY 2023, indexed forward using the Wage Price Index.
Education, transport & amenities
School enrolments, ICSEA and performance come from ACARA's current release, not the Census. Public transport stops and service frequency are derived from GTFS timetable feeds published by state transport departments. Services and amenities are proximity and count scores built from provider directories, refreshed on their own cycle. The Census contributes only the travel-to-work and qualification measures.
Rankings and benchmarks. Where we rank this area, the comparison set is every area of the same boundary type — suburbs against suburbs, SA2s against SA2s. Benchmarks compare this area against its greater capital city region and the national figure for the same measure and period.
Limits worth knowing. Small areas carry larger error margins, and the ABS introduces small random adjustments to Census counts to protect confidentiality — so totals may not sum exactly. Estimates re-based from regional data describe the area's expected trajectory, not a direct count of it. Figures are indicative for research and are not financial, planning or valuation advice.
Cross-check us. The Census baseline for this boundary is at ABS 2021 Census QuickStats (SAL20338). QuickStats reports 2021 only — the figures on this page are more current wherever the ledger shows a later date.