Chart Color Schemes
This analysis uses ABS Statistical Areas Level 2 (SA2) boundaries, which can materially differ from Suburbs and Localities (SAL) even when sharing similar names.
SA2 boundaries are defined by the Australian Bureau of Statistics and are designed to represent communities for statistical reporting (e.g., census and ERP).
Suburbs and Localities (SAL) represent commonly-used suburb/locality names (postal-style areas) and may use different geographic boundaries. For comprehensive analysis, consider reviewing both boundary types if available.
est. as @ -- *
ABS ERP | -- people | --
2021 Census | -- people


Curious about local property values? Filter the chart to assess the volume and appreciation (including resales) trends and regional comparisons, or scroll to the map below view this information at an individual property level.


Find a Recent Sale

Sales Detail
Brighton East has an estimated 17,542 residents, up from 16,540 at the 2021 Census — a change of 1,002 people, or 6.1%. Growth has averaged 0.6% a year over five years. Overseas migration accounts for 92.9% of that increase. That puts 3,127 residents on each square kilometre. Population is estimated from ABS Estimated Resident Population releases and GNAF address data, re-based from the 2021 Census and updated annually.
Detail
According to AreaSearch data, the population of Brighton East stands at approximately 17,542 as of Aug 2026. This figure represents a rise of 1,002 individuals, or 6.1%, compared to the 2021 Census count of 16,540 people. The adjustment is derived from the Australian Bureau of Statistics' estimated resident population of 17,486 as of June 2025, combined with 80 newly validated addresses recorded after the Census date. With a density of 3,126 persons per square kilometer, the area ranks within the upper quartile when compared to other national locations evaluated by AreaSearch.
The 6.1% increase since the 2021 census surpassed the SA3 regional average of 6.0%, establishing Brighton East as a leading growth area in the region. Overseas migration accounted for roughly 92.9% of the total population gains observed in recent periods. SA2 geographic projections published in 2024 by ABS/Geoscience Australia utilizing 2022 as a base year form the foundation of AreaSearch's demographic models. Where SA2 coverage is absent, AreaSearch draws upon 2023 VIC State Government Regional/LGA projections, applying a weighted aggregation methodology to translate LGA trends down to SA2 boundaries. Age cohort growth rates derived from these aggregations are subsequently integrated across every locality for the 2032 to 2041 period. In terms of future growth trajectories, the locality is projected to experience population expansion above the national median, increasing by 2,482 persons to 2041 according to recent annual ERP data, which equates to a cumulative 13.8% climb across the 16 years.
Frequently Asked Questions - Population
774 new dwellings have been approved in Brighton East over the past five years, an average of 154 a year. That places the area in the 75th percentile for residential development activity nationally, about 9 approvals per 1,000 residents a year. Of the 155 dwellings approved in the latest reporting year, 21% were detached houses and the rest townhouses or apartments. Figures come from ABS building approvals aggregated to this SA2 boundary and are updated monthly as the ABS releases them.
Detail
Dwelling consent figures for Brighton East show a yearly average of approximately 154 approvals, culminating in 774 residential units approved across the last 5 financial years (between FY-22 and FY-26). Because additions have tracked at an average of only 0.6 new residents per year per dwelling constructed over the past 5 financial years (between FY-22 and FY-26), supply is keeping pace with or exceeding local demand, expanding consumer choice and creating capacity for demographic growth beyond baseline projections. Concurrently, approved residential projects average an expected building cost of $692,000, illustrating an emphasis among developers on upmarket, premium construction.
Alongside this, $6.1 million in commercial building approvals was documented during the present financial year, reinforcing the suburb's predominantly residential character. Per capita construction activity in Brighton East closely mirrors that of Greater Melbourne, preserving an equilibrium in line with the surrounding metropolitan market. Recent residential building permits are divided between 21.0% standalone houses and 79.0% medium-to-high-density apartments or townhouses. This pivot toward higher-density building provides attainable entry points for first-home purchasers, downsizers, and property investors alike. It also marks a distinct departure from the prevailing housing stock (which currently consists of 71.0% detached homes), underscoring a scarcity of greenfield sites as well as growing appetite for varied, cost-effective residential options. With approximately 125 people per dwelling approval, the neighborhood continues to exhibit low-density structural qualities. Demographic projections indicate that Brighton East will add 2,426 residents through to 2041 based on the most recent AreaSearch quarterly estimate. Ongoing construction activity indicates that incoming residential stock should easily accommodate this influx, generating favorable buying conditions while establishing the infrastructure needed to accommodate gains exceeding existing population forecasts.
Frequently Asked Questions - Development
Development applications around Brighton East
SOURCE: Planning portals and council registers, compiled by AreaSearch. Distance & bearing measured from the suburb midpoint.
AreaSearch tracks 6 current infrastructure and development projects inside Brighton East, worth an estimated $142 million. A further 194 sit in the immediately surrounding suburbs, taking the tracked pipeline within reach of the area to $19.7 billion. 49 are already under construction and 71 are due for completion within three years. The pipeline spans residential development, communities, precincts & urban renewal and communities. Records are compiled from Infrastructure Australia, state agencies, council planning portals and public announcements, reviewed and updated daily, then ranked by proximity, construction stage, completion horizon and project scale.
Detail
Capital works, major planning frameworks, and infrastructure investments play a defining role in shaping local urban outcomes. AreaSearch has pinpointed 42 individual initiatives anticipated to influence the immediate area. Notable developments include the Bayside Gallery Building Works, 111 Carpenter Brighton Townhomes, 24 Burrows Street Brighton, and the Ormond Station Development (Ormond Place), with subsequent records itemizing those carrying the greatest local importance.
Professional plan users can use the search below to filter and access additional projects.
INFRASTRUCTURE SEARCH
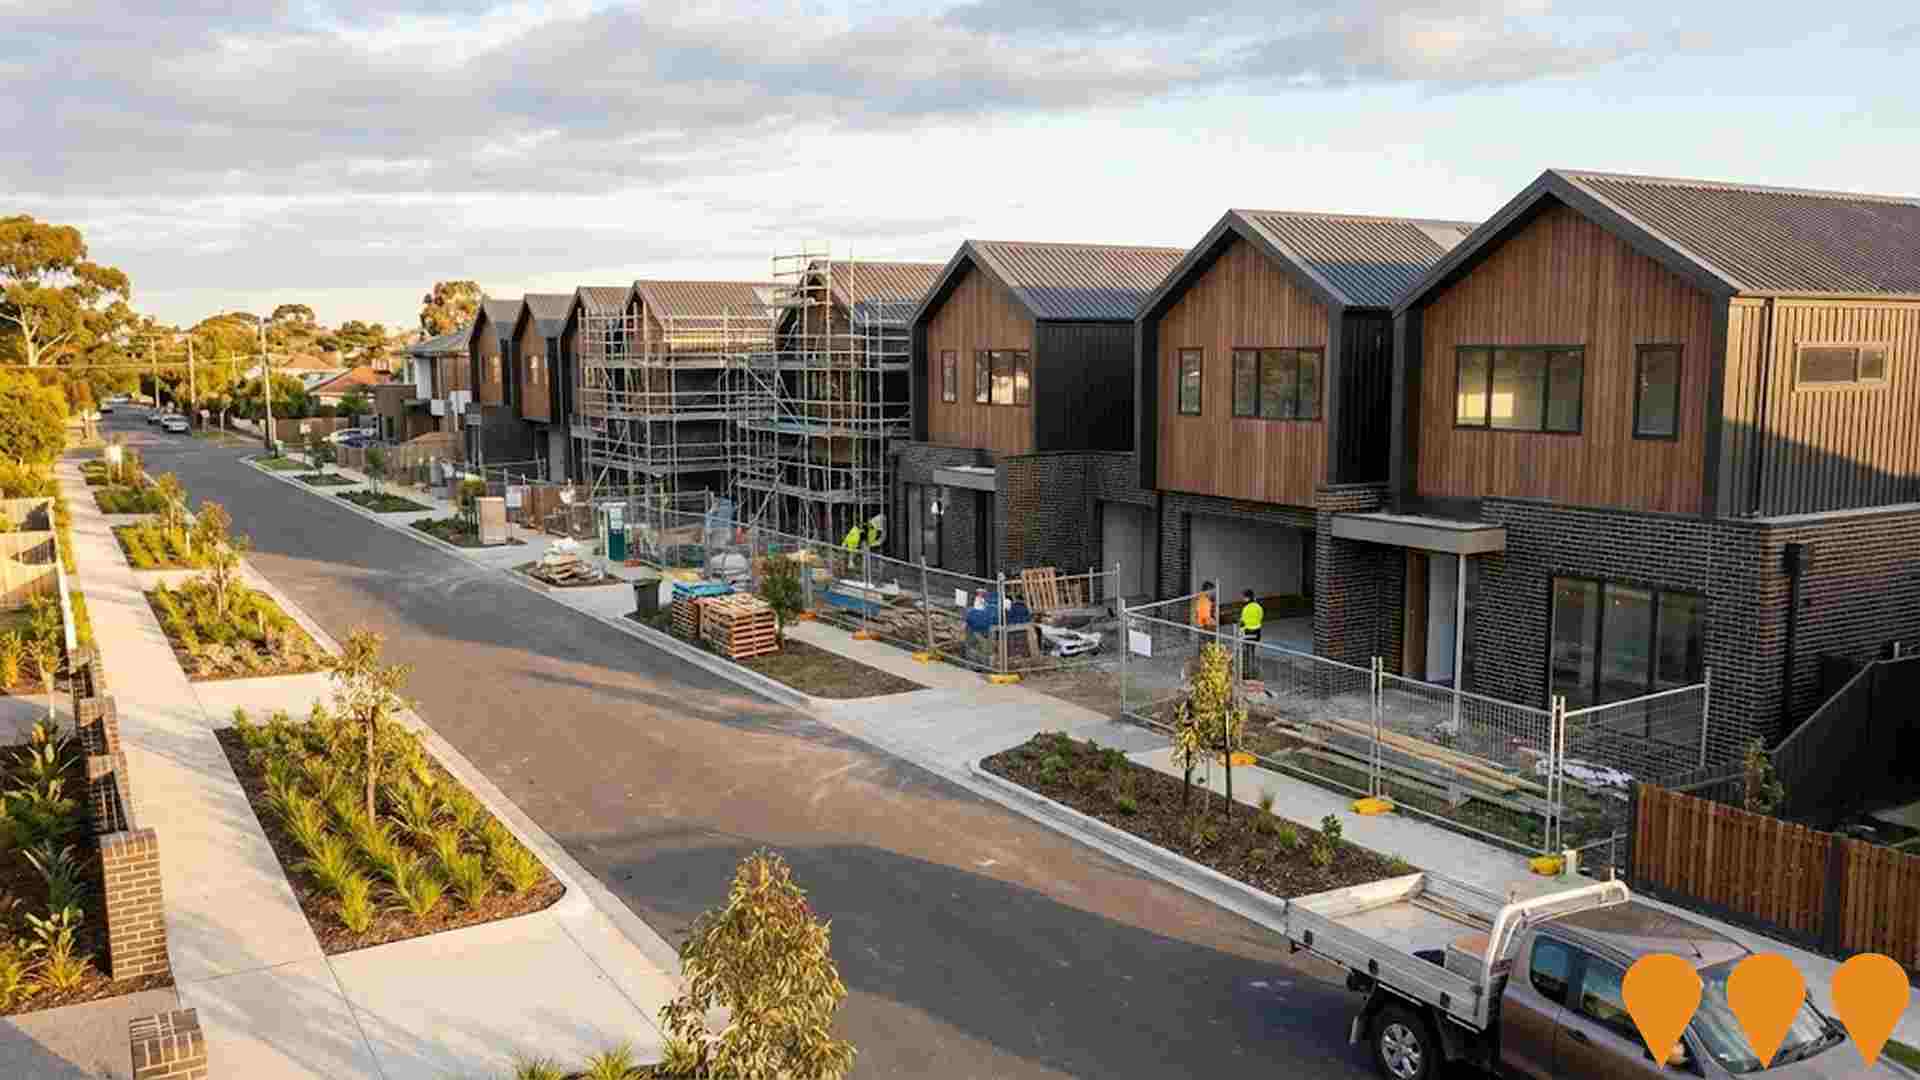
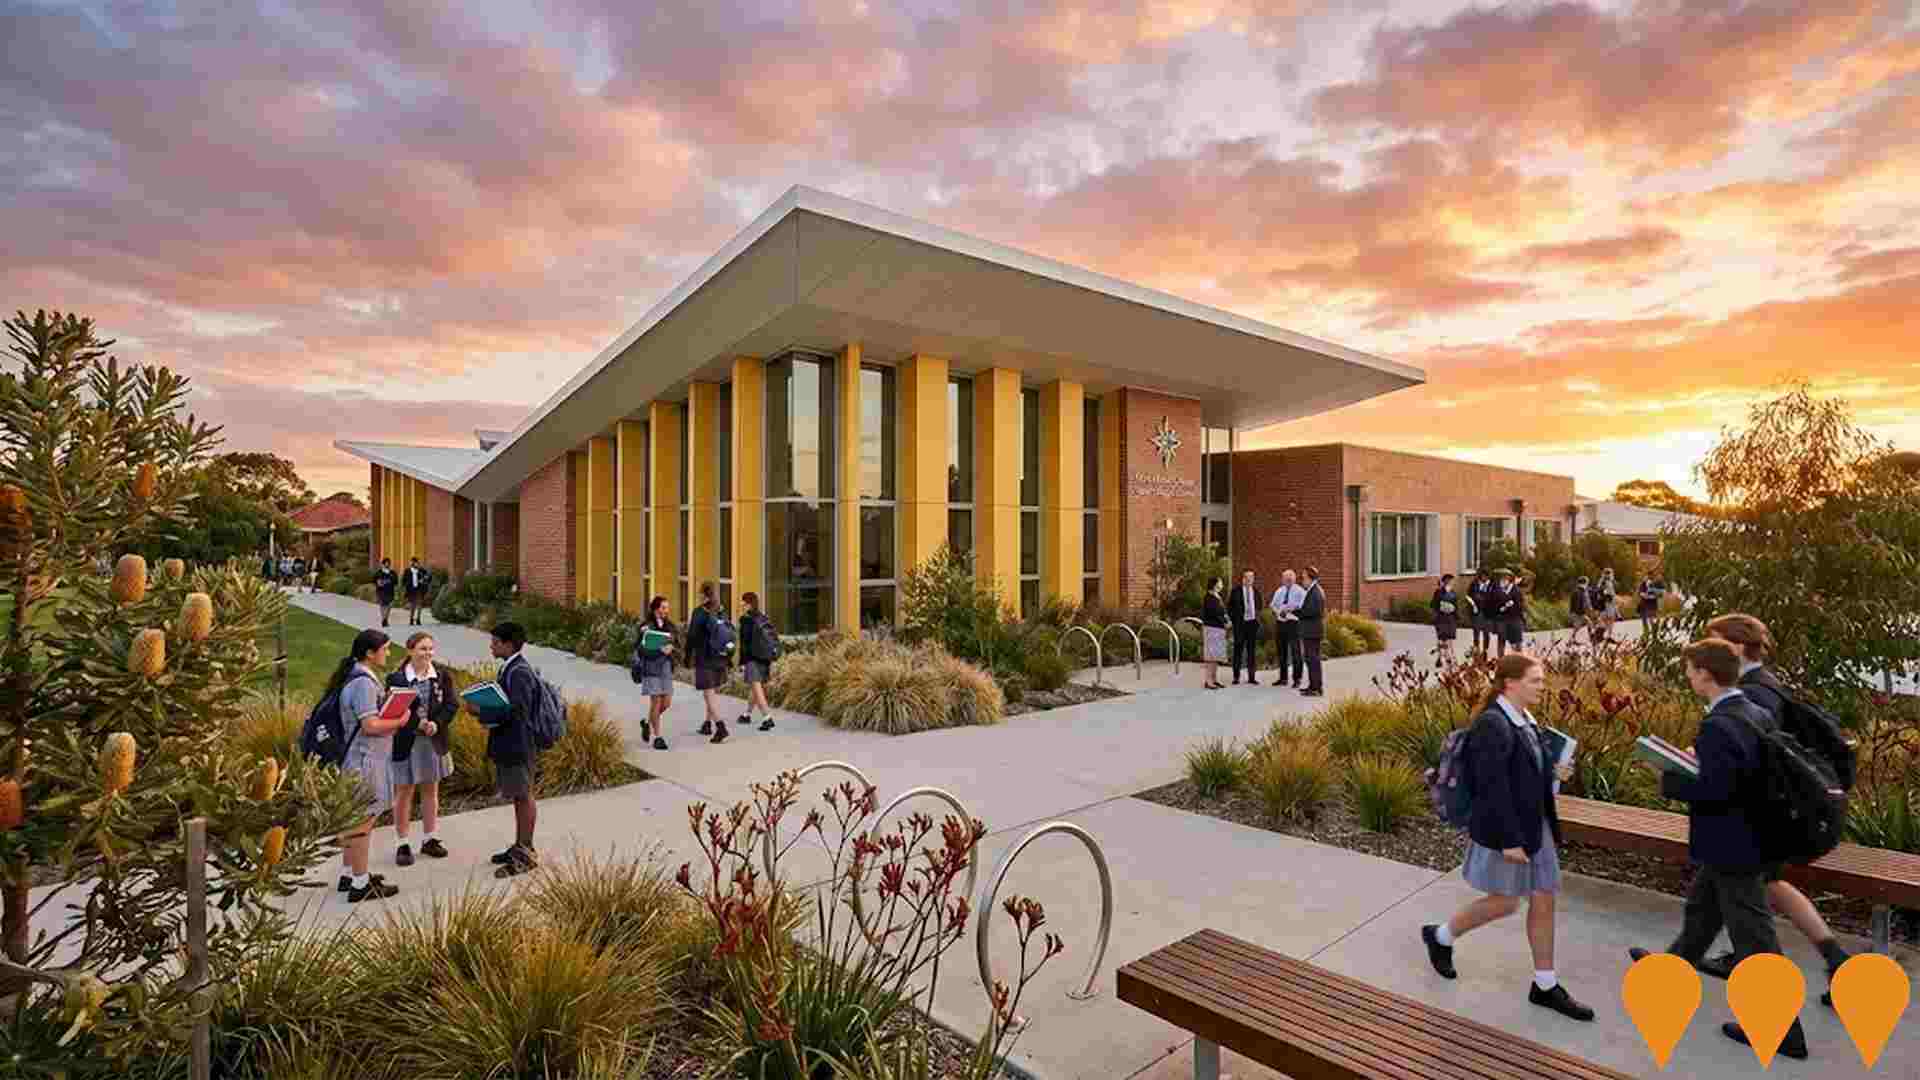
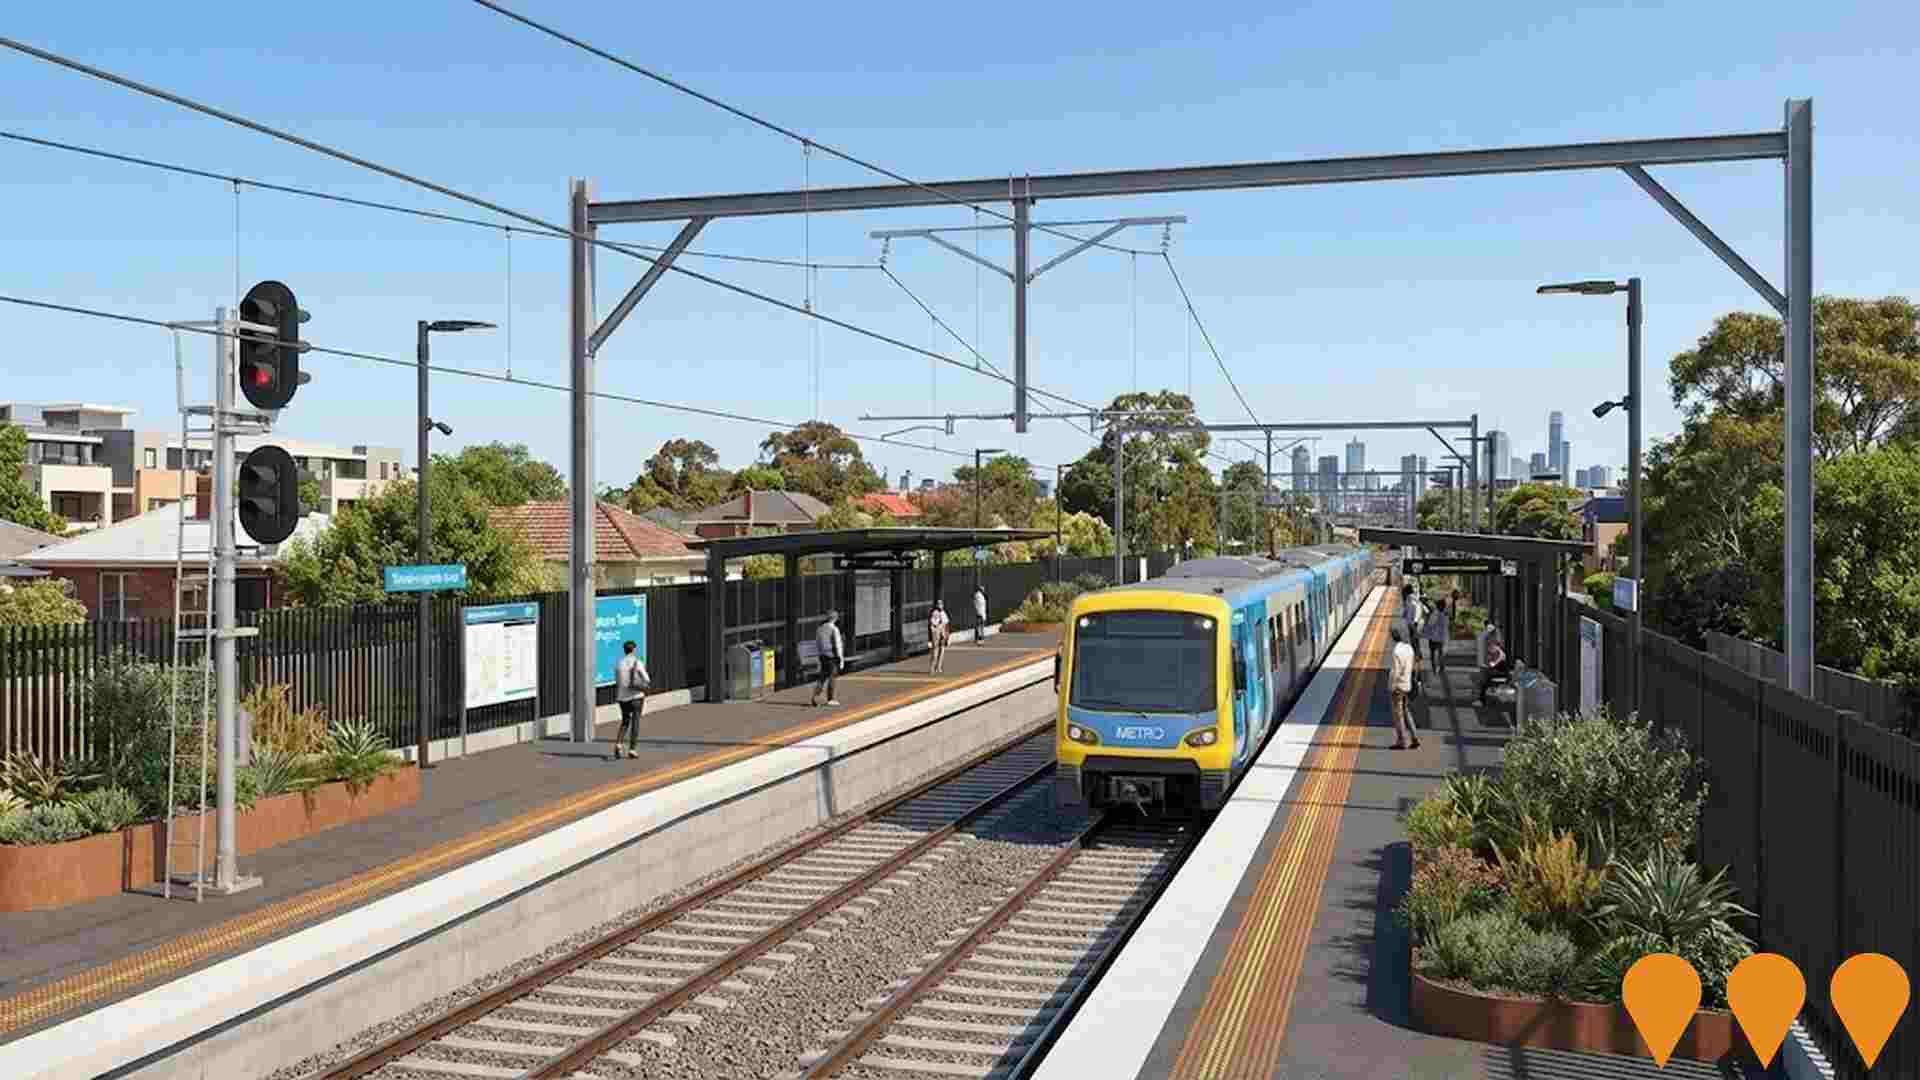
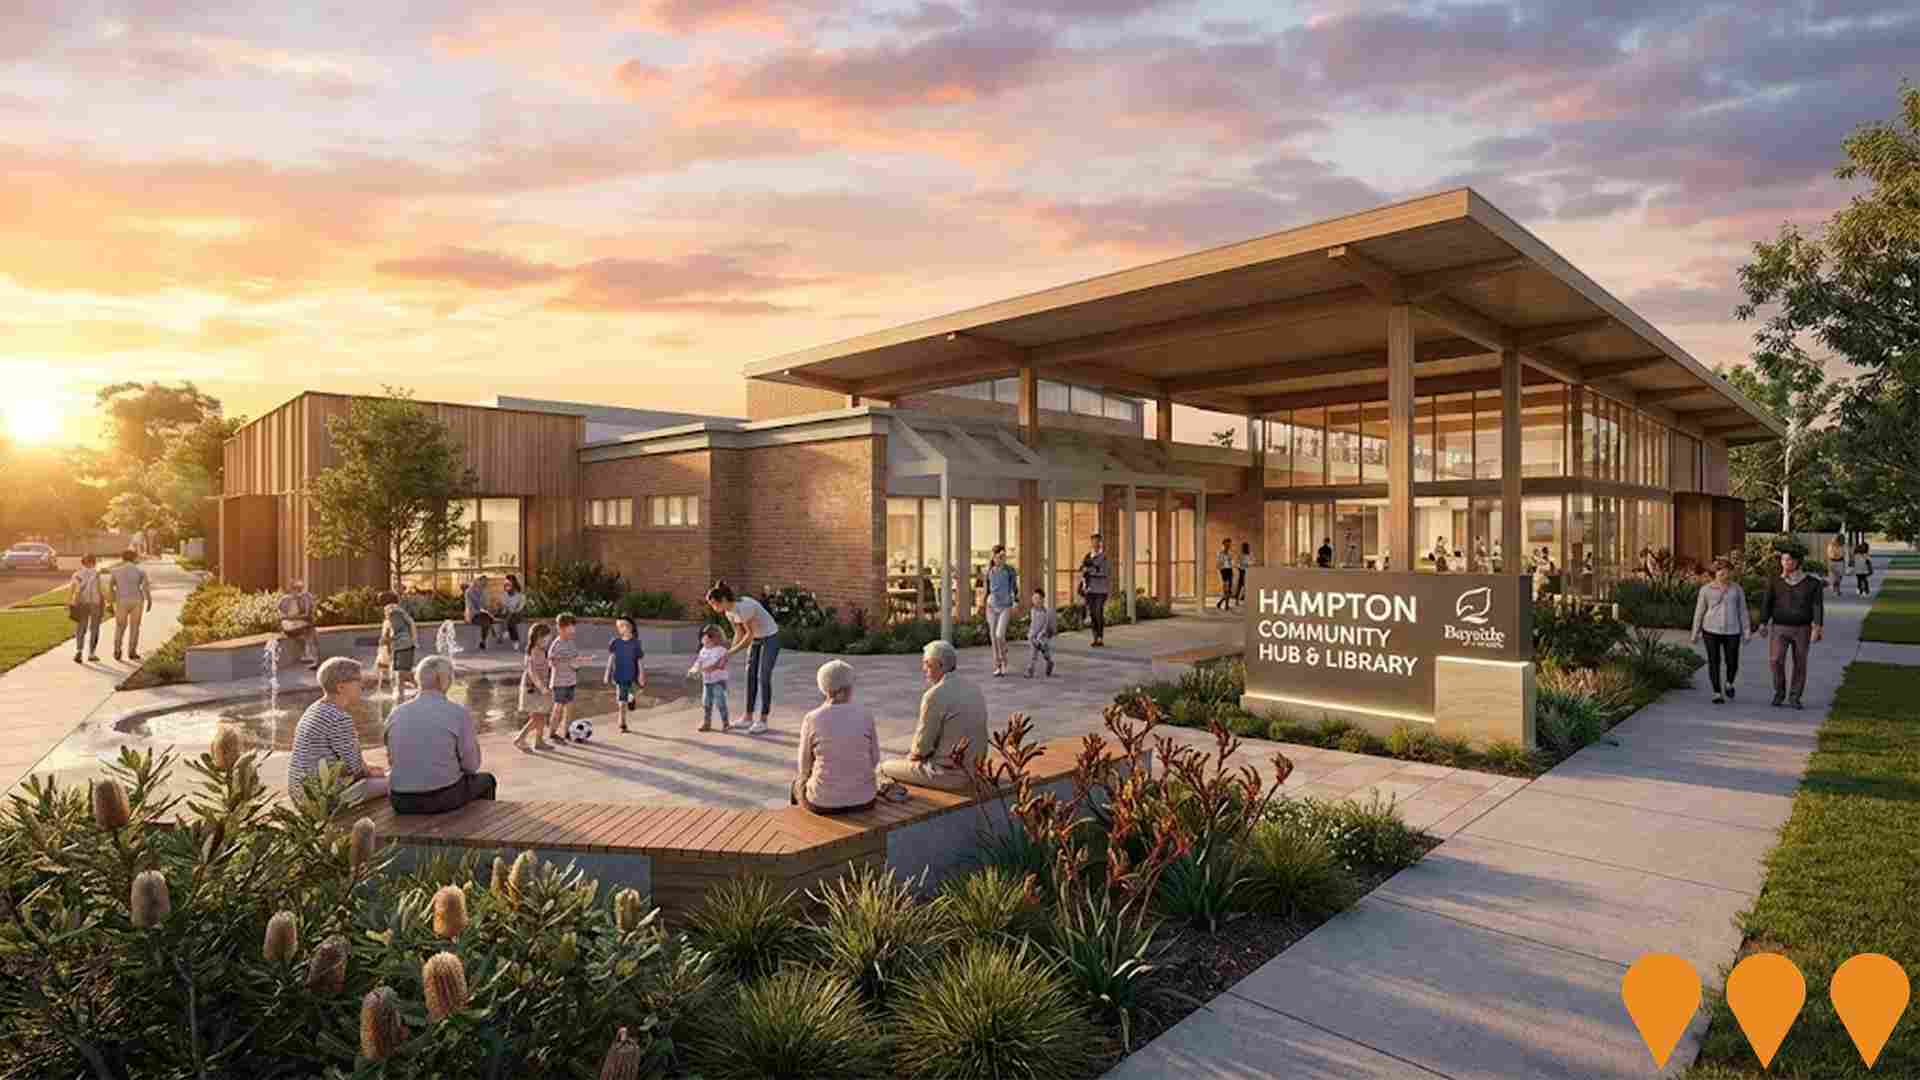
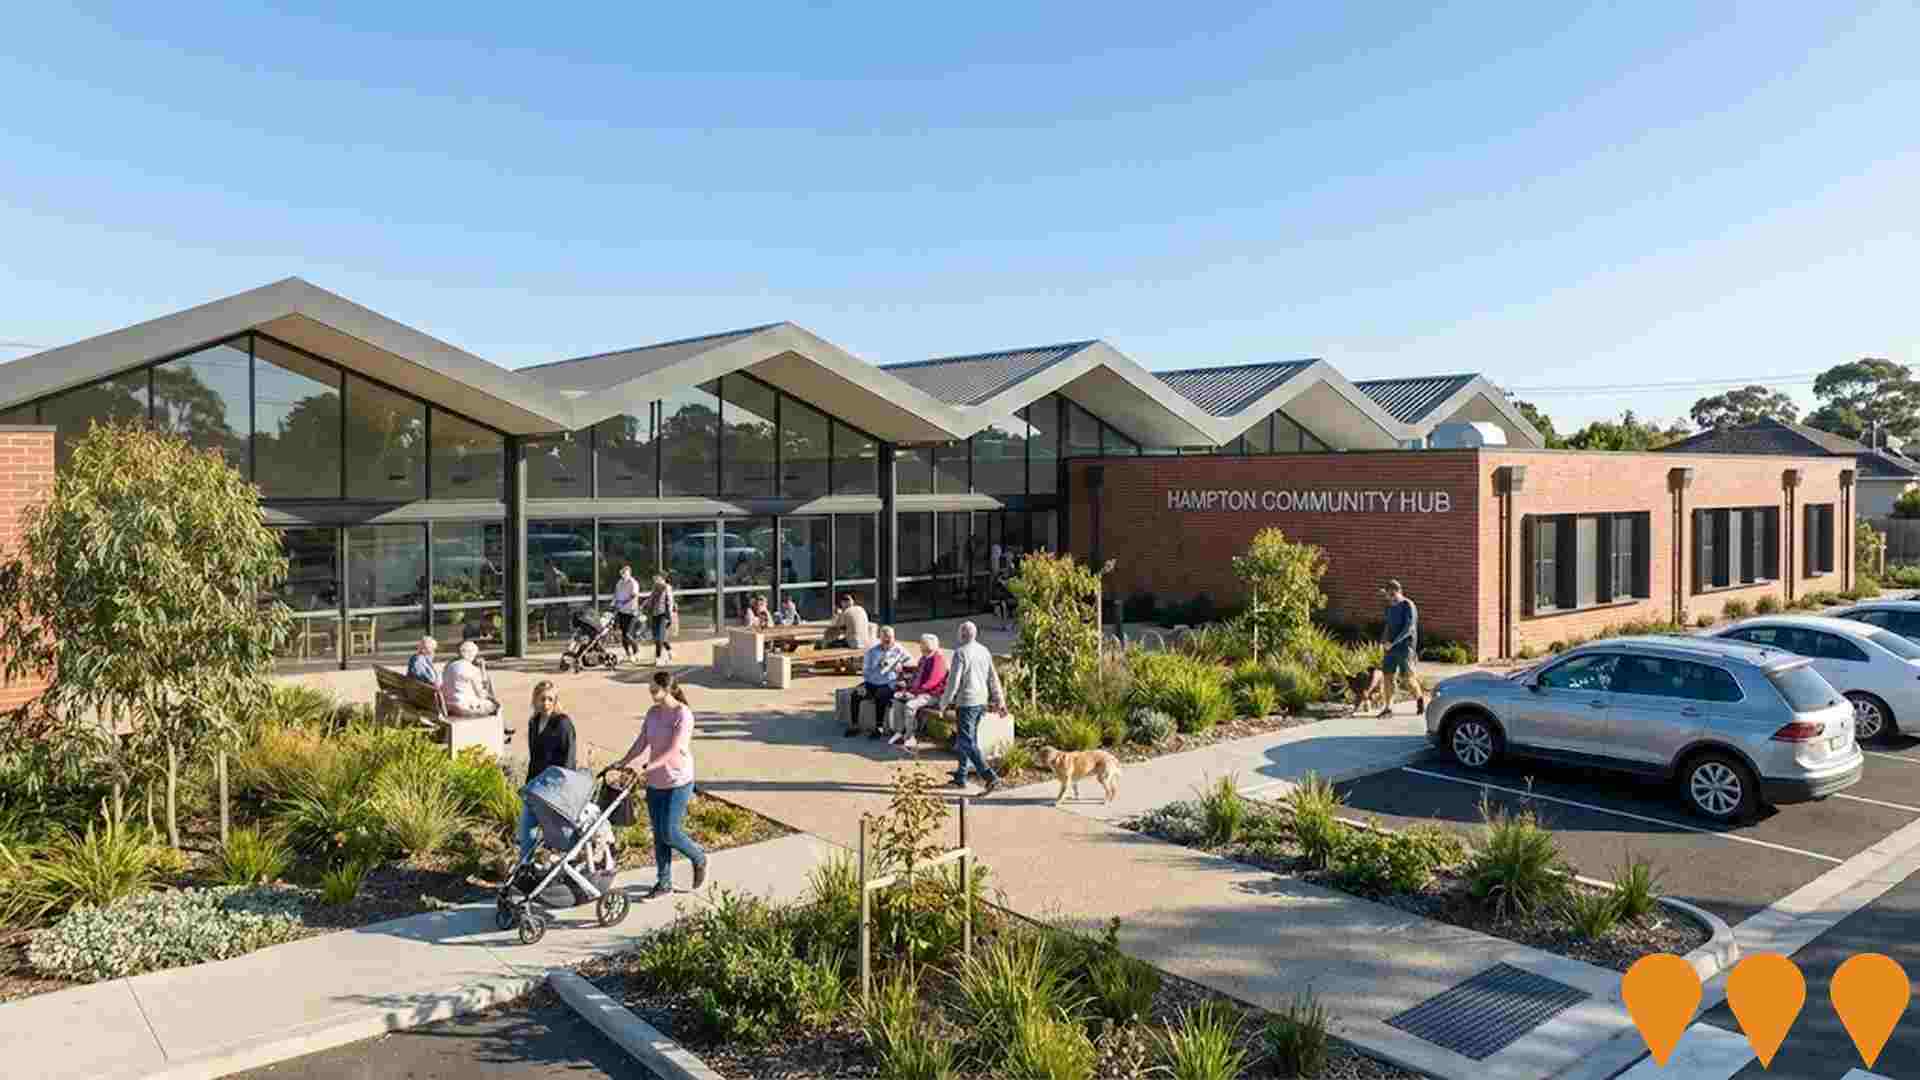
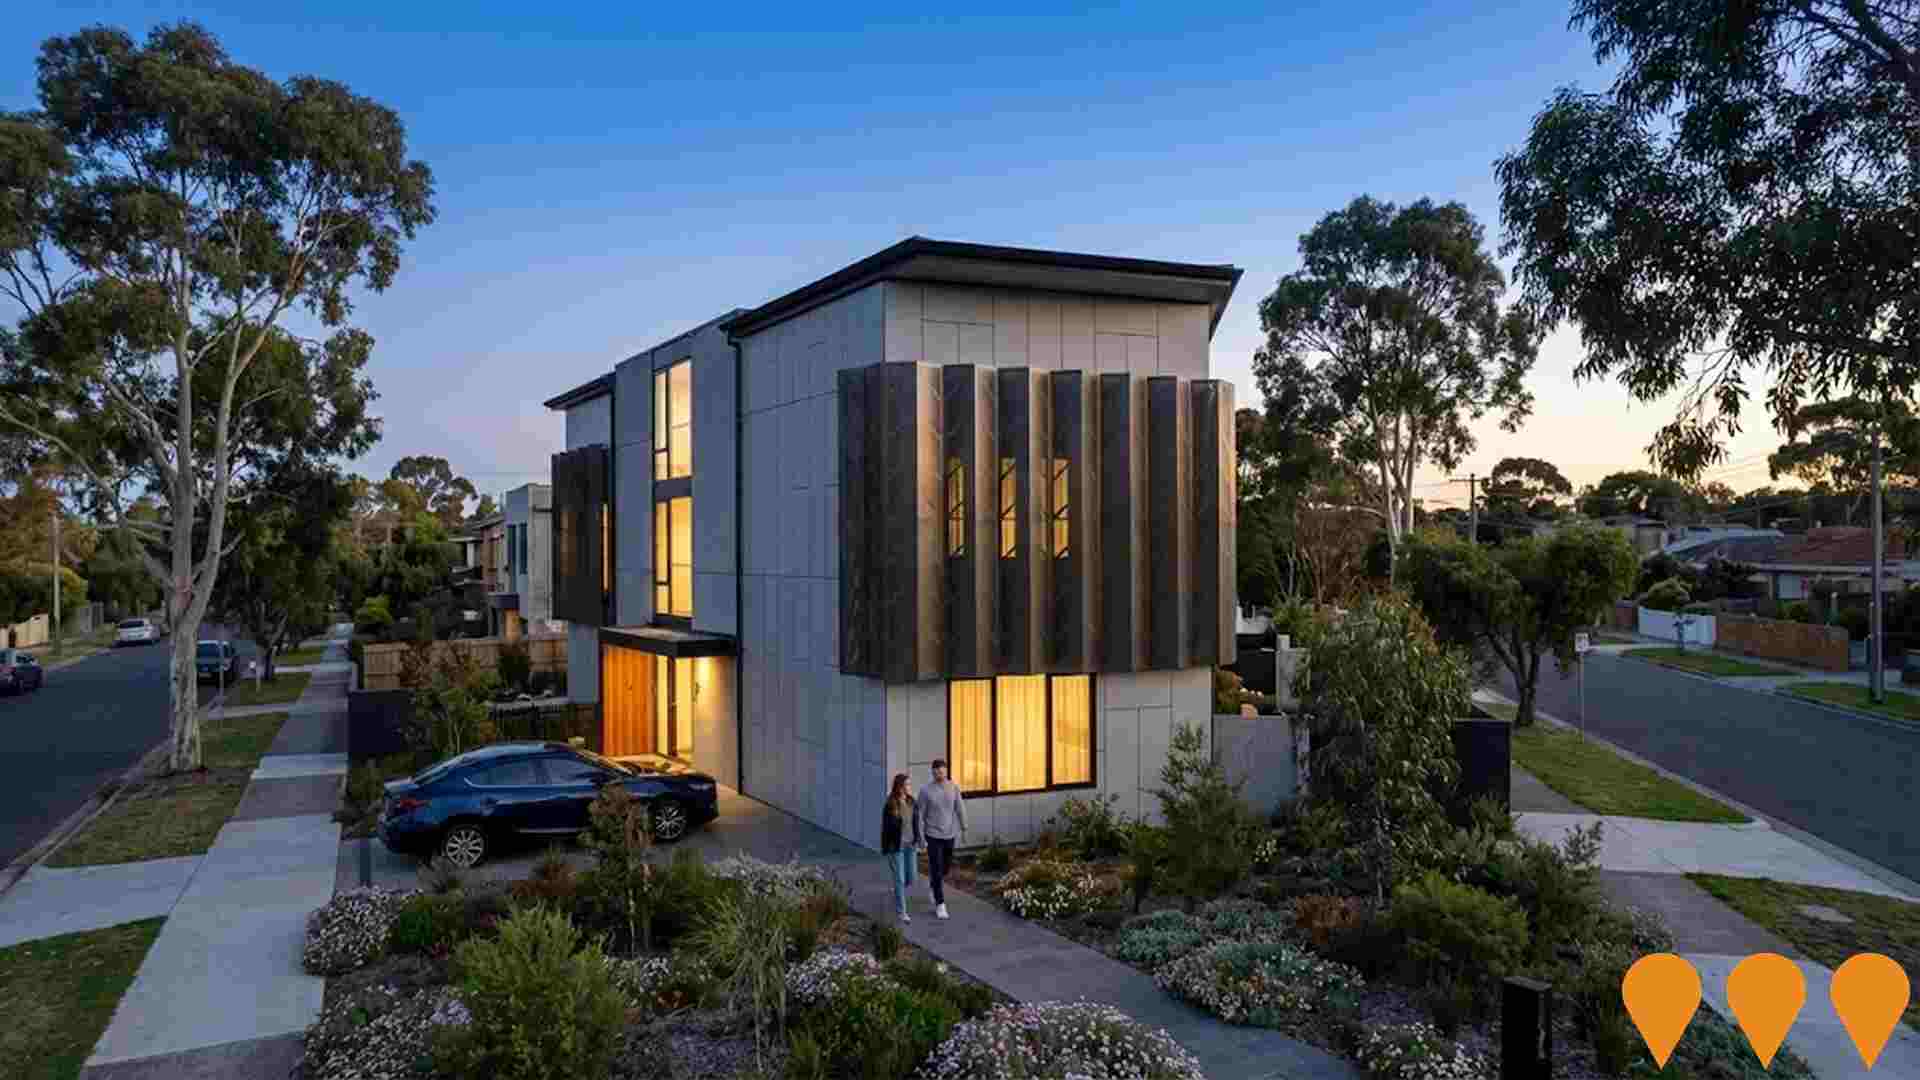
 Denotes AI-based impression for illustrative purposes only, not to be taken as definitive under any circumstances. Please follow links and conduct other investigations from the project's source for actual imagery. Developers and project owners wishing us to use original imagery please Contact Us and we will do so.
Frequently Asked Questions - Infrastructure
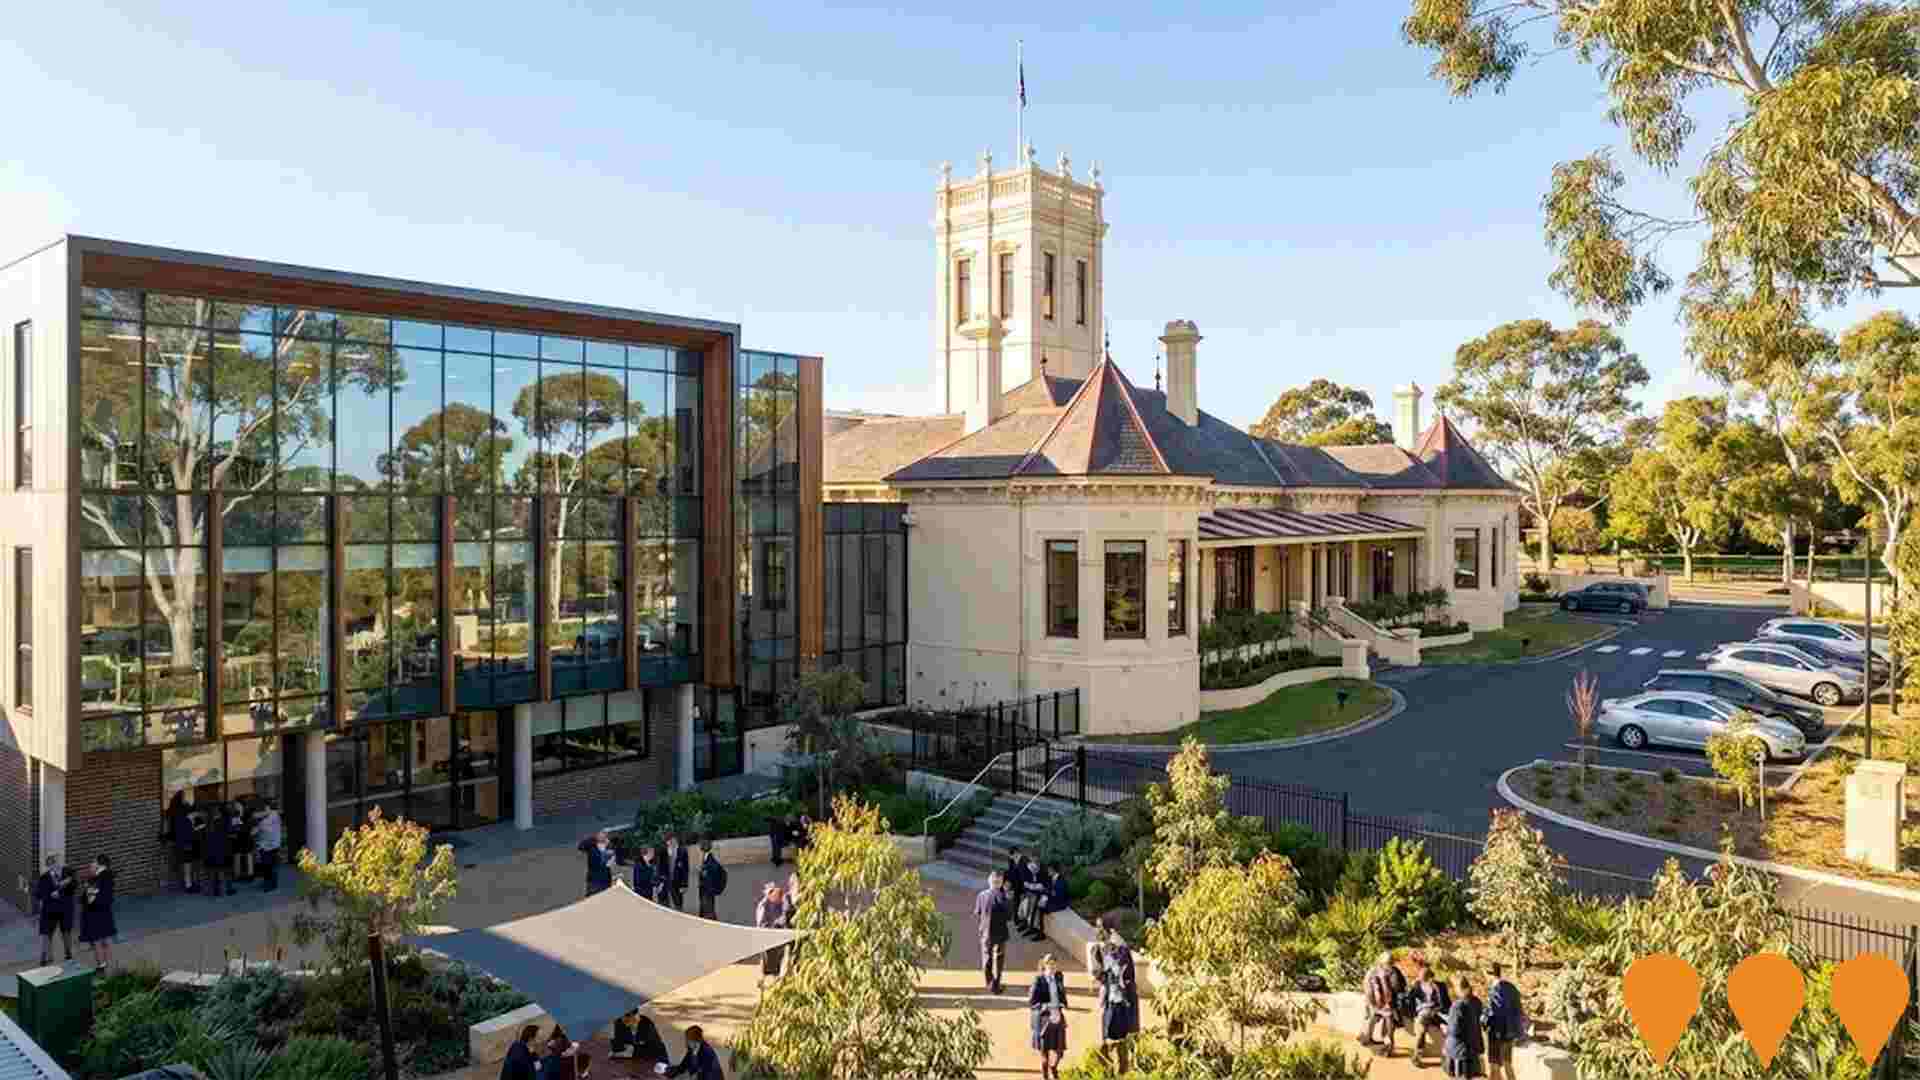
St Leonards College Expansion
Expansion of St Leonards College through the adaptive reuse of adjacent properties as an Education Centre, providing additional administration and classroom facilities within existing buildings together with new staff car and bicycle parking. The ministerial planning permit was approved in March 2024 and subsequent permit amendments were approved in February and April 2026 to refine campus works including a gatehouse, pool reception improvements, bicycle facilities and flood-related design changes.
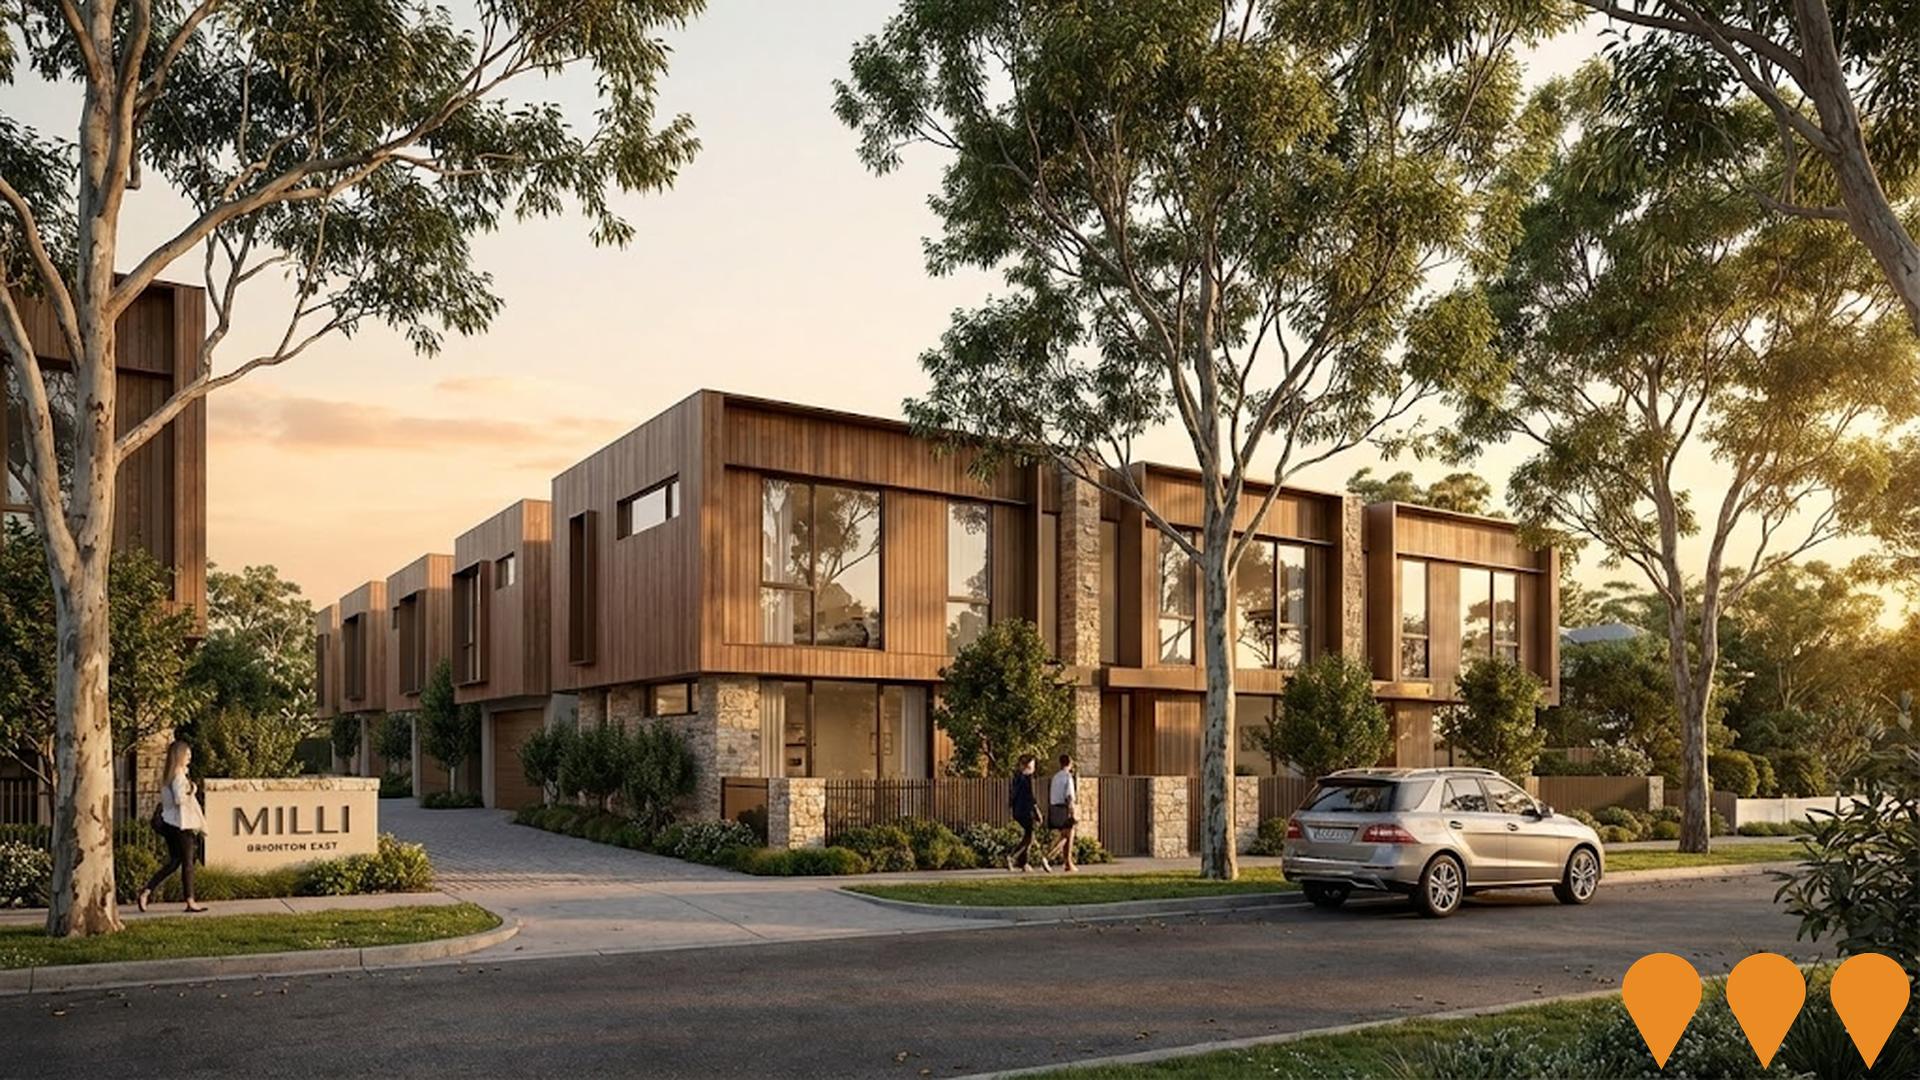
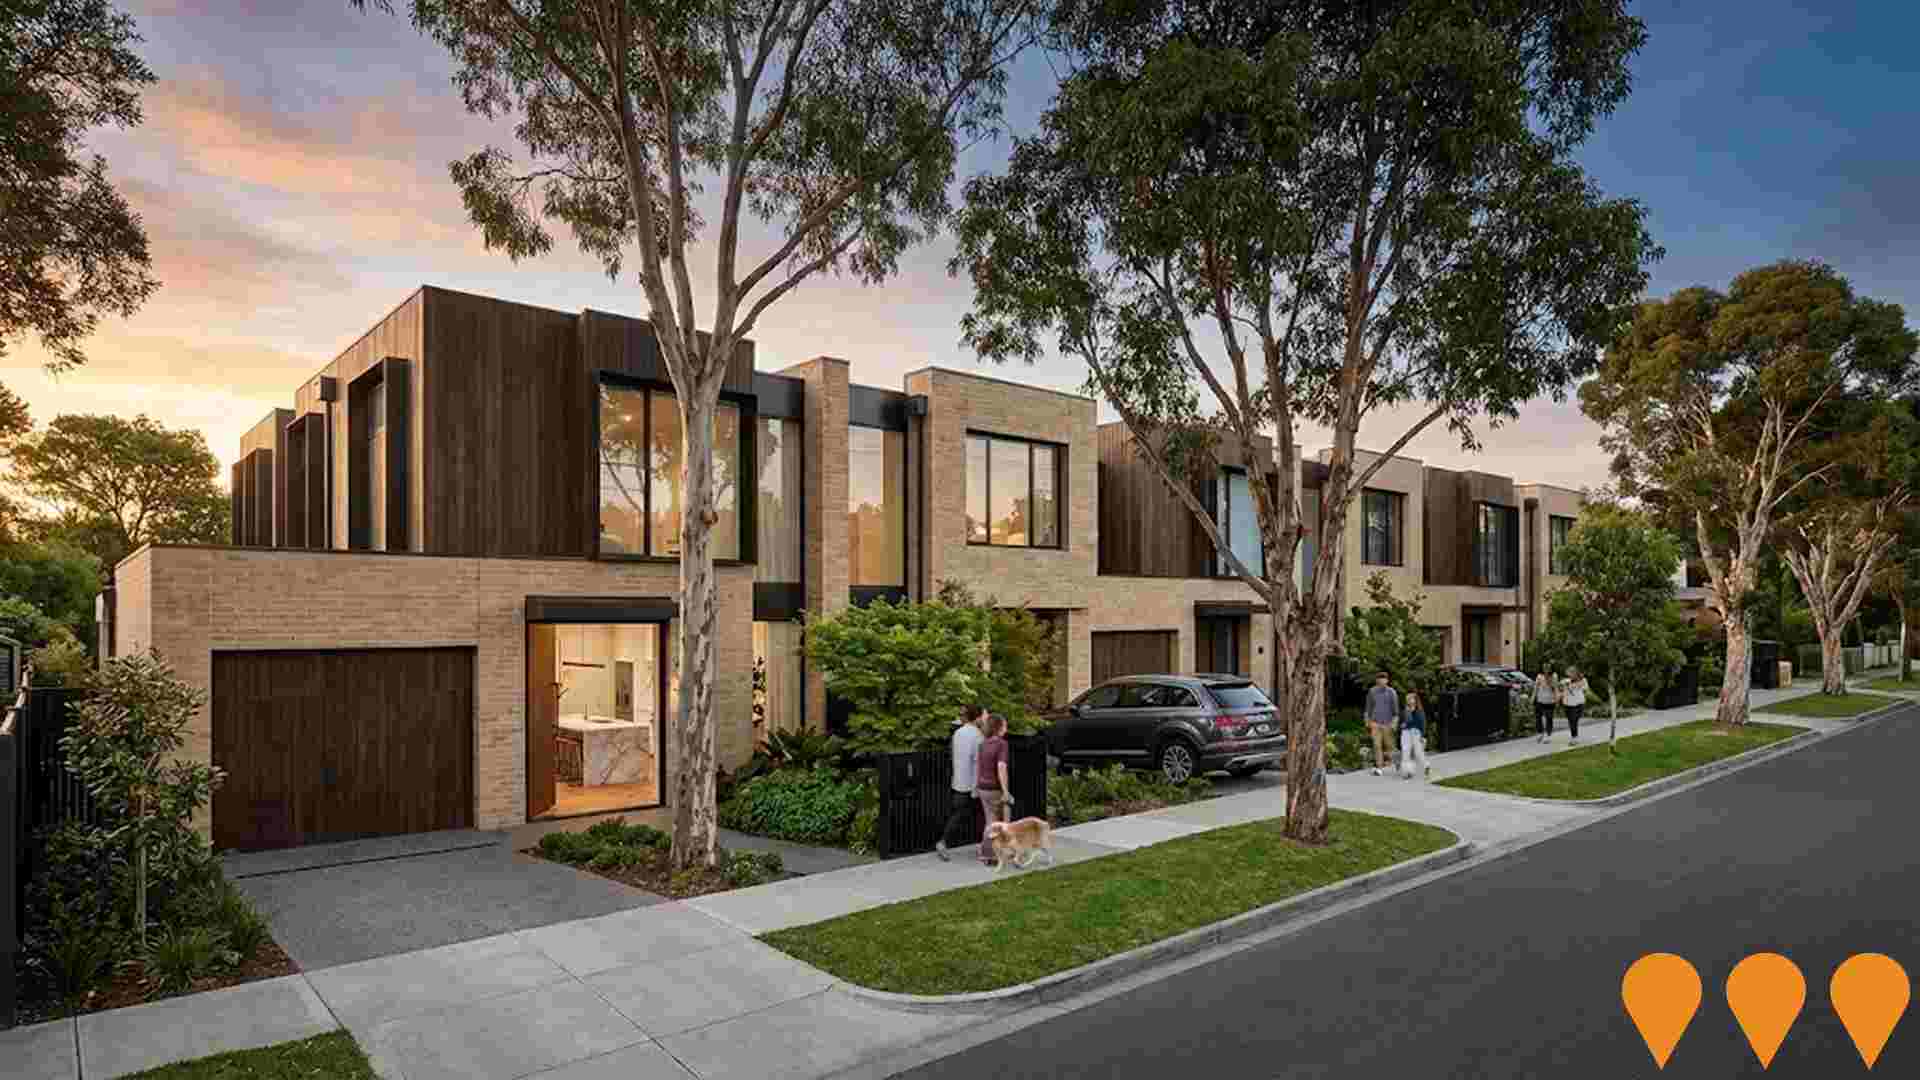
Milli Brighton East
Contemporary village of 28 exclusive townhomes in Brighton East designed by Cera Stribley Architects and DM Property. Features 3 and 4-bedroom residences with open-plan living, inspired by natural rhythms and textures of the bay. Development includes established trees, parklands, and leafy streetscapes with proximity to Brighton Beach.
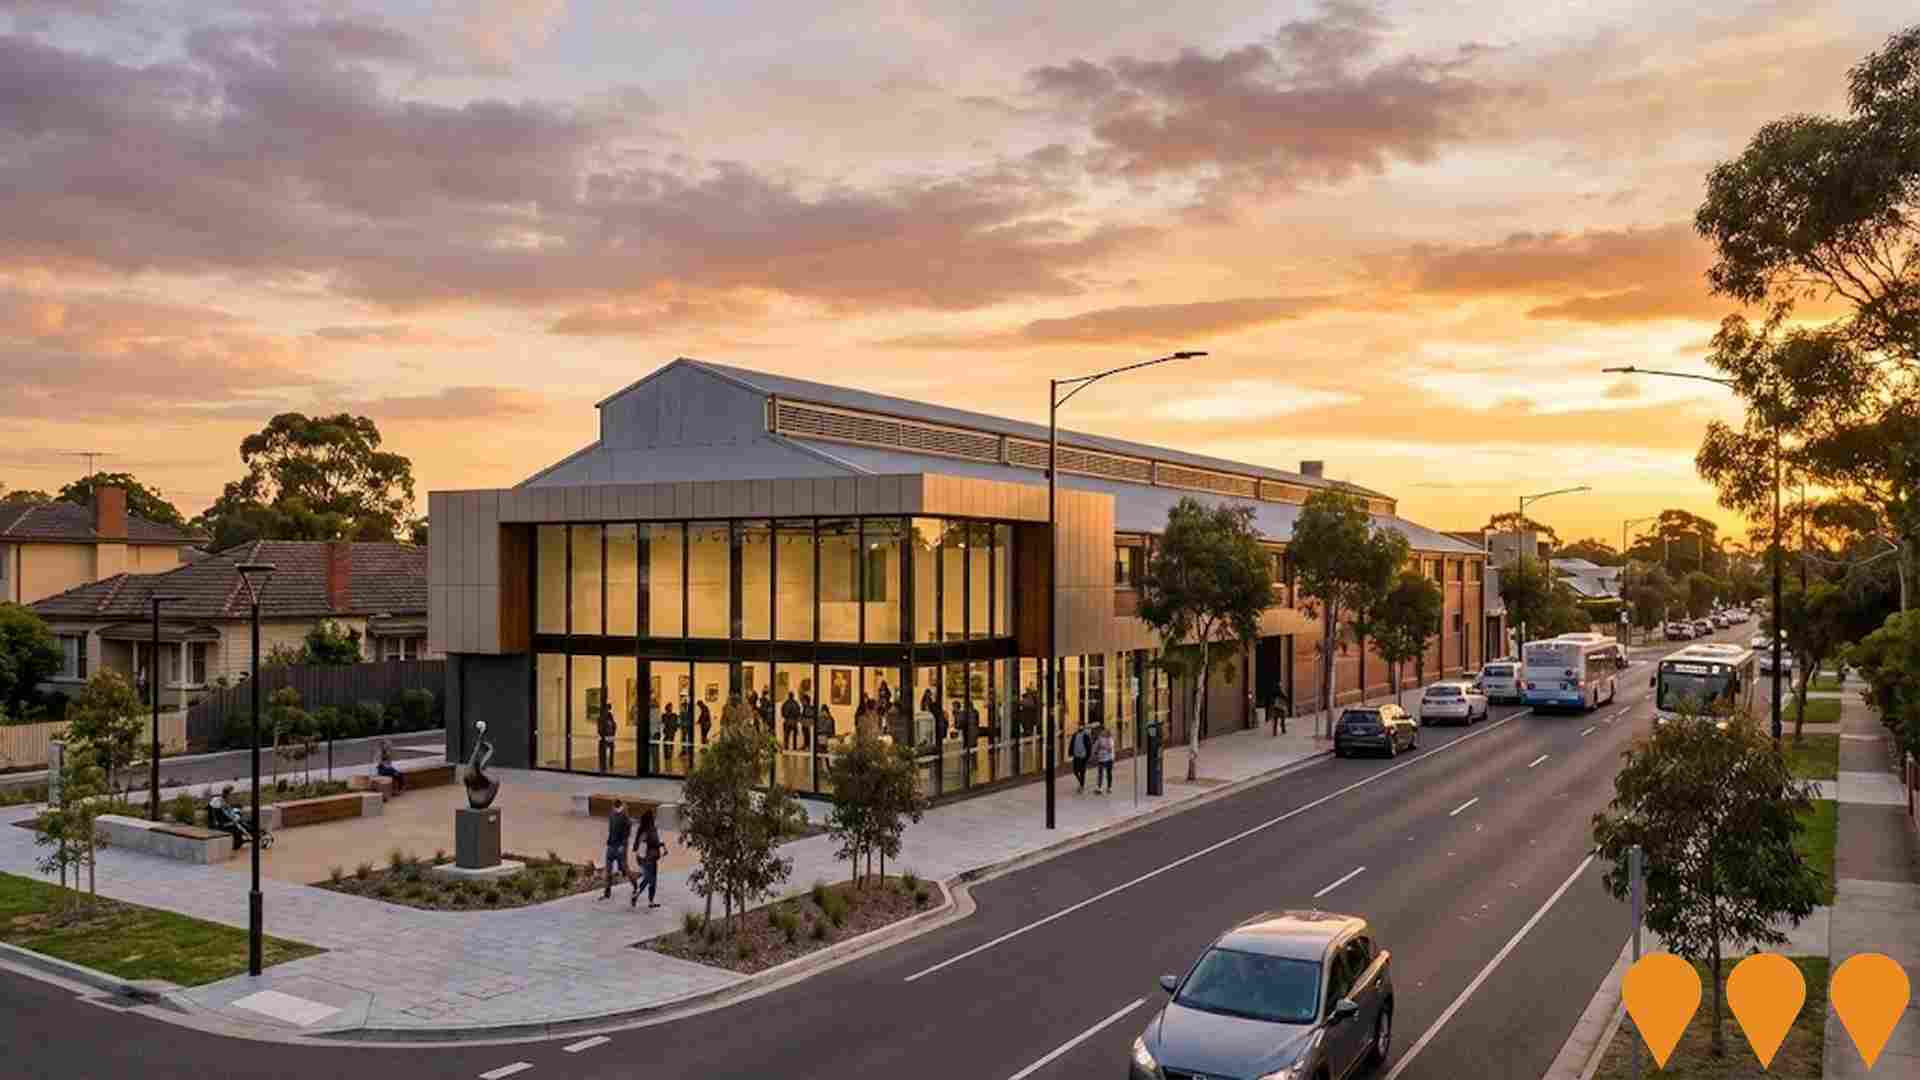
Bayside Gallery Building Works
Renovation and expansion works for the Bayside Gallery, enhancing the cultural facilities and exhibition spaces. The project includes modernization of gallery spaces, improved accessibility, and enhanced visitor amenities.
Laurel, Bentleigh (Bentleigh Club Redevelopment)
Redevelopment of the former Bentleigh Club site into Laurel, a Metro Property Development townhome project in Bentleigh. Now under construction and nearing completion, the project delivers 35 all-electric family townhomes across 4 and 5 bedroom layouts with two living zones, street frontage, deep backyards, double glazing, 7.5-star NatHERS ratings and 4.4kW solar systems. Architecture is by ClarkeHopkinsClarke with landscapes by MDG Landscape Architects, and the project is marketed by Marshall White Projects. Homes are priced from $1,595,000 with move-in expected in spring 2026.
Star of the Sea College Nano Nagle Centre
Construction of the Nano Nagle Centre as the next stage of the Star of the Sea College Master Plan. The redevelopment replaces Sebastian Hall with a modern multi-level education and community facility including two full-sized basketball courts, 900 retractable seats, flexible learning spaces, student social areas and future stages incorporating a new library and cafe. Construction commenced in 2025 with Stage 1 progressing and targeted for completion by the end of 2026.
Train and Tram Zone Activity Centres Program - Bentleigh Centre
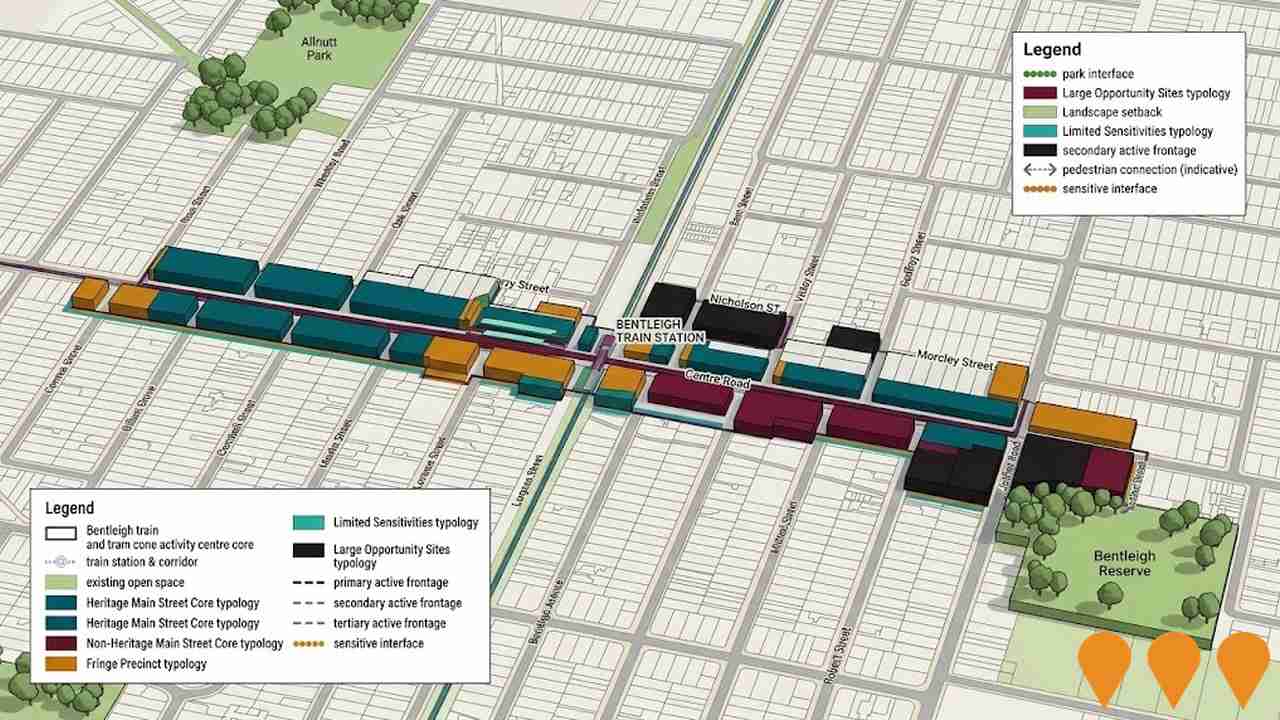
State government planning initiative under Stage 2 of the Activity Centres Program establishing updated planning controls, height limits, and transit-oriented development frameworks within 800 metres of Bentleigh Railway Station to accommodate housing growth.
Metro Tunnel Network Upgrades - Sandringham, Werribee and Williamstown Cross-City Service
Rail network upgrade works associated with the Metro Tunnel program and the 2026 timetable changes. The Metro Tunnel is open and major construction of the five new stations and tunnels is complete, while some rail works and disruptions continue. The Werribee, Laverton and Williamstown lines now start and end at Flinders Street under the new timetable, and later in 2026 are planned to connect with the Sandringham Line to form a new cross-city service. The broader program frees capacity in the City Loop and supports more frequent services across Melbourne's rail network.
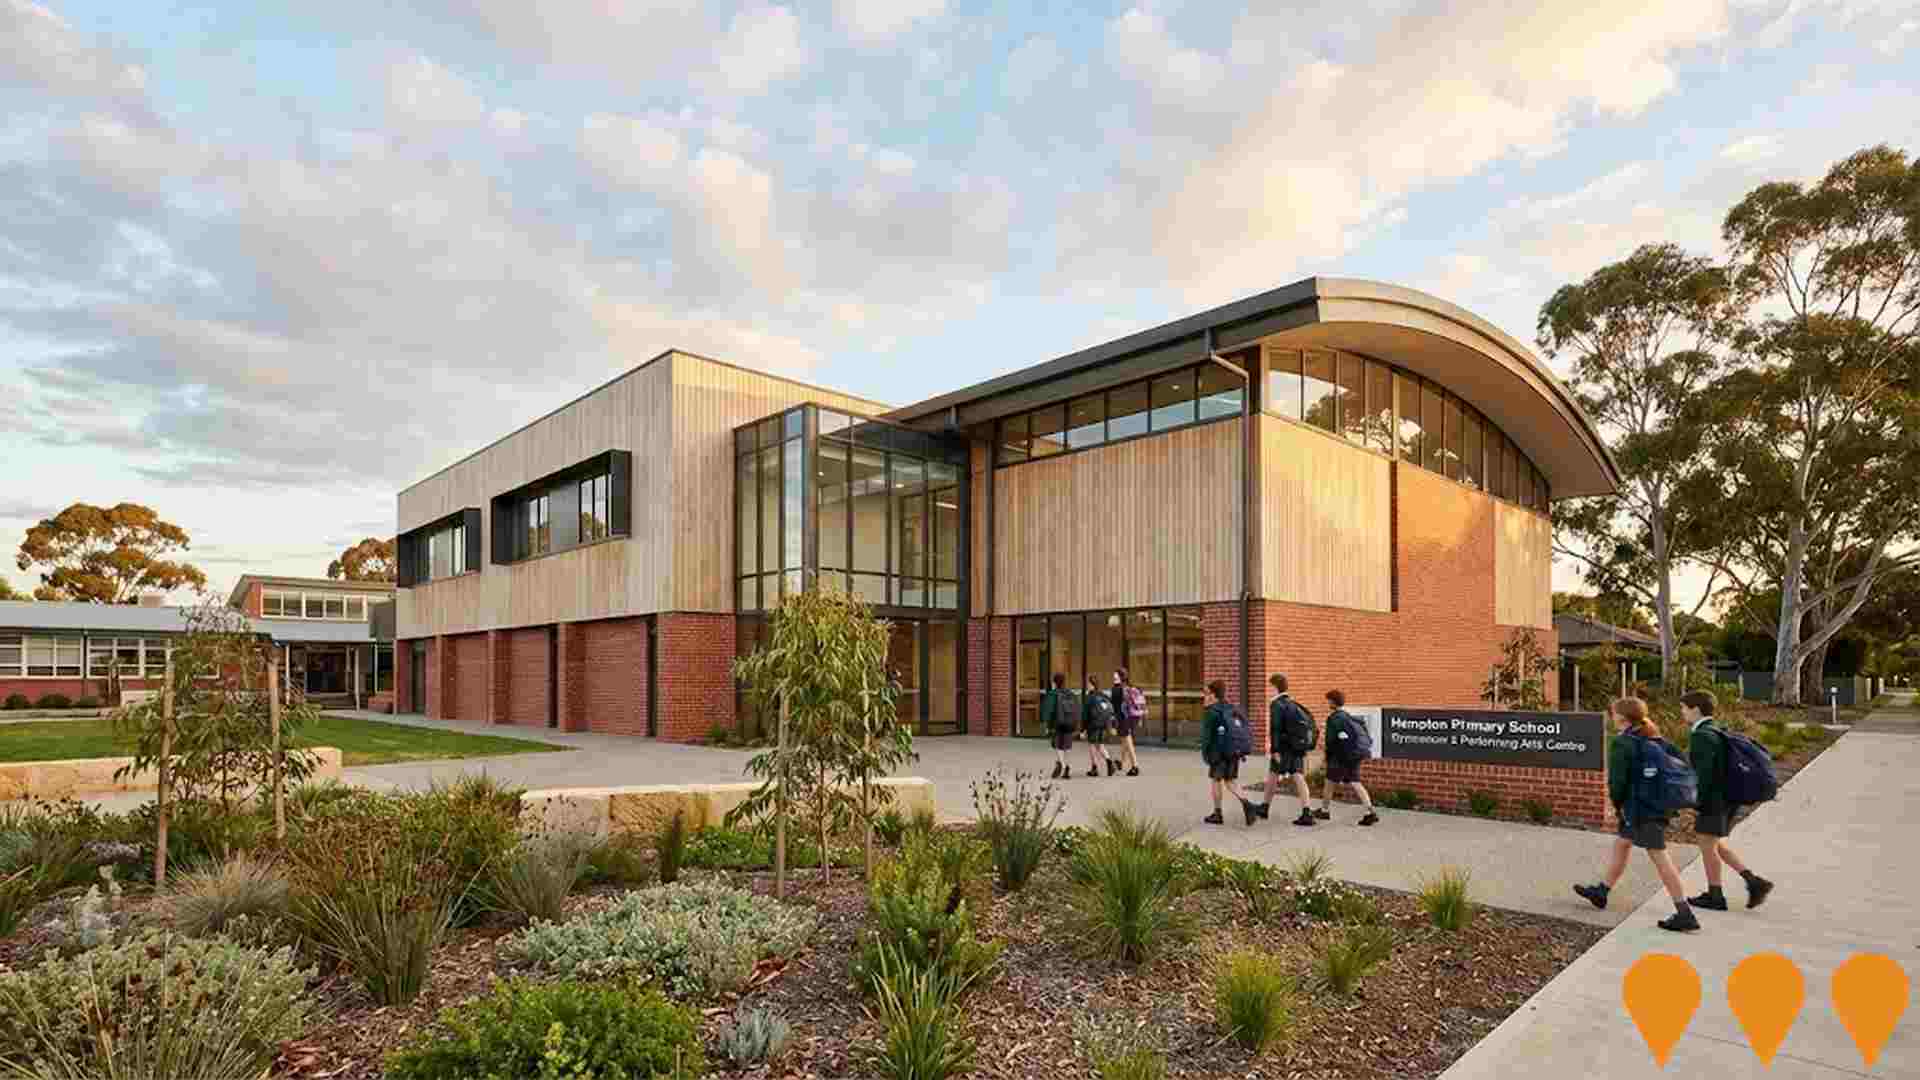
Hampton Primary School Upgrade and Modernisation
Victorian School Building Authority upgrade comprising a new gymnasium, performing arts centre, additional classrooms, relocation of an existing modular building and associated site works to modernise Hampton Primary School. Construction is underway with completion forecast for Q2 2027. Total project funding announced is AUD 9.8 million including earlier planning funding.
9,307 residents of Brighton East are employed, from a labour force of 9,578. Unemployment sits at 2.8%, with participation at 65.7%. Weighted for its industry mix, the area's sectors are forecast to grow about 7.1% nationally over five years. That reflects industry composition only and makes no allowance for local population growth. The working-day population is estimated at 14,714, about 84% of the resident population, so more people leave the area for work than travel in. Unemployment and labour force come from ABS Small Area Labour Markets, updated quarterly; the industry and occupation profile is from the 2021 Census.
Detail
The local labor pool in Brighton East is exceptionally qualified, featuring extensive representation across professional services, an unemployment rate of only 2.8%, and dependable job market stability across the previous twelve months. As of March 2026, employed residents total 9,307, with local unemployment tracking 1.9% below the 4.8% benchmark observed across Greater Melbourne, even as workforce participation remains somewhat suppressed at 65.7% against the metropolitan figure of 70.1%. Census records show that a substantial 49.1% of workers conducted their duties from home, an outcome influenced in part by Covid-19 restrictions.
The primary employment sectors for local residents are professional & technical services, health care & social assistance, and retail trade. Brighton East demonstrates a notable concentration within professional & technical roles, capturing a workforce share 1.6 times that of the regional benchmark. Conversely, transport, postal & warehousing represents just 2.6% of resident employment, trailing Greater Melbourne's 5.2%. A comparison between local resident worker counts and total jobs located within the suburb confirms that this residential enclave provides relatively few internal employment positions. AreaSearch's evaluation of ABS and SALM metrics indicates that the past twelve months saw both the overall workforce and total employed persons contract by 0.3%, holding unemployment virtually unchanged. In contrast, Greater Melbourne registered a 2.1% increase in employment, a 2.3% expansion in the labor force, and a 0.2 percentage point rise in unemployment. Further context regarding future labor requirements in Brighton East can be drawn from national workforce forecasts published by Jobs and Skills Australia as of Mar-26. Applying these five-year and ten-year national trajectory models—which anticipate nationwide employment gains of 6.6% over five years and 13.7% over ten years across varying industries—to Brighton East's specific sector distribution indicates local job opportunities could rise by 7.1% over five years and 14.2% over ten years (a weighted projection designed purely for illustration that excludes local demographic shifts).
Frequently Asked Questions - Employment
Median household income in Brighton East is $2,720 a week (about $141,000 a year), with median personal income at $1,064 a week. ATO records put median taxable income at $66,255 a year against an average of $113,323. The average runs 71% above the median, a wider spread than most areas and a sign of a concentrated group of high earners. Household income is from the 2021 Census; taxable income is from ATO Taxation Statistics for the latest financial year available, indexed forward using the ABS Wage Price Index.
Detail
Recent ATO tax statistics at postcode level compiled by AreaSearch for financial year 2023 place personal earnings in the Brighton East SA2 within the highest percentile nationwide, registering a median of $66,255 alongside an average income of $113,323. By comparison, Greater Melbourne recorded a median of $57,688 and an average of $75,164. Factoring in the 9.62% increase in the Wage Price Index since financial year 2023, updated estimates as of March 2026 reach approximately $72,629 for the median and $124,225 for the average. In the 2021 Census, personal, family, and household incomes across Brighton East consistently placed in the 84th to 94th national percentiles.
High earners are prevalent, with 35.0% of residents (6,139 individuals) earning $4000+ per week, diverging from metropolitan trends where 32.8% fall in the $1,500 - 2,999 bracket. Economic affluence is further reflected by the 46.6% of households generating weekly incomes above $3,000, underpinning strong consumer capacity. Shelter expenses consume 15.0% of income, while net disposable income ranks in the 94th percentile nationally and the area achieves a SEIFA income score in the 10th decile.
Frequently Asked Questions - Income
Brighton East had 5,787 occupied dwellings at the 2021 Census, 71% detached houses and 4% apartments. 37% are owned with a mortgage, 21% rented and 43% owned outright. At that Census the median rent was $602 a week and the median mortgage repayment $3,335 a month, a total housing cost higher than 93% of areas nationally. Rent absorbs 22.1% of household income here and mortgage repayments 28.3%. Dwelling stock, tenure and housing costs are 2021 Census measures — the only source that counts dwellings at this boundary size.
Detail
Residential patterns documented in the most recent Census show that Brighton East was composed of 71.0% standalone houses and 29.1% other dwellings (including semi-detached units, apartments, and non-standard housing), whereas Melbourne metro recorded 67.9% houses and 32.1% other dwellings. Outright homeownership was markedly higher than across the broader metropolis at 42.5%, with remaining properties split between mortgaged residences (36.6%) and tenant-occupied rentals (20.9%). Typical housing costs were elevated: monthly mortgage payments commanded a median of $3,335 compared to the Melbourne metro level of $2,000, while median weekly rent stood at $602 versus $390 regionally.
On a nationwide scale, local mortgage burdens substantially outstrip the Australian norm of $1,863, and rents exceed the national median of $375.
Frequently Asked Questions - Housing
Brighton East counted 5,787 households at the 2021 Census, an estimated 6,138 today, averaging 2.7 people each. 42% are couples with children, more than in 82% of areas nationally, against 25% couples without children. 21% of households are people living alone, and families average 1.5 children. Household and family composition is measured only by the Census, so these are 2021 figures.
Detail
Family structures represent the vast majority of local households at 76.9%, comprising couples with children (41.7%), couples without children (24.5%), and single parent families (10.2%). Non-family living arrangements account for the remaining 23.1%, consisting of single-person households at 21.1% and group living situations at 2.0%. The typical household size sits at 2.7 people, slightly above the Greater Melbourne average of 2.6.
Frequently Asked Questions - Households
49.6% of adults in Brighton East hold a university qualification, including 32.9% with a bachelor degree and 12.3% with postgraduate qualifications, higher than 99% of areas nationally. A further 9.5% hold a vocational qualification. 5 schools serve the area, with 3,477 enrolment places and an average ICSEA of 1,152 against a national benchmark of 1,000. Qualifications come from the 2021 Census; school enrolments, ICSEA and results come from ACARA's current release.
Detail
Tertiary attainment among Brighton East residents outpaces broader benchmarks by a wide margin, with 49.6% of people aged 15+ holding a higher education degree, compared with 30.4% across Australia and 33.4% in VIC. This educational profile positions the community exceptionally well for knowledge-intensive industries. Bachelor degrees constitute the largest share at 32.9%, accompanied by postgraduate degrees (12.3%) and graduate diplomas (4.4%). Vocational accreditations account for 20.6% of qualifications held by individuals aged 15+, divided between advanced diplomas (11.1%) and certificates (9.5%). Engagement in learning programs remains robust, with 32.3% of the resident population participating in formal education.
This proportion includes 10.5% attending primary schools, 10.5% in secondary education, and 6.6% enrolled in tertiary institutions.
Frequently Asked Questions - Education
Schools Detail
Public transport in Brighton East reaches 58 stops on 10 routes, timetabled for about 4,300 services a week. The typical home sits about 200 m from its nearest stop. Buses carry the largest share of public transport commuters. Households keep an average of 1.5 vehicles. Stop and service counts are built from operators' published GTFS timetables and refresh with each timetable release; vehicle ownership is from the 2021 Census.
Detail
Public transportation infrastructure in Brighton East encompasses 58 active stops spanning bus and light rail networks. Across these stops, 10 distinct transit routes deliver a combined 4,310 weekly passenger trips. Overall transport connectivity remains favorable, with residents living a typical distance of 202 meters from their closest boarding point. Reflecting the area's residential orientation, the majority of journeys involve outbound commuting, led overwhelmingly by private vehicle use at 86%, followed by rail transit at 6%. Household car ownership sits at 1.5 vehicles per dwelling, which exceeds the metropolitan benchmark, while 49.1% of workers reported working from home in the 2021 Census during a period shaped by COVID-19 conditions.
Transit route frequency delivers an average of 615 daily services network-wide, translating to roughly 74 weekly departures per individual transit stop.
Frequently Asked Questions - Transport
Transport Stops Detail
72.5% of residents in Brighton East report no long-term health condition. 5.6% need daily assistance with core activities, and 78.0% hold private health cover. The standardised death rate runs at 5.7 per 1,000 residents. Health conditions, assistance needs and insurance are 2021 Census measures; the death rate comes from current ABS releases.
Detail
Based on AreaSearch's evaluation of chronic illness prevalence and mortality indicators, Brighton East displays favorable health standards, accompanied by typical rates of common medical conditions across younger and older demographics alike. Private health insurance participation is remarkably widespread, covering roughly 78% of the community (13,682 people), compared to 56.7% throughout Greater Melbourne and an Australian average of 55.7%. Among reported long-term illnesses, arthritis and asthma emerged as the most prevalent, diagnosed in 7.0 and 6.4% of the population respectively, while 72.5% of residents reported no chronic conditions whatsoever, mirroring Greater Melbourne's 72.6%.
The working-age cohort remains notably resilient against long-term ailments. Residents aged 65 and over make up 20.0% of the community (3,515 people), exceeding the 15.1% share recorded across Greater Melbourne, with senior health indicators tracking above average and holding steady against national benchmarks.
Frequently Asked Questions - Health
30.6% of Brighton East residents were born overseas and 21.6% speak a language other than English at home. The largest reported ancestries are English (23.3%) and Australian (20.3%). Ancestry, language and country of birth are counted only by the Census, so these are 2021 figures.
Detail
Cultural diversity in Brighton East exceeds that of most surrounding neighborhoods, with 30.6% of residents born abroad and 21.6% utilizing a primary language other than English in their households. Christianity represents the most common religious affiliation, encompassing 45.1% of the population. The community also features a distinct concentration of Jewish residents, who make up 9.4% of the population—a proportion substantially higher than the Greater Melbourne share of 1.0%. Regarding ancestral background based on parental country of birth, the primary groups in Brighton East are English (23.3%), Australian (20.3%), and Other (10.8%).
Significant variations also appear among specific European ancestries, with Polish background overrepresented at 2.4% locally (compared to 0.8% across the region), Russian at 1.6% (versus 0.4%), and Hungarian at 0.5% (versus 0.3%).
Frequently Asked Questions - Diversity
The median resident of Brighton East is 44. 23.3% of residents are aged 15 to 34. Age cohorts are not raw Census counts: the Census split is re-based to the latest ABS population estimates and state projections.
Detail
Brighton East exhibits a mature demographic structure compared to Greater Melbourne. Data updated to August 2026 reveals that 28.9% of the local population falls into the middle-aged and semi-retired bracket (45 - 64), against 22.3% metropolitan-wide, whereas young-to-mid career adults (25 - 44) comprise 18.7% compared to the regional figure of 32.1%. Consequently, the median age is estimated at 44 years, matching the 2021 Census outcome and exceeding the Greater Melbourne median of 37 from that same Census by 7 years. The Australian national median was 38. Long-term projections to 2041 indicate that the largest demographic addition will take place within the senior bracket (65+), expanding by 1,059 residents (30%) to reach 4,574.
Frequently Asked Questions - Age
Data & MethodBoundaries, Sources & Method for Brighton East
9 of 14 data sections on this page were updated within the last 12 months — the newest current to Sep 2026.
Everything is aggregated to the SA2 boundary shown above, on a 2021 Census baseline. Only 3 sections — housing, households and cultural diversity — still wait on the 2026 Census.
The ledger — source, cycle and currency by section
| Section | Source & update cycle | Currency |
|---|---|---|
| Updated within the last 12 months 9 sections | ||
| Population | ABS, GNAF, Geoscience Australia Annual (ABS ERP) | Aug 2026 2 months ago headline measures · 2021 Census baseline |
| Re-based to the ABS Estimated Resident Population (June 2025 release) and updated with new dwellings from GNAF address data. Current to Aug 2026, with the 2021 Census supplying the small-area baseline. | ||
| Age profile | ABS, Geoscience Australia, State governments Annual | Aug 2026 2 months ago headline measures · 2021 Census baseline |
| Age cohorts are re-based to the latest ABS population estimates and state projections, current to Aug 2026. Each cohort is held as a Census baseline and a current estimate. | ||
| Development & approvals | ABS, GNAF Monthly (ABS approvals) | Aug 2026 2 months ago headline measures · Jul 2026 baseline |
| Property sales & rents | Valuer General, Rental Board, ABS Weekly sales, quarterly rents | Sep 2026 last month all 21 measures |
| Sales from the state Valuer General register, refreshed weekly, and rents from quarterly rental bond lodgements. Both are read live each time this page loads, current to Sep 2026. | ||
| Infrastructure projects | Infrastructure Australia, State agencies, Local governments Daily | Jul 2026 3 months ago all 6 projects tracked here |
| Project pipeline maintained continuously from Infrastructure Australia, state agencies, local government and public announcements. Records are added and revised daily; this area was last updated Jul 2026. | ||
| Employment | ABS, DEWR, JSA Quarterly (ABS SALM) | Mar 2026 7 months ago headline measures · 2021 Census baseline |
| Unemployment and labour force from ABS Small Area Labour Markets, current to Mar 2026. The growth outlook applies Department of Employment (now Jobs and Skills Australia) forecasts for all 19 industry divisions to the local industry mix, so it measures sector composition rather than local expansion and makes no allowance for population growth. Job demand comes from the same agency via its Internet Vacancy Index; industry and occupation structure from the 2021 Census. | ||
| Education | ABS, ACARA Annual (ACARA) | Sep 2026 last month headline measures · 2021 Census baseline |
| Transport | ABS, State Transport Departments Each timetable release | Jul 2026 3 months ago headline measures · 2021 Census baseline |
| Services & amenities | Provider directories, ACECQA Continuous | Sep 2026 last month all 14 measures |
| Annual and financial-year sources 2 sections | ||
| Income | ABS, ATO Annual (ATO) | FY 2023 3 years ago headline measures · 2021 Census baseline |
| ATO taxable income statistics for FY 2023, indexed forward using the Wage Price Index. Census household income provides the distribution detail. | ||
| Health | ABS, ATO Annual | 2024 2 years ago headline measures · 2021 Census baseline |
| Census-measured — next update: 2026 Census 3 sections No more current small-area source exists for these, so they are labelled as Census-measured rather than implied to be current. | ||
| Housing | ABS 5-yearly (Census) | 2021 Census next update 2026 all 30 measures |
| Households | ABS 5-yearly (Census) | 2021 Census next update 2026 all 18 measures |
| Cultural diversity | ABS, Geoscience Australia 5-yearly (Census) | 2021 Census next update 2026 all 44 measures |
"Currency" is the most recent release feeding that section. Where the Census supplies the structural baseline underneath a current headline figure, the row says so.
How the numbers are built
Population
The Census provides the small-area baseline, aggregated from mesh blocks to this boundary. It is then re-based to the ABS Estimated Resident Population (June 2025 release), and new dwellings built since Census night are counted from address data — 80 validated new addresses here. The headline figure is therefore a current estimate for Aug 2026, not a 2021 count (16,540 at the 2021 Census → 17,542 now). Annual growth rates are compound (CAGR), not simple averages.
Age profile
Cohort shares are not raw Census counts. Every cohort is held as a pair — the Census baseline and a current estimate — and the split is re-based using ERP and state population projections, current to Aug 2026. Median age is the Census median plus modelled change since. Charts that show both are labelled "2021 Census vs Current Estimate".
Property sales
Sourced from the state valuation authority's sales register — current, not Census, and refreshed weekly. Medians are calculated from settled transactions in the period shown; periods with very low transaction counts are flagged or suppressed, because a handful of sales can move a median substantially.
Rents
Derived from state rental bond lodgement data, by dwelling type and bedroom count. Bonds are lodged at the start of a new tenancy, so this reflects new lettings, not the whole rented stock.
Development & infrastructure
Building approvals come from current ABS releases; development applications are collected from council and state planning portals; the infrastructure pipeline is compiled from Infrastructure Australia and local government sources. Applications are matched to this boundary by address or coordinates, so very recent lodgements may not yet appear.
Employment & income
Industry and occupation structure comes from the Census, but the headline labour-market indicators do not. Unemployment and labour force are derived from ABS Small Area Labour Markets (quarterly). The employment outlook applies Department of Employment forecasts for all 19 industry divisions to this area's own industry mix (the agency is now Jobs and Skills Australia), as does the Internet Vacancy Index used for job demand. Because it is weighted on industry composition alone, that outlook carries no allowance for local population growth — in fast-growing areas the real rise in local jobs will typically be higher. Income combines Census household income with ATO taxable-income statistics for FY 2023, indexed forward using the Wage Price Index.
Education, transport & amenities
School enrolments, ICSEA and performance come from ACARA's current release, not the Census. Public transport stops and service frequency are derived from GTFS timetable feeds published by state transport departments. Services and amenities are proximity and count scores built from provider directories, refreshed on their own cycle. The Census contributes only the travel-to-work and qualification measures.
Rankings and benchmarks. Where we rank this area, the comparison set is every area of the same boundary type — suburbs against suburbs, SA2s against SA2s. Benchmarks compare this area against its greater capital city region and the national figure for the same measure and period.
Limits worth knowing. Small areas carry larger error margins, and the ABS introduces small random adjustments to Census counts to protect confidentiality — so totals may not sum exactly. Estimates re-based from regional data describe the area's expected trajectory, not a direct count of it. Figures are indicative for research and are not financial, planning or valuation advice.
Cross-check us. The Census baseline for this boundary is at ABS 2021 Census QuickStats (208011170). QuickStats reports 2021 only — the figures on this page are more current wherever the ledger shows a later date.