Chart Color Schemes
This analysis uses Suburbs and Localities (SAL) boundaries, which can materially differ from Statistical Areas (SA2) even when sharing the same name.
SAL boundaries are defined by Australia Post and the Australian Bureau of Statistics to represent commonly-known suburb names used in postal addresses.
Statistical Areas (SA2) are designed for census data collection and may combine multiple suburbs or use different geographic boundaries. For comprehensive analysis, consider reviewing both boundary types if available.
est. as @ -- *
2021 Census | -- people


Curious about local property values? Filter the chart to assess the volume and appreciation (including resales) trends and regional comparisons, or scroll to the map below view this information at an individual property level.
Find a Recent Sale

Sales Detail
South Melbourne has an estimated 14,525 residents, up from 11,548 at the 2021 Census — a change of 2,977 people, or 25.8%. Growth has averaged 2.9% a year over five years, faster than 94% of areas nationally. 1,749 new addresses have been validated here since Census night. Overseas migration accounts for 99.0% of that increase. That puts 6,632 residents on each square kilometre. Population is estimated from ABS Estimated Resident Population releases and GNAF address data, re-based from the 2021 Census and updated annually.
Detail
According to AreaSearch's evaluation of regional ABS updates alongside post-Census address validations, the suburb of South Melbourne reached an estimated 14,525 residents by Aug 2026. This represents an expansion of 2,977 people (25.8%) beyond the 11,548 residents recorded in the 2021 Census. AreaSearch established this 14,525 resident count by reviewing the ABS ERP release from June 2025 in conjunction with 1,749 validated new addresses confirmed following the Census. Consequently, population density stands at 6,632 persons per square kilometer, placing the locality in the top 10% of AreaSearch's national coverage and highlighting strong demand for local real estate.
Outpacing both the broader Victorian rate of 9.5% and nationwide figures, the suburb of South Melbourne saw its 25.8% increase establish it as a premier regional growth pocket. This demographic surge was overwhelmingly underpinned by overseas arrivals, who accounted for roughly 99.0% of recent population additions. Projections for each SA2 district rely on 2024 ABS/Geoscience Australia figures pegged to a 2022 baseline, with remaining SA2s mapped via the 2023 VIC State Government Regional/LGA dataset through population-weighted LGA-to-SA2 aggregations. Furthermore, these aggregated age-bracket growth trajectories are applied to every location for the years 2032 to 2041. Moving forward, the suburb of South Melbourne is forecast to maintain top 10 percent growth among statistical areas reviewed by AreaSearch, with aggregated SA2 models projecting an influx of 9,293 persons by 2041, translating to an overall expansion of 63.4% across the 16 years.
Frequently Asked Questions - Population
1,707 new dwellings have been approved in South Melbourne over the past five years, an average of 341 a year. That places the area in the 92nd percentile for residential development activity nationally, about 23 approvals per 1,000 residents a year. Of the 250 dwellings approved in the latest reporting year, 1% were detached houses and the rest townhouses or apartments. Approvals are currently running at an annualised 553, running ahead of that longer-run average. Figures come from ABS building approvals aggregated to this Suburb (SAL) boundary and are updated monthly as the ABS releases them.
Detail
Examining ABS residential approval statistics aggregated across statistical boundaries, AreaSearch observes that South Melbourne averages roughly 341 residential dwelling consents annually, totaling approximately 1,707 residential approvals over the preceding 5 financial years (between FY-21 and FY-25) alongside 553 units approved to date in FY-25. Construction activity remains closely aligned with local intake, with 1.6 incoming occupants recorded per approved home over the past 5 financial years (between FY-21 and FY-25), fostering steady property fundamentals. At the same time, newly approved residences carry an average estimated construction cost of $703,000, underscoring an emphasis by developers on higher-tier, upscale residential builds.
Additionally, the non-residential pipeline shows substantial progress, with $171.3 million in commercial developments sanctioned during the current financial year. On an individual basis, South Melbourne outpaces Greater Melbourne with 68.0% more new home approvals (per person), presenting prospective purchasers with abundant options. This elevated volume substantially exceeds the nationwide baseline, signaling pronounced developer enthusiasm for local projects. Within the residential pipeline, freestanding houses constitute 1.0% while attached townhomes and apartments represent 99.0%. This emphasis on higher-density urban formats provides accessible pricing for entering the market, appealing to first-home buyers, downsizers, and property investors. Generating roughly 29 people per dwelling approval, the neighborhood displays clear hallmarks of an expanding urban center. Demographic forecasts from the most recent AreaSearch quarterly update indicate that South Melbourne will add 9,208 residents by 2041. Present rates of residential construction appear well-aligned with anticipated requirements, encouraging balanced market dynamics in the absence of severe pricing stress.
Frequently Asked Questions - Development
Development applications around South Melbourne
SOURCE: Planning portals and council registers, compiled by AreaSearch. Distance & bearing measured from the suburb midpoint.
AreaSearch tracks 20 current infrastructure and development projects inside South Melbourne, worth an estimated $4.6 billion. A further 180 sit in the immediately surrounding suburbs, taking the tracked pipeline within reach of the area to $104.8 billion. 72 are already under construction and 70 are due for completion within three years. The pipeline spans residential development, communities, precincts & urban renewal and transport & logistics. Records are compiled from Infrastructure Australia, state agencies, council planning portals and public announcements, reviewed and updated daily, then ranked by proximity, construction stage, completion horizon and project scale.
Detail
Local economic and urban performance is heavily shaped by major civic works, transport upgrades, and planning schemes. AreaSearch has pinpointed 63 projects positioned to influence the surrounding precinct. Prominent undertakings include the South Melbourne Town Hall Restoration, First Light, Verde Arts Precinct, and the 80-94 Cecil Street South Melbourne Commercial Development, with significant works detailed below.
Professional plan users can use the search below to filter and access additional projects.
INFRASTRUCTURE SEARCH
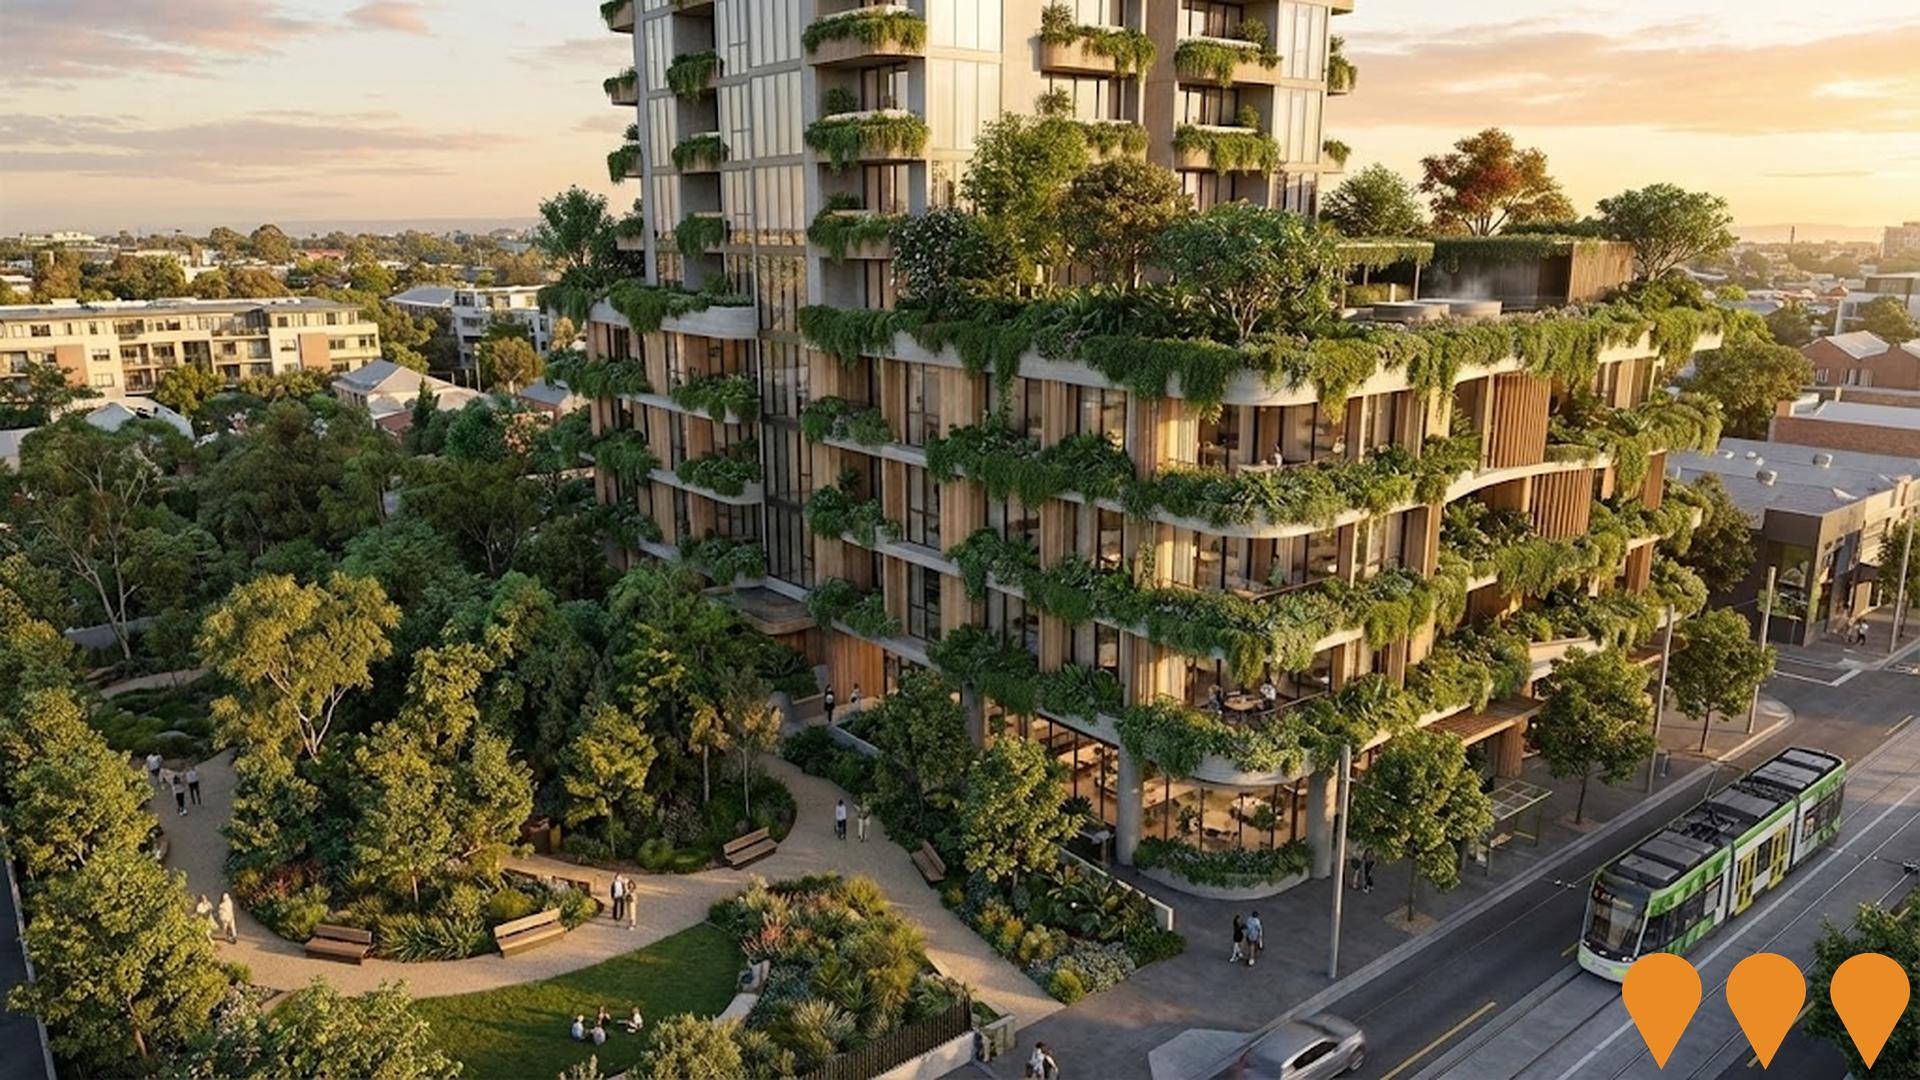
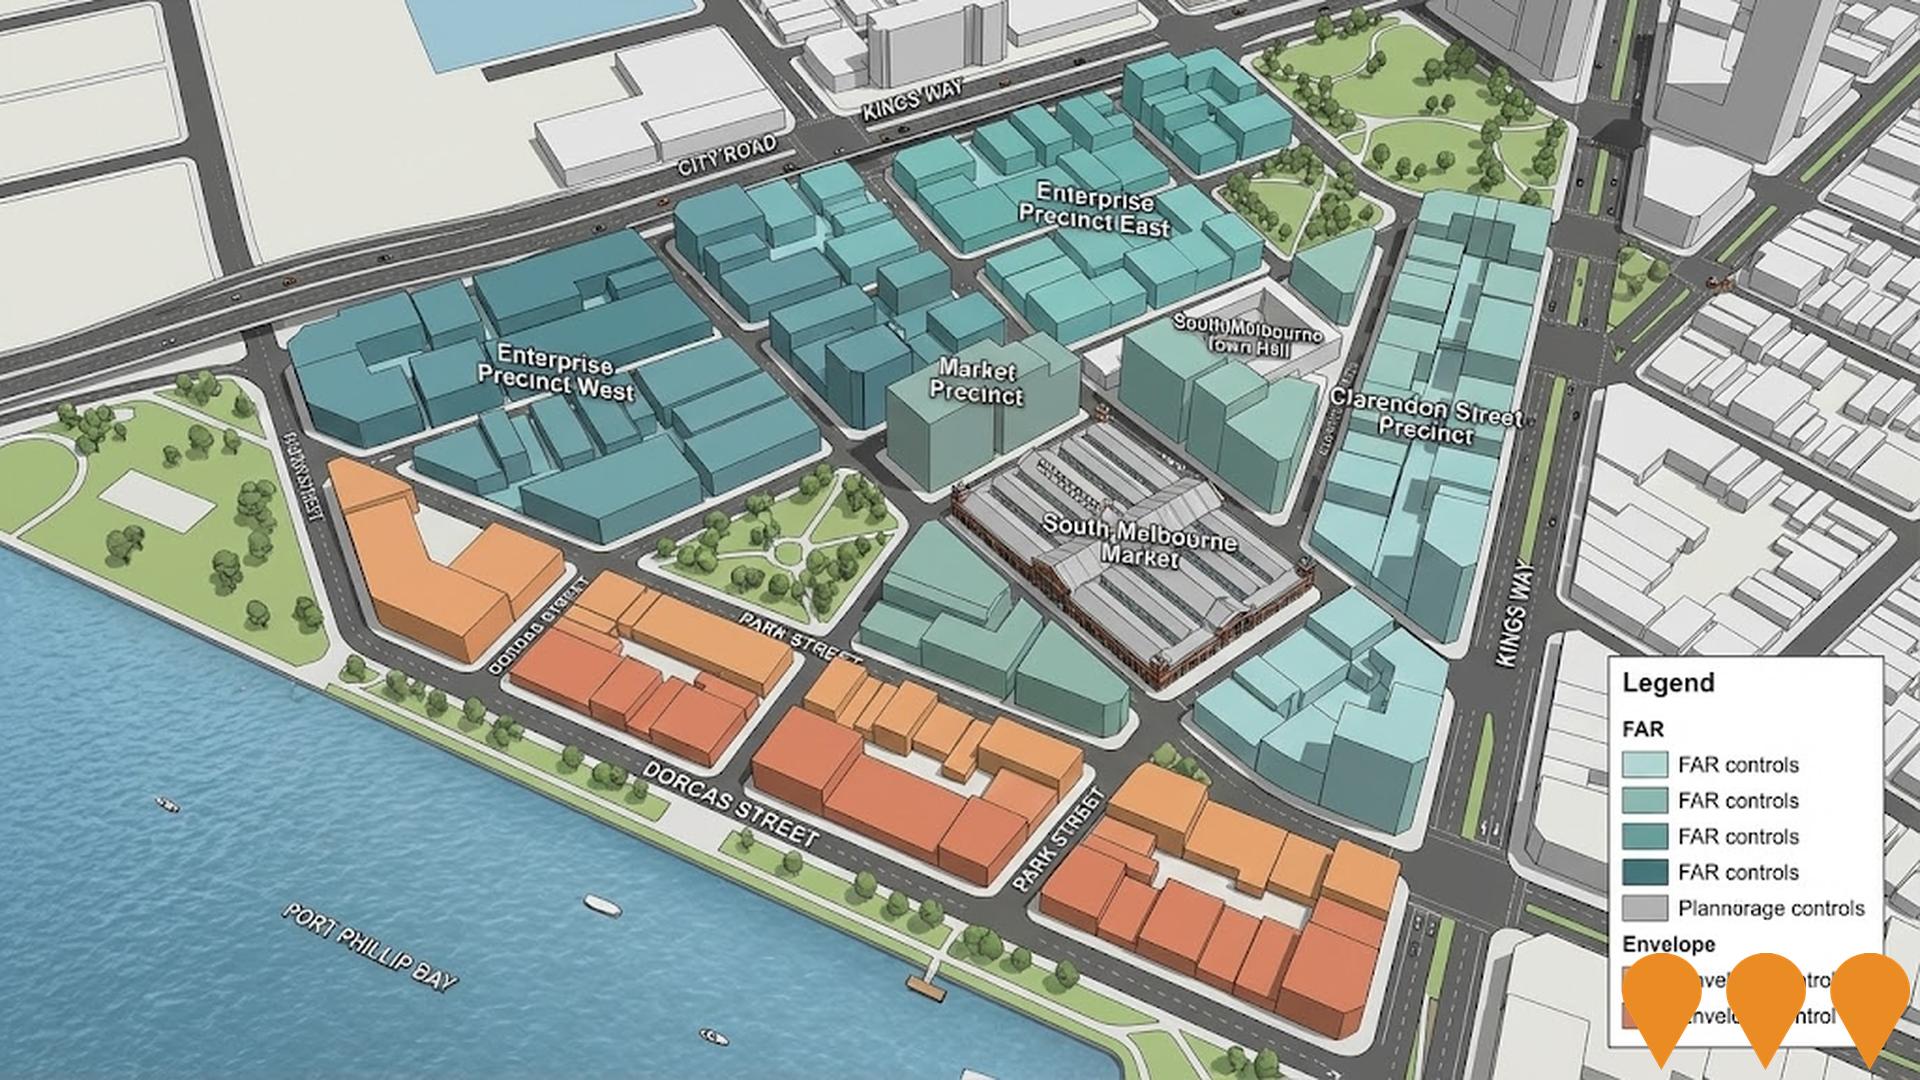
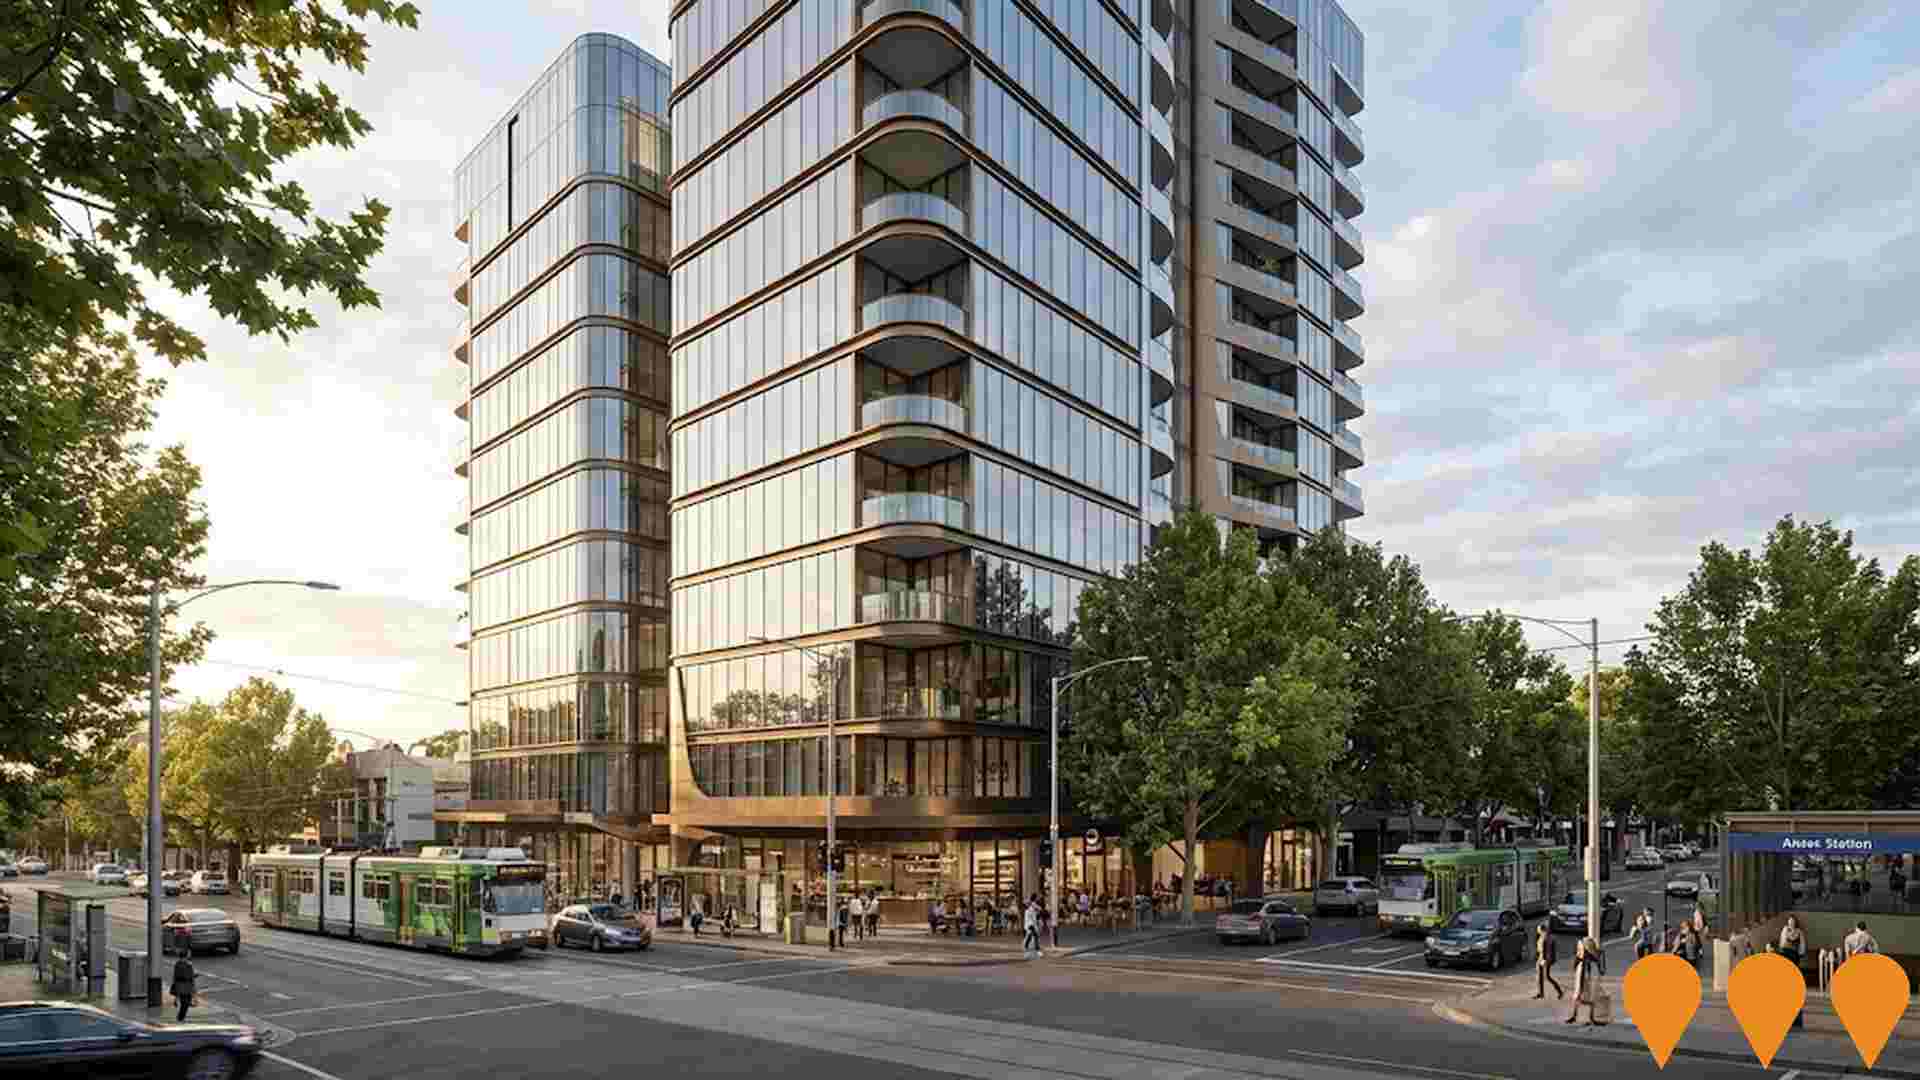
 Denotes AI-based impression for illustrative purposes only, not to be taken as definitive under any circumstances. Please follow links and conduct other investigations from the project's source for actual imagery. Developers and project owners wishing us to use original imagery please Contact Us and we will do so.
Frequently Asked Questions - Infrastructure
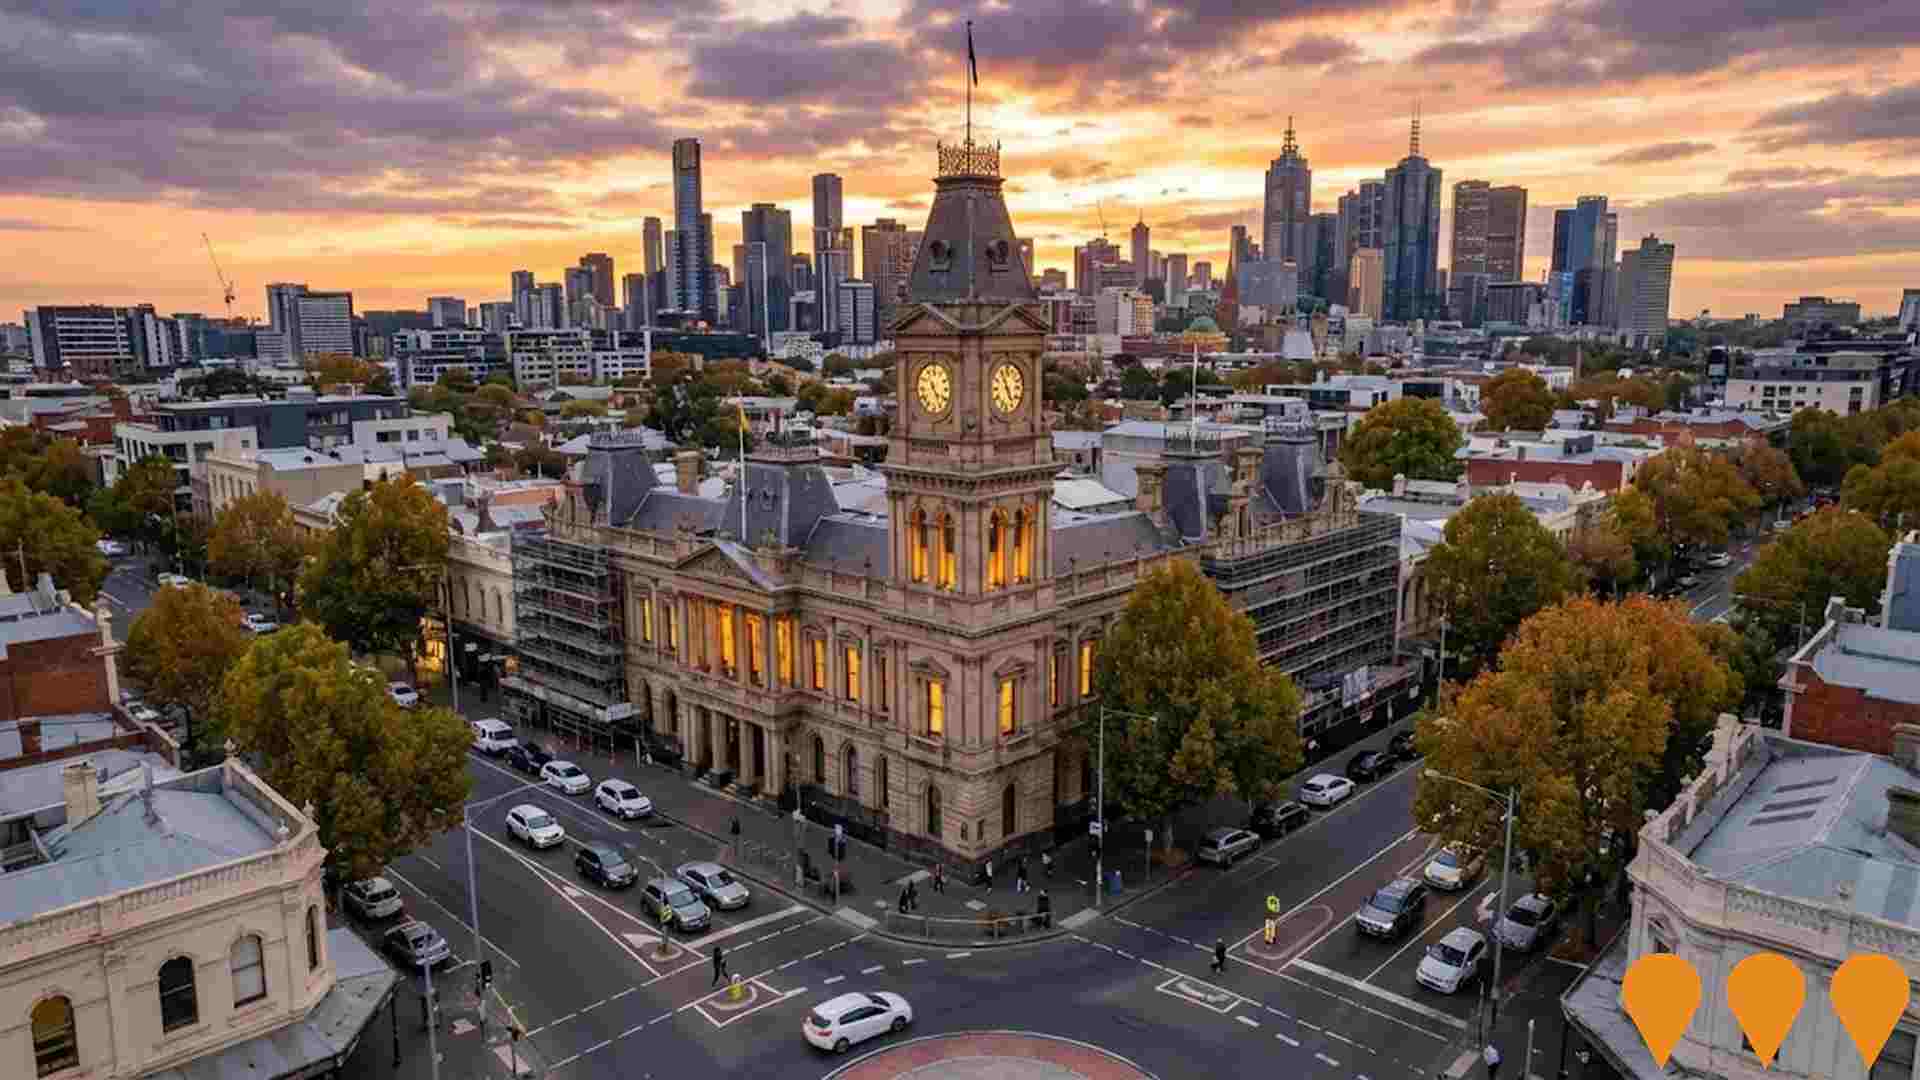
South Melbourne Town Hall Restoration
Major restoration and renewal of the historic South Melbourne Town Hall, preserving its heritage while transforming it into a vibrant cultural and community hub. Works include seismic roof strengthening, a new slate roof, solar panels, a new north-west annexe studio, Clock Tower conservation, and full fit-out of two performance venues (350-seat Main Hall and new 150-seat venue). Co-funded by City of Port Phillip ($60M) and ANAM ($54M including $25M Australian Government and philanthropic contributions). Completion expected late 2027 with public reopening in early 2028.
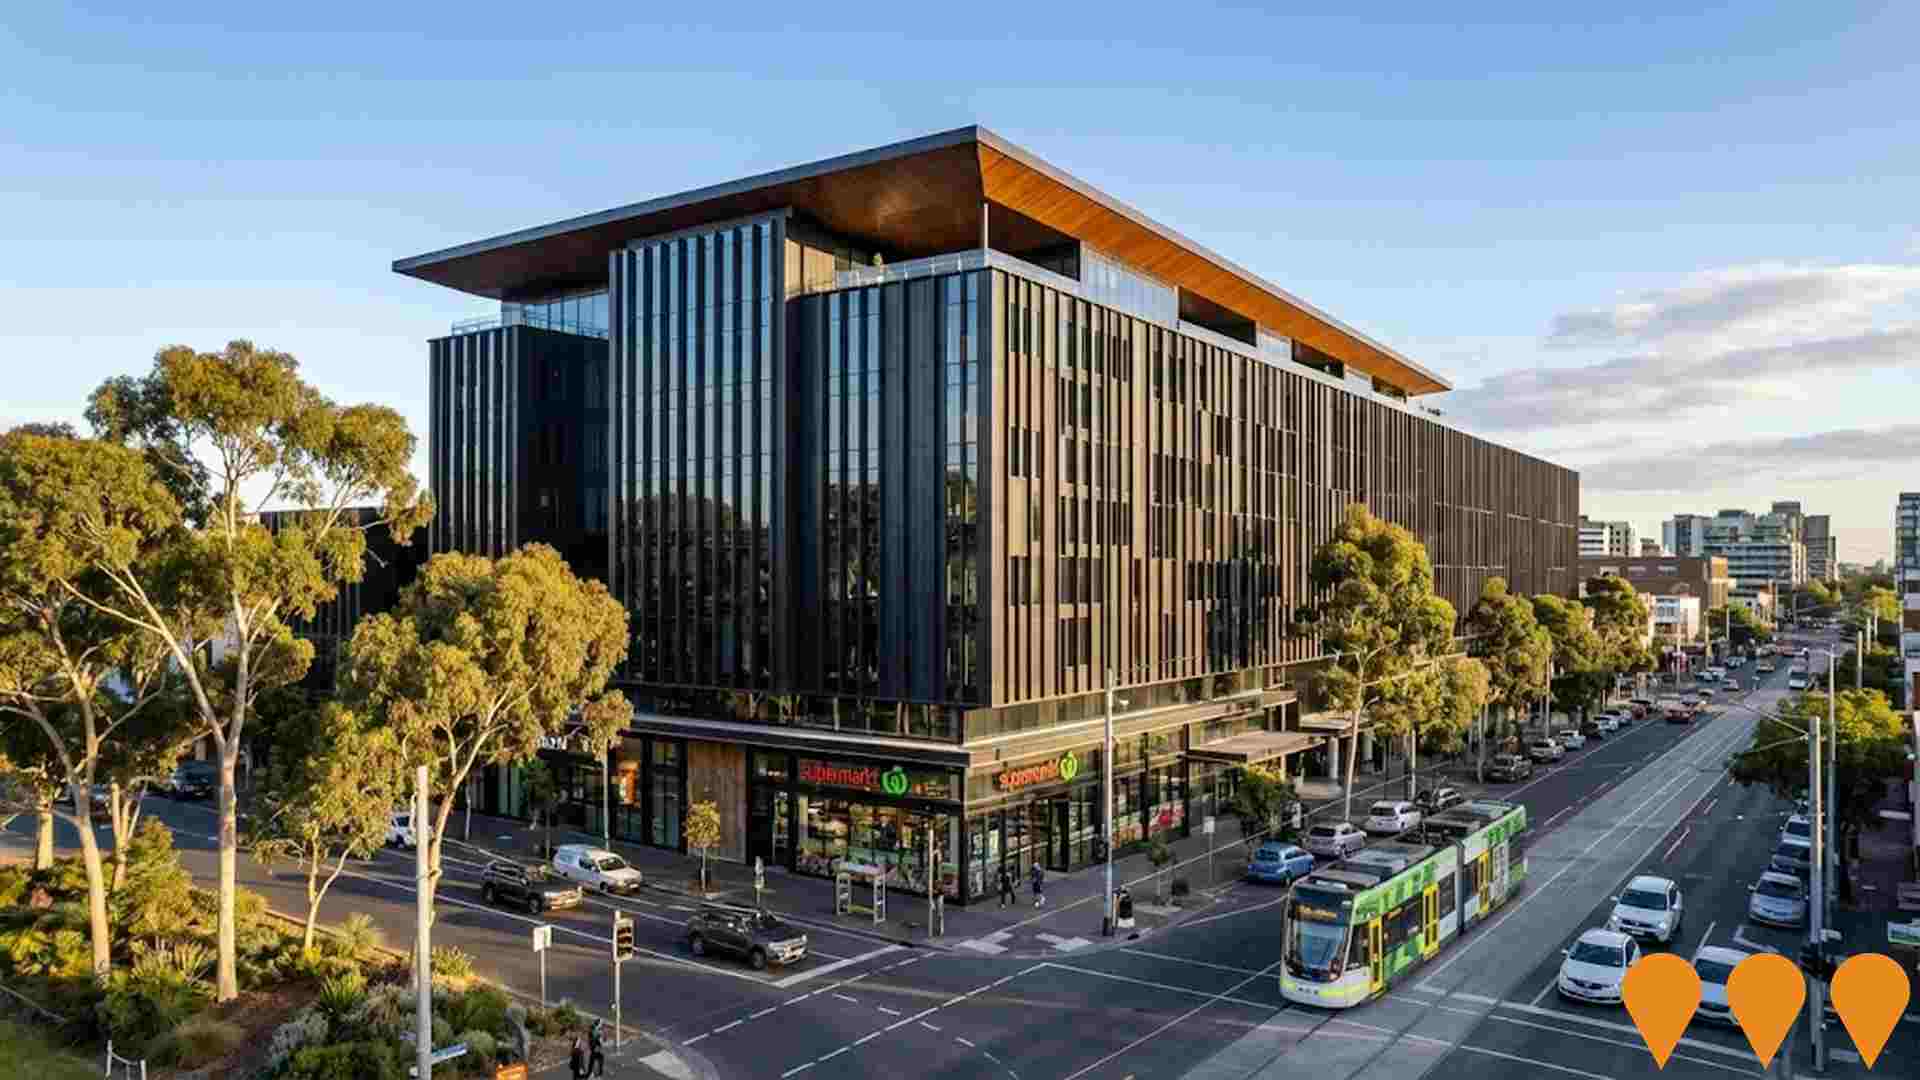
80-94 Cecil Street South Melbourne Commercial Development
Approved commercial and retail redevelopment of a whole South Melbourne block opposite South Melbourne Market. The amended scheme allows a multi-storey building with office space, a supermarket, shops, food and drink premises, a commercial car park, basement parking, public realm works on Northumberland Street and retention of the heritage Southern Cross Hotel at 78 Cecil Street.
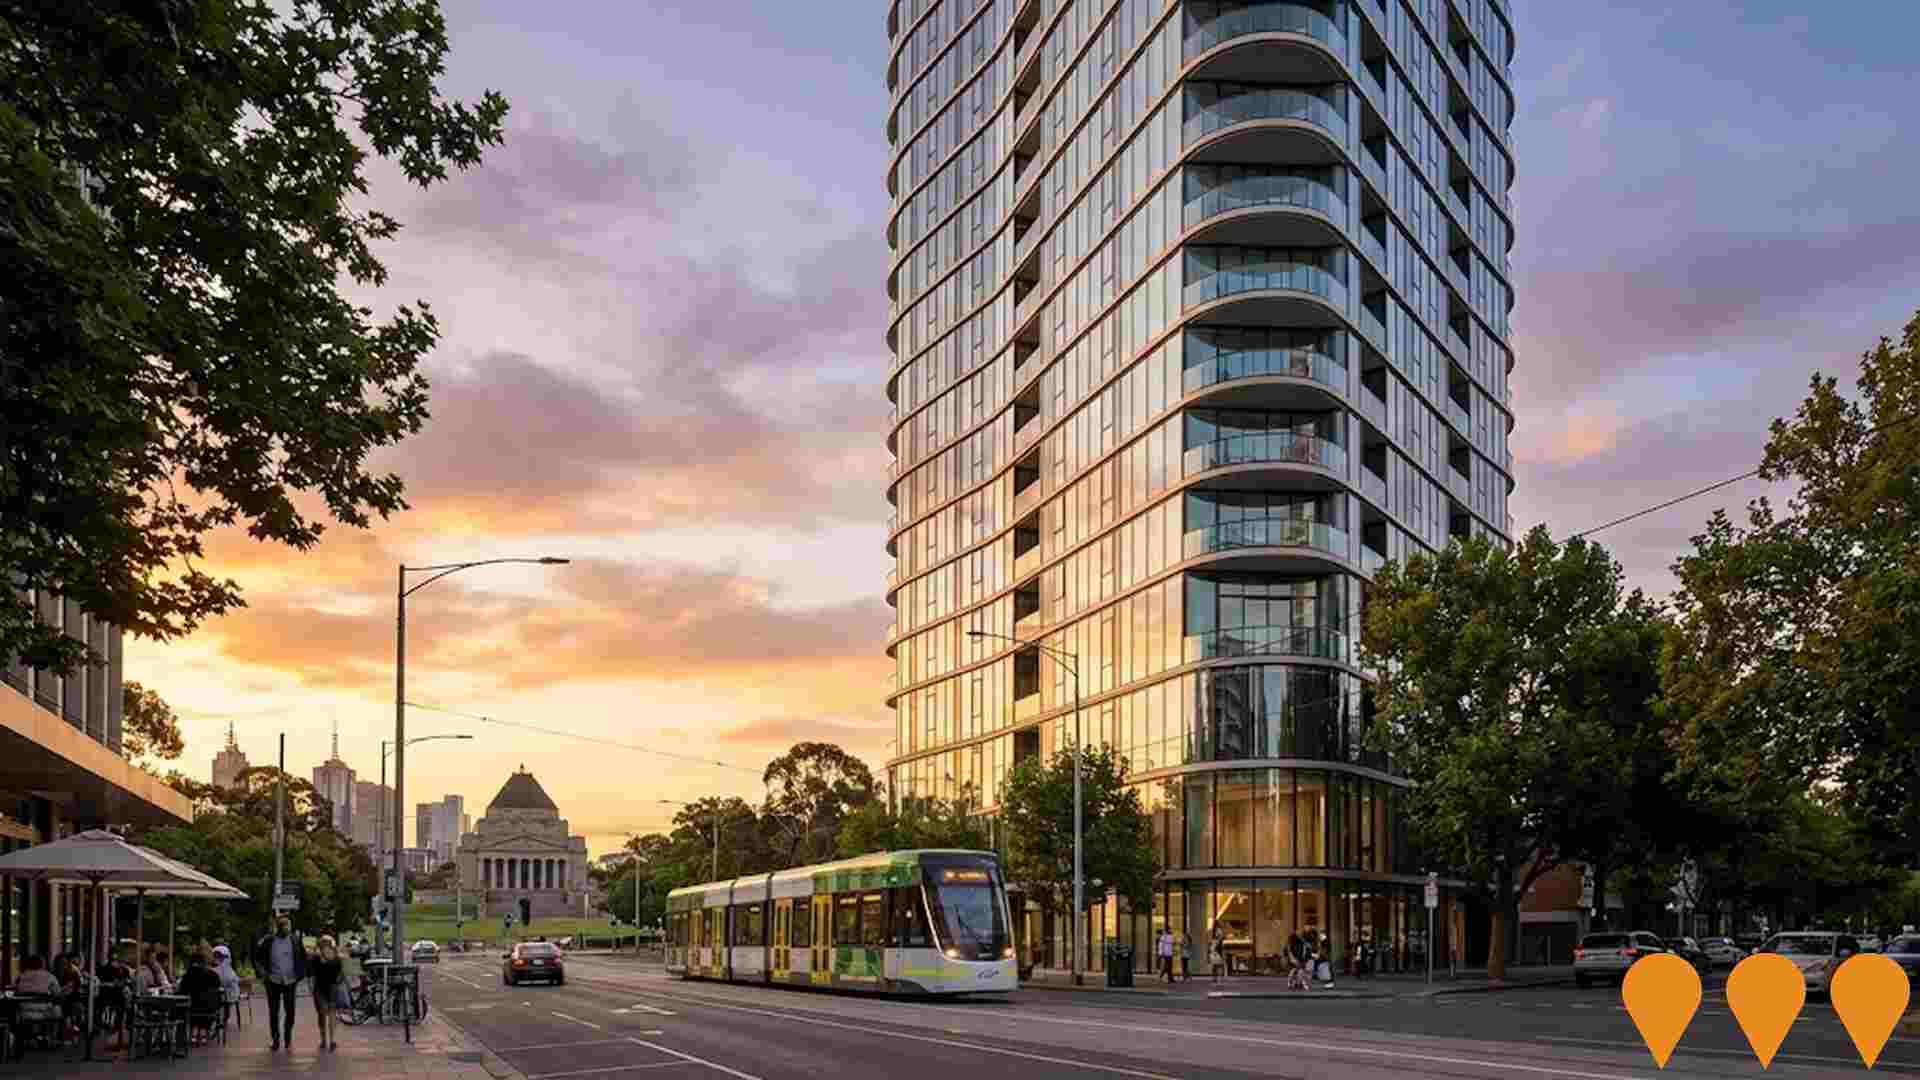
First Light
First Light is an under-construction luxury mixed-use apartment and hotel project at 28 Albert Road, South Melbourne. The scheme includes a boutique collection of 35 private residences, a 97-key Nu by YOO hotel, wellness facilities, pool, gym, concierge services, restaurants, and a pedestrian arcade linking the Domain Precinct near Anzac Station.
Kings Way, South Melbourne
Proposed $65 million, 19-storey premium commercial office tower designed by Elenberg Fraser. The project features luxury whole-floor tenancies, ground-floor food and beverage outlets, and basement parking with dedicated end-of-trip facilities. Positioned on a pentagon-shaped island site, the building offers views of Albert Park Lake and Port Phillip Bay. The development proceeded to VCAT review following a Port Phillip Council recommendation for refusal in 2022.
The Canopy on Normanby
The Canopy on Normanby is a 20-storey sustainable residential tower located in South Melbourne's Fishermans Bend precinct. Developed by Gamuda Land, the project features 213 apartments designed with biophilic principles, aiming for a 7.8-star NatHERS rating and 5-Star Green Star certification. The development includes a 3,000sqm public park featuring Melbourne's first urban Miyawaki forest, a rooftop onsen-inspired spa, geothermal heat pump systems, and extensive green facades and cascading gardens. Construction is being carried out by Crema Constructions.
Local South Melbourne
A 35 to 40-storey build-to-rent tower featuring 406 apartments, designed by LiFE Architecture with a facade inspired by aviation heritage. The project includes extensive amenities such as a wellness podium with a gym and yoga studio, co-working spaces, a pet wash bay, and ground-level commercial retail. It is fully electric and achieves net zero emissions, targeting completion in late 2026.

Future South Melbourne Structure Plan
The Future South Melbourne Structure Plan (2024-2044) is a comprehensive framework guiding the long-term transformation of South Melbourne. Implemented via Planning Scheme Amendment C219port, the plan rezones the City Road Industrial Triangle to Commercial 2, introduces four new Design and Development Overlays (DDO37-40) to manage building heights and design, and strengthens heritage protections for local precincts. Following a public Planning Panel hearing which concluded in April 2026, the project is currently in the final stages of assessment for formal adoption.
Bank Street Build-to-Rent Development
Approved 19-storey build-to-rent mixed-use development at 15-37 Bank Street, South Melbourne. The scheme comprises 355 rental apartments, including studios and one, two and three bedroom apartments, ground floor retail, 141 car spaces and resident amenities including coworking, gym and wellness areas, lifestyle spaces, heated pool, rooftop terrace and pet-friendly facilities. Local Residential acquired the permit-ready project from Hines, with 10 percent of dwellings designated as affordable housing.


9,451 residents of South Melbourne are employed, from a labour force of 10,084. Unemployment sits at 6.3%, with participation at 77.7%. Weighted for its industry mix, the area's sectors are forecast to grow about 7.2% nationally over five years. That reflects industry composition only and makes no allowance for local population growth, so in an area growing as fast as this one it understates the likely rise in local jobs. The working-day population is estimated at 24,166, about 166% of the resident population, so the area draws in more workers than it sends out. Unemployment and labour force come from ABS Small Area Labour Markets, updated quarterly; the industry and occupation profile is from the 2021 Census.
Detail
South Melbourne features a well-educated labor pool with pronounced concentration across the technology industry, a jobless rate of 6.3%, and an annual employment rise of 6.0% derived from aggregated statistical area figures by AreaSearch. In March 2026, employed locals numbered 9,451, with local joblessness tracking 1.5% higher than the 4.8% recorded across Greater Melbourne, while labor participation registered an elevated 77.7% against the regional benchmark of 70.1%. At the time of the Census, 51.9% of local employees carried out their roles remotely from home, a figure influenced by prevailing Covid-19 restrictions.
Major sectors employing local residents include professional & technical, health care & social assistance, and finance & insurance. Specialization is particularly elevated in professional & technical fields, where the local workforce share reaches 2.0 times regional concentrations. In contrast, health care & social assistance comprises a smaller portion locally at 10.2%, compared to the broader metropolitan benchmark of 14.2%. Registering 2.0 workers for every resident during the Census, the locality serves as a major commercial center that provides more positions than it has resident workers, pulling in commuters from surrounding areas. Reviewing combined SALM and ABS datasets across surrounding statistical boundaries, AreaSearch notes that over the 12-month period, local jobs expanded by 6.0% while the workforce grew by 6.4%, lifting unemployment by 0.3 percentage points. Over the equivalent timeframe, Greater Melbourne recorded a 2.1% job gain alongside a 2.3% labor force expansion, resulting in a 0.2 percentage point rise. Long-term industry trajectories from Jobs and Skills Australia as of Mar-26 provide additional context regarding future workforce requirements in South Melbourne. Evaluated across five and ten-year horizons against the existing workforce distribution, these projections illustrate shifting sector requirements. Nationwide job creation is projected at 6.6% over five years and 13.7% over ten years, though sector trajectories vary markedly; aligning these rates with South Melbourne's specific industry distribution points to prospective local job growth of 7.2% over five years and 14.4% over ten years (note that this reflects a basic weighted distribution for context rather than localized demographic forecasts).
Frequently Asked Questions - Employment
Median household income in South Melbourne is $2,101 a week (about $109,000 a year), with median personal income at $1,307 a week. ATO records put median taxable income at $68,864 a year against an average of $105,821. The average runs 54% above the median, a wider spread than most areas and a sign of a concentrated group of high earners. Household income is from the 2021 Census; taxable income is from ATO Taxation Statistics for the latest financial year available, indexed forward using the ABS Wage Price Index.
Detail
Postcode-level ATO data aggregated by AreaSearch for financial year 2023 indicates that taxpayers in the suburb of South Melbourne registered a median income of $68,864 and an average income of $105,821. These figures sit well above nationwide norms, comparing favorably to the Greater Melbourne benchmarks of $57,688 and $75,164. Factoring in Wage Price Index appreciation of 9.62% since financial year 2023, updated estimates reach approximately $75,489 (median) and $116,001 (average) as of March 2026. The 2021 Census placed individual earnings at the 94th percentile across Australia ($1,307 weekly). The largest income segment is the $1,500 - 2,999 tier, containing 29.9% of residents (4,342 people), mirroring the regional rate of 32.8%.
Local affluence is further highlighted by 34.1% of households earning more than $3,000 per week, underpinning elevated retail and discretionary activity. Residential accommodation absorbs 17.1% of income, yet robust earnings maintain disposable funds at the 70th percentile, positioning the neighborhood in the 9th decile on the SEIFA income index.
Frequently Asked Questions - Income
South Melbourne had 5,547 occupied dwellings at the 2021 Census, 5% detached houses and 59% apartments. 24% are owned with a mortgage, 56% rented and 20% owned outright. At that Census the median rent was $421 a week and the median mortgage repayment $2,200 a month, a total housing cost higher than 84% of areas nationally. Rent absorbs 20.0% of household income here and mortgage repayments 24.2%. Dwelling stock, tenure and housing costs are 2021 Census measures — the only source that counts dwellings at this boundary size.
Detail
According to the most recent Census, the residential fabric in South Melbourne consisted of 4.7% detached houses alongside 95.3% other dwelling formats such as terraces, apartments, and alternative structures, differing from the Melbourne metro split of 67.9% houses and 32.1% other dwellings. Outright home ownership stood at 19.6%, trailing broader metropolitan levels, while mortgaged residences accounted for 24.0% and rental accommodation made up 56.4%. Median monthly mortgage commitments were $2,200 locally versus $2,000 across Melbourne metro, with median weekly rents reaching $421 compared to the metropolitan standard of $390. Across Australia, local mortgage payments sit substantially higher than the national baseline of $1,863, with rental costs similarly exceeding the nationwide benchmark of $375.
Frequently Asked Questions - Housing
South Melbourne counted 5,547 households at the 2021 Census, an estimated 6,977 today, averaging 1.9 people each. 15% are couples with children, fewer than in 94% of areas nationally, against 28% couples without children. 43% of households are people living alone, and families average 0.9 children. Household and family composition is measured only by the Census, so these are 2021 figures.
Detail
Family units constitute 51.1% of all local households, divided between couples without children (27.8%), couples with children (15.2%), and single parent families (6.9%). Non-family living arrangements make up the remaining 48.9%, featuring lone person households at 43.1% and group households at 5.8%. The typical household size is 1.9 people, lower than the Greater Melbourne standard of 2.6.
Frequently Asked Questions - Households
56.9% of adults in South Melbourne hold a university qualification, including 35.8% with a bachelor degree and 16.5% with postgraduate qualifications. A further 9.4% hold a vocational qualification. 5 schools serve the area, with 910 enrolment places and an average ICSEA of 1,029 against a national benchmark of 1,000. Qualifications come from the 2021 Census; school enrolments, ICSEA and results come from ACARA's current release.
Detail
South Melbourne residents demonstrate high educational qualifications relative to state and national standards, with 56.9% of individuals aged 15+ holding a tertiary qualification compared to 33.4% in VIC and 30.4% across Australia. This educational profile positions the locality well for participation in knowledge-intensive sectors. Bachelor degrees represent the largest proportion at 35.8%, followed by postgraduate degrees at 16.5% and graduate diplomas at 4.6%. Technical and vocational credentials represent 20.0% of qualifications among residents aged 15+, consisting of advanced diplomas (10.6%) and certificates (9.4%). Participation in study is substantial across the community, with 26.7% of locals actively enrolled in educational courses.
This comprises 8.9% attending tertiary institutions, 6.3% in primary education, and 5.0% undertaking secondary education.
Frequently Asked Questions - Education
Schools Detail
Public transport in South Melbourne reaches 45 stops on 11 routes, timetabled for about 7,100 services a week. The typical home sits about 140 m from its nearest stop. Trams carry the largest share of public transport commuters. Households keep an average of 0.5 vehicles. Stop and service counts are built from operators' published GTFS timetables and refresh with each timetable release; vehicle ownership is from the 2021 Census.
Detail
Public transport connectivity is supported by 45 active stops across South Melbourne, providing combined access to lightrail and buses. A network of 11 distinct routes operates across these stops to deliver 7,119 passenger services on a weekly basis. Commuter convenience is high, with the typical resident residing 142 meters from their nearest transit node. Due to its residential character, outward travel is common, with private cars accounting for 50% of journeys, walking representing 20%, and rail transit comprising 6%. Average vehicle availability is 0.5 per dwelling, tracking below metropolitan figures, while 51.9% of workers operated from home during the 2021 Census under prevailing pandemic circumstances.
Transit services maintain an average volume of 1,017 trips per day across all available routes, providing approximately 158 weekly trips at each individual transit stop.
Frequently Asked Questions - Transport
Transport Stops Detail
72.3% of residents in South Melbourne report no long-term health condition. 5.3% need daily assistance with core activities, and 68.5% hold private health cover. The standardised death rate runs at 4.9 per 1,000 residents. Health conditions, assistance needs and insurance are 2021 Census measures; the death rate comes from current ABS releases.
Detail
South Melbourne records favorable health statistics across all age cohorts according to AreaSearch research on mortality and chronic condition rates, paired with a remarkably high private health insurance rate of approximately 68% (9,942 people). This coverage level substantially exceeds the Greater Melbourne benchmark of 56.7% and the Australian national average of 55.7%. Asthma and mental health issues represent the most prevalent diagnosed conditions among residents, reported by 7.3% and 9.2% of the local population respectively, whereas 72.3% reported no chronic medical diagnoses, closely matching the 72.6% rate recorded across Greater Melbourne.
Residents under the age of 65 experience better than typical health metrics. Older residents aged 65 and over comprise 14.1% of the population (2,048 people), sitting below the Greater Melbourne proportion of 15.1%, with health measures for this senior cohort tracking above average and broadly reflecting national distributions.
Frequently Asked Questions - Health
37.4% of South Melbourne residents were born overseas and 25.3% speak a language other than English at home, more culturally diverse than 76% of areas nationally. The largest reported ancestries are English (24.2%) and Australian (17.2%). Ancestry, language and country of birth are counted only by the Census, so these are 2021 figures.
Detail
The local community exhibits strong multicultural features, with 37.4% of residents born abroad and 25.3% speaking a language other than English in their households. Christianity is the most widely followed faith, practiced by 37.2% of the population. The most prominent deviation from regional averages occurs with Judaism, which represents 1.2% of local residents compared to 1.0% across Greater Melbourne. Regarding ancestral background based on parents' birthplaces, the three most common heritages in South Melbourne are English (24.2%), Australian (17.2%), and Other (12.5%). Notable regional variations also appear among other ancestries: Russian represents 0.8% locally versus 0.4% regionally, French accounts for 0.9% compared to 0.5%, and Greek makes up 3.2% against the wider metropolitan figure of 2.7%.
Frequently Asked Questions - Diversity
The median resident of South Melbourne is 38. That is 1 year younger than at the 2021 Census. 33.9% of residents are aged 15 to 34. Age cohorts are not raw Census counts: the Census split is re-based to the latest ABS population estimates and state projections.
Detail
Demographically, South Melbourne leans heavily toward younger demographics. Adults in the 25 - 44 age bracket account for 42.6% of the population as at August 2026, exceeding the 32.1% share recorded across Greater Melbourne, while children and youth aged 0 - 24 represent 20.1% against 30.5% regionally. The estimated median age is 38 as at August 2026, a decline from 39 at the 2021 Census and 1 year older than the Greater Melbourne median of 37 recorded during that Census. Since that Census count, the proportion of 25 - 44 year olds has climbed from 39.0% to an estimated 42.6%.
This cohort is expected to generate the largest numerical expansion through to 2041, increasing by 3,194 (52%) to 9,382 residents. In relative percentage terms, mature adults and early retirees aged 45 - 64 will see the fastest growth, rising 90% to 6,422 residents.
Frequently Asked Questions - Age
Data & MethodBoundaries, Sources & Method for South Melbourne
9 of 14 data sections on this page were updated within the last 12 months — the newest current to Oct 2026.
Everything is aggregated to the Suburb (SAL) boundary shown above, on a 2021 Census baseline. Only 3 sections — housing, households and cultural diversity — still wait on the 2026 Census.
The ledger — source, cycle and currency by section
| Section | Source & update cycle | Currency |
|---|---|---|
| Updated within the last 12 months 9 sections | ||
| Population | ABS, GNAF, Geoscience Australia Annual (ABS ERP) | Aug 2026 2 months ago headline measures · 2021 Census baseline |
| Re-based to the ABS Estimated Resident Population (June 2025 release) and updated with new dwellings from GNAF address data. Current to Aug 2026, with the 2021 Census supplying the small-area baseline. | ||
| Age profile | ABS, Geoscience Australia, State governments Annual | Aug 2026 2 months ago headline measures · 2021 Census baseline |
| Age cohorts are re-based to the latest ABS population estimates and state projections, current to Aug 2026. Each cohort is held as a Census baseline and a current estimate. | ||
| Development & approvals | ABS, GNAF Monthly (ABS approvals) | Aug 2026 2 months ago headline measures · Jul 2026 baseline |
| Property sales & rents | Valuer General, Rental Board, ABS Weekly sales, quarterly rents | Oct 2026 this month headline measures · Sep 2026 baseline |
| Sales from the state Valuer General register, refreshed weekly, and rents from quarterly rental bond lodgements. Both are read live each time this page loads, current to Oct 2026. | ||
| Infrastructure projects | Infrastructure Australia, State agencies, Local governments Daily | Apr 2026 6 months ago all 20 projects tracked here |
| Project pipeline maintained continuously from Infrastructure Australia, state agencies, local government and public announcements. Records are added and revised daily; this area was last updated Apr 2026. | ||
| Employment | ABS, DEWR, JSA Quarterly (ABS SALM) | Mar 2026 7 months ago headline measures · 2021 Census baseline |
| Unemployment and labour force from ABS Small Area Labour Markets, current to Mar 2026. The growth outlook applies Department of Employment (now Jobs and Skills Australia) forecasts for all 19 industry divisions to the local industry mix, so it measures sector composition rather than local expansion and makes no allowance for population growth. Job demand comes from the same agency via its Internet Vacancy Index; industry and occupation structure from the 2021 Census. | ||
| Education | ABS, ACARA Annual (ACARA) | Sep 2026 last month headline measures · 2021 Census baseline |
| Transport | ABS, State Transport Departments Each timetable release | Jul 2026 3 months ago headline measures · 2021 Census baseline |
| Services & amenities | Provider directories, ACECQA Continuous | Sep 2026 last month all 14 measures |
| Annual and financial-year sources 2 sections | ||
| Income | ABS, ATO Annual (ATO) | FY 2023 3 years ago headline measures · 2021 Census baseline |
| ATO taxable income statistics for FY 2023, indexed forward using the Wage Price Index. Census household income provides the distribution detail. | ||
| Health | ABS, ATO Annual | 2024 2 years ago headline measures · 2021 Census baseline |
| Census-measured — next update: 2026 Census 3 sections No more current small-area source exists for these, so they are labelled as Census-measured rather than implied to be current. | ||
| Housing | ABS 5-yearly (Census) | 2021 Census next update 2026 all 30 measures |
| Households | ABS 5-yearly (Census) | 2021 Census next update 2026 all 18 measures |
| Cultural diversity | ABS, Geoscience Australia 5-yearly (Census) | 2021 Census next update 2026 all 44 measures |
"Currency" is the most recent release feeding that section. Where the Census supplies the structural baseline underneath a current headline figure, the row says so.
How the numbers are built
Population
The Census provides the small-area baseline, aggregated from mesh blocks to this boundary. It is then re-based to the ABS Estimated Resident Population (June 2025 release), and new dwellings built since Census night are counted from address data — 1,749 validated new addresses here. The headline figure is therefore a current estimate for Aug 2026, not a 2021 count (11,548 at the 2021 Census → 14,525 now). Annual growth rates are compound (CAGR), not simple averages.
Age profile
Cohort shares are not raw Census counts. Every cohort is held as a pair — the Census baseline and a current estimate — and the split is re-based using ERP and state population projections, current to Aug 2026. Median age is the Census median plus modelled change since. Charts that show both are labelled "2021 Census vs Current Estimate".
Property sales
Sourced from the state valuation authority's sales register — current, not Census, and refreshed weekly. Medians are calculated from settled transactions in the period shown; periods with very low transaction counts are flagged or suppressed, because a handful of sales can move a median substantially.
Rents
Derived from state rental bond lodgement data, by dwelling type and bedroom count. Bonds are lodged at the start of a new tenancy, so this reflects new lettings, not the whole rented stock.
Development & infrastructure
Building approvals come from current ABS releases; development applications are collected from council and state planning portals; the infrastructure pipeline is compiled from Infrastructure Australia and local government sources. Applications are matched to this boundary by address or coordinates, so very recent lodgements may not yet appear.
Employment & income
Industry and occupation structure comes from the Census, but the headline labour-market indicators do not. Unemployment and labour force are derived from ABS Small Area Labour Markets (quarterly). The employment outlook applies Department of Employment forecasts for all 19 industry divisions to this area's own industry mix (the agency is now Jobs and Skills Australia), as does the Internet Vacancy Index used for job demand. Because it is weighted on industry composition alone, that outlook carries no allowance for local population growth — in fast-growing areas the real rise in local jobs will typically be higher. Income combines Census household income with ATO taxable-income statistics for FY 2023, indexed forward using the Wage Price Index.
Education, transport & amenities
School enrolments, ICSEA and performance come from ACARA's current release, not the Census. Public transport stops and service frequency are derived from GTFS timetable feeds published by state transport departments. Services and amenities are proximity and count scores built from provider directories, refreshed on their own cycle. The Census contributes only the travel-to-work and qualification measures.
Rankings and benchmarks. Where we rank this area, the comparison set is every area of the same boundary type — suburbs against suburbs, SA2s against SA2s. Benchmarks compare this area against its greater capital city region and the national figure for the same measure and period.
Limits worth knowing. Small areas carry larger error margins, and the ABS introduces small random adjustments to Census counts to protect confidentiality — so totals may not sum exactly. Estimates re-based from regional data describe the area's expected trajectory, not a direct count of it. Figures are indicative for research and are not financial, planning or valuation advice.
Cross-check us. The Census baseline for this boundary is at ABS 2021 Census QuickStats (SAL22310). QuickStats reports 2021 only — the figures on this page are more current wherever the ledger shows a later date.