Chart Color Schemes
This analysis uses ABS Statistical Areas Level 2 (SA2) boundaries, which can materially differ from Suburbs and Localities (SAL) even when sharing similar names.
SA2 boundaries are defined by the Australian Bureau of Statistics and are designed to represent communities for statistical reporting (e.g., census and ERP).
Suburbs and Localities (SAL) represent commonly-used suburb/locality names (postal-style areas) and may use different geographic boundaries. For comprehensive analysis, consider reviewing both boundary types if available.
est. as @ -- *
ABS ERP | -- people | --
2021 Census | -- people


Curious about local property values? Filter the chart to assess the volume and appreciation (including resales) trends and regional comparisons, or scroll to the map below view this information at an individual property level.


Find a Recent Sale

Sales Detail
Melbourne CBD - North has an estimated 24,306 residents, up from 16,870 at the 2021 Census — a change of 7,436 people, or 44.1%. Growth has averaged 4.9% a year over five years, faster than 97% of areas nationally. Overseas migration accounts for 97.9% of that increase. That puts 43,404 residents on each square kilometre. Population is estimated from ABS Estimated Resident Population releases and GNAF address data, re-based from the 2021 Census and updated annually.
Detail
According to evaluations by AreaSearch, the resident count for Melbourne CBD - North stands at approximately 24,306 as of Aug 2026. Compared to the 16,870 people recorded in the 2021 Census, this represents a expansion of 7,436 people (44.1%). The update draws upon the ABS estimated resident population of 24,296 as of June 2025 alongside 86 validated new addresses documented following the Census date. With a density of 43,403 persons per square kilometer, the locality sits among the top 10% of areas assessed across the country by AreaSearch, placing local land at a premium.
The locality's 44.1% increase since the 2021 census outpaced the broader state (9.5%) and national benchmarks, establishing it as a regional growth frontrunner. Net overseas migration served as the primary catalyst, generating roughly 97.9% of the overall population additions in recent periods. Projections for each SA2 published in 2024 by ABS/Geoscience Australia, anchored to 2022 as a base year, are utilised by AreaSearch. In instances where an SA2 lacks coverage, VIC State Government Regional/LGA projections issued in 2023 are integrated via a weighted aggregation methodology shifting LGA growth to SA2 boundaries. Age-bracket growth rates derived from these models are further applied to all localities for the period spanning 2032 to 2041. Future demographic modelling places the district in the top quartile nationally for expansion, with current annual ERP figures pointing to a gain of 9,413 persons to 2041, translating to an overall growth rate of 38.7% across the 16 years.
Frequently Asked Questions - Population
569 new dwellings have been approved in Melbourne CBD - North over the past five years, an average of 113 a year. That places the area in the 99th percentile for residential development activity nationally, about 5 approvals per 1,000 residents a year. Of the 114 dwellings approved in the latest reporting year, 0% were detached houses and the rest townhouses or apartments. Figures come from ABS building approvals aggregated to this SA2 boundary and are updated monthly as the ABS releases them.
Detail
Residential building consents in Melbourne CBD - North have averaged roughly 113 new homes annually, totalling 569 homes approved across the past 5 financial years (between FY-22 and FY-26). Over this same span of the past 5 financial years (between FY-22 and FY-26), an influx averaging 9 people per year for every home completed has created substantial demand pressures against supply, a dynamic that typically fuels price increases and heightened buyer interest. The mean value of approved dwellings stands at $633,000, pointing toward an emphasis on higher-end, upmarket residential construction.
Concurrently, commercial building approvals reached $76.9 million this financial year, underscoring notable local business investment. Per capita building activity in Melbourne CBD - North trails the broader metropolitan benchmark considerably, sitting 71.0% below regional average per person recorded for Greater Melbourne. While construction volume has picked up lately, the constrained pipeline of new stock provides continuous support for established property values. Furthermore, contemporary building work consists exclusively of attached dwellings. This orientation toward higher-density housing offers attainable price points for first-home buyers, downsizers, and investors alike. Projections from the newest AreaSearch quarterly estimate indicate Melbourne CBD - North will add 9,403 residents through to 2041. If residential building activity continues at its current trajectory, supply may fall short of demographic expansion, likely driving stronger competition among purchasers and sustaining upward pressure on prices.
Frequently Asked Questions - Development
Development applications around Melbourne CBD - North
SOURCE: Planning portals and council registers, compiled by AreaSearch. Distance & bearing measured from the suburb midpoint.
AreaSearch tracks 5 current infrastructure and development projects inside Melbourne CBD - North, worth an estimated $4.4 billion. A further 195 sit in the immediately surrounding suburbs, taking the tracked pipeline within reach of the area to $93.9 billion. 65 are already under construction and 62 are due for completion within three years. The pipeline spans residential development, communities, precincts & urban renewal and business parks & technology hubs. Records are compiled from Infrastructure Australia, state agencies, council planning portals and public announcements, reviewed and updated daily, then ranked by proximity, construction stage, completion horizon and project scale.
Detail
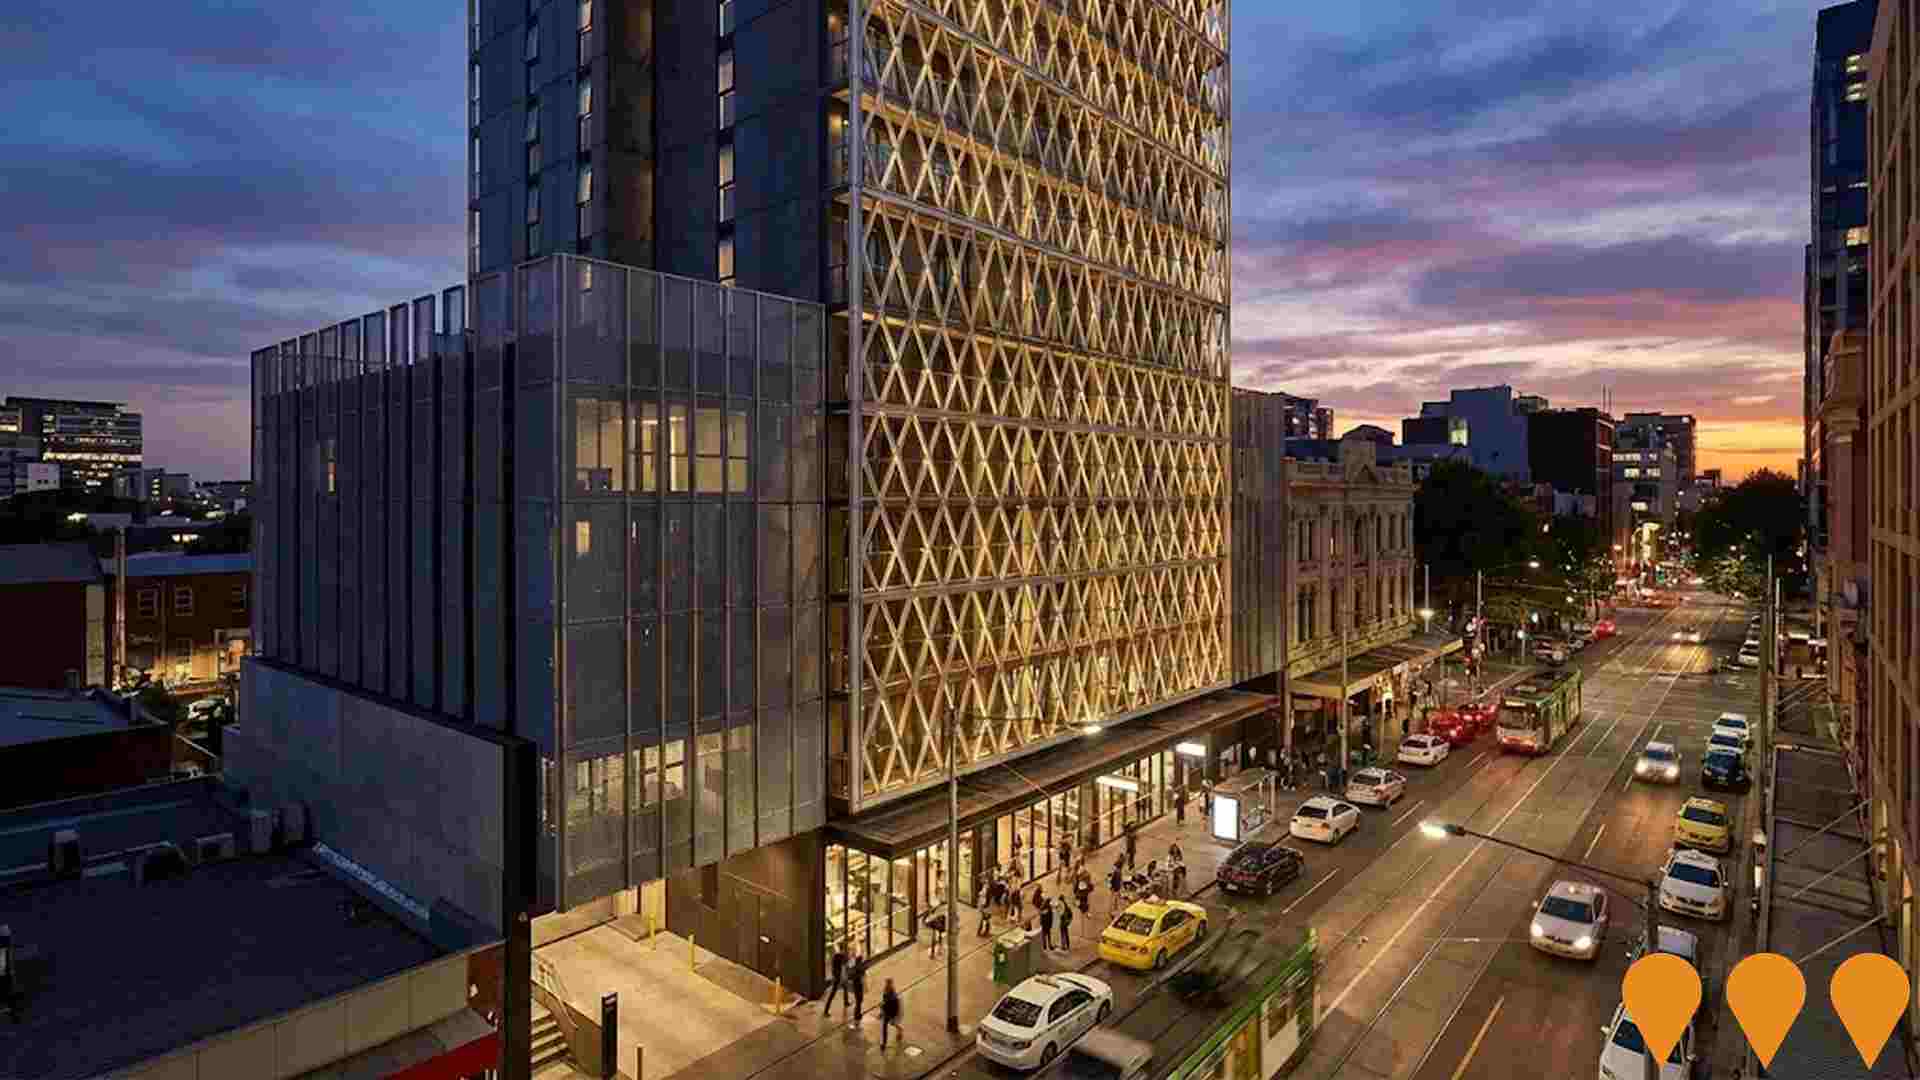
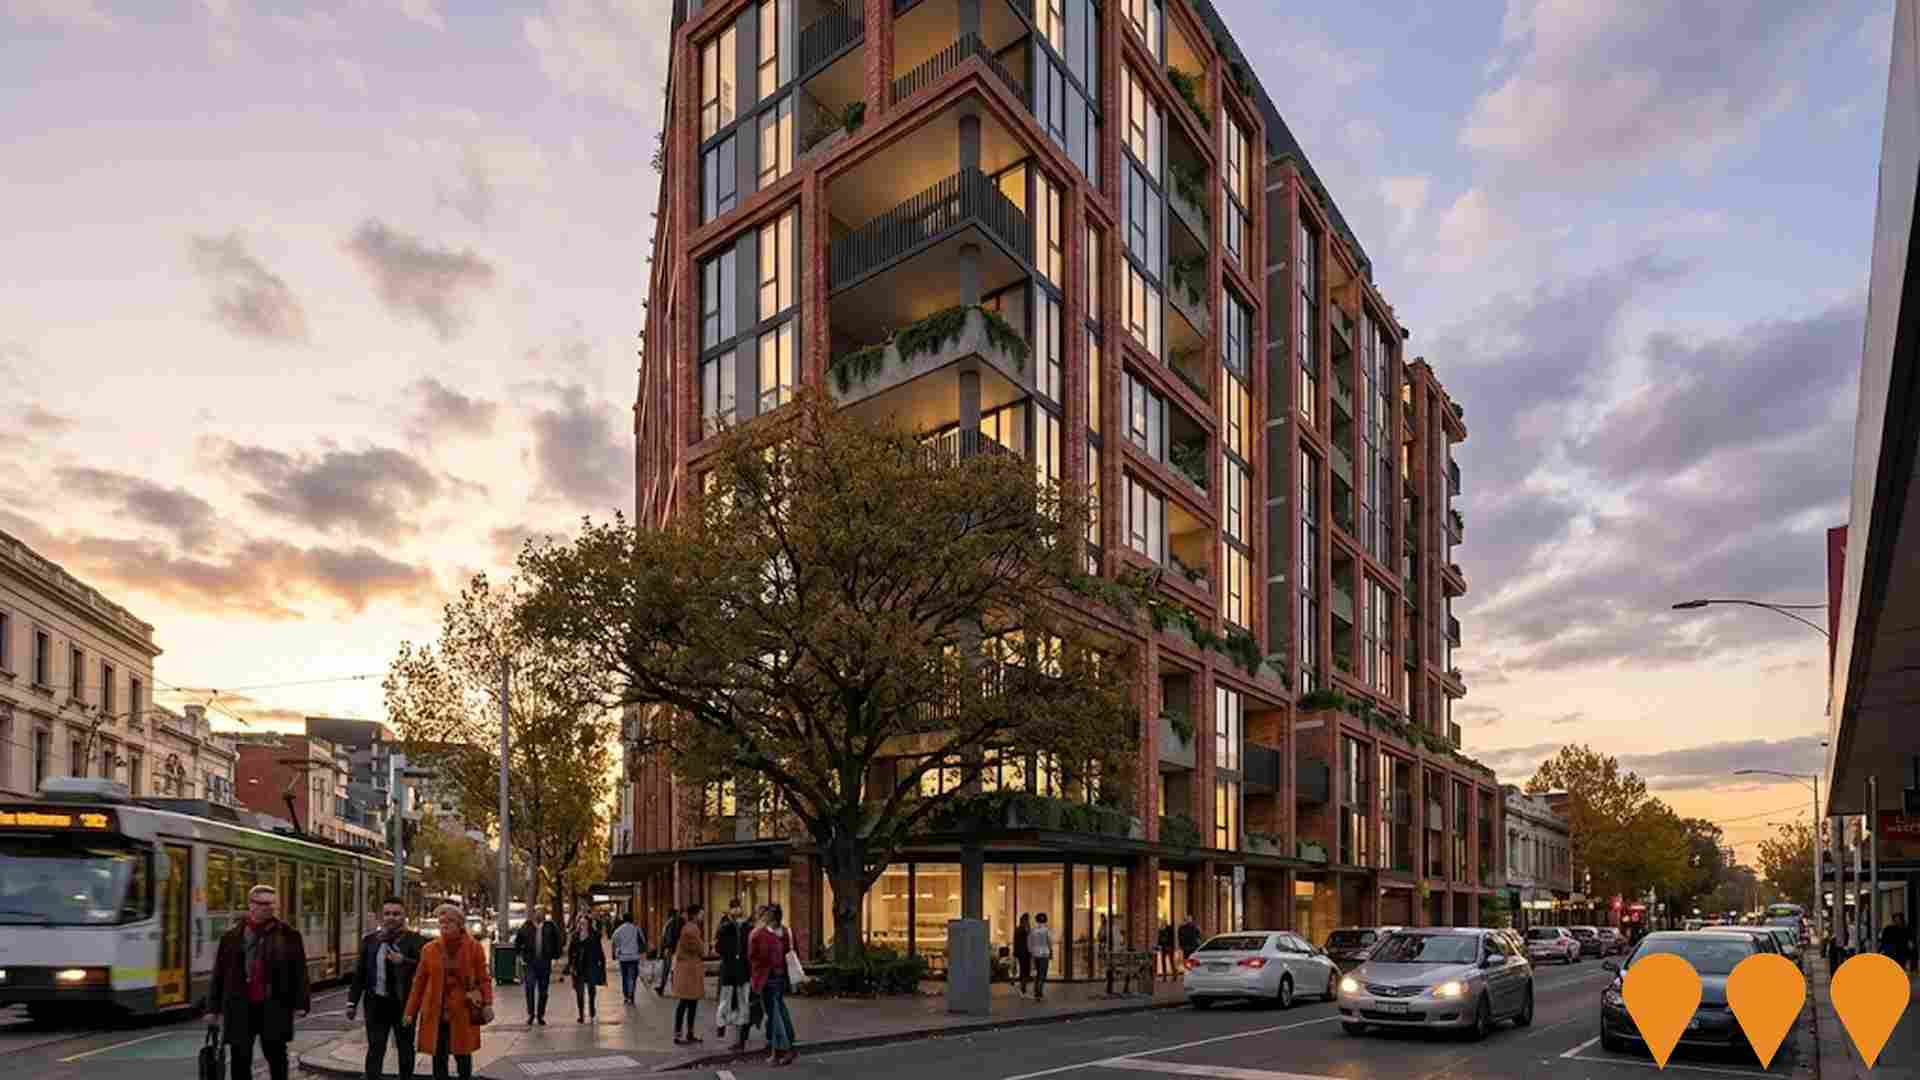
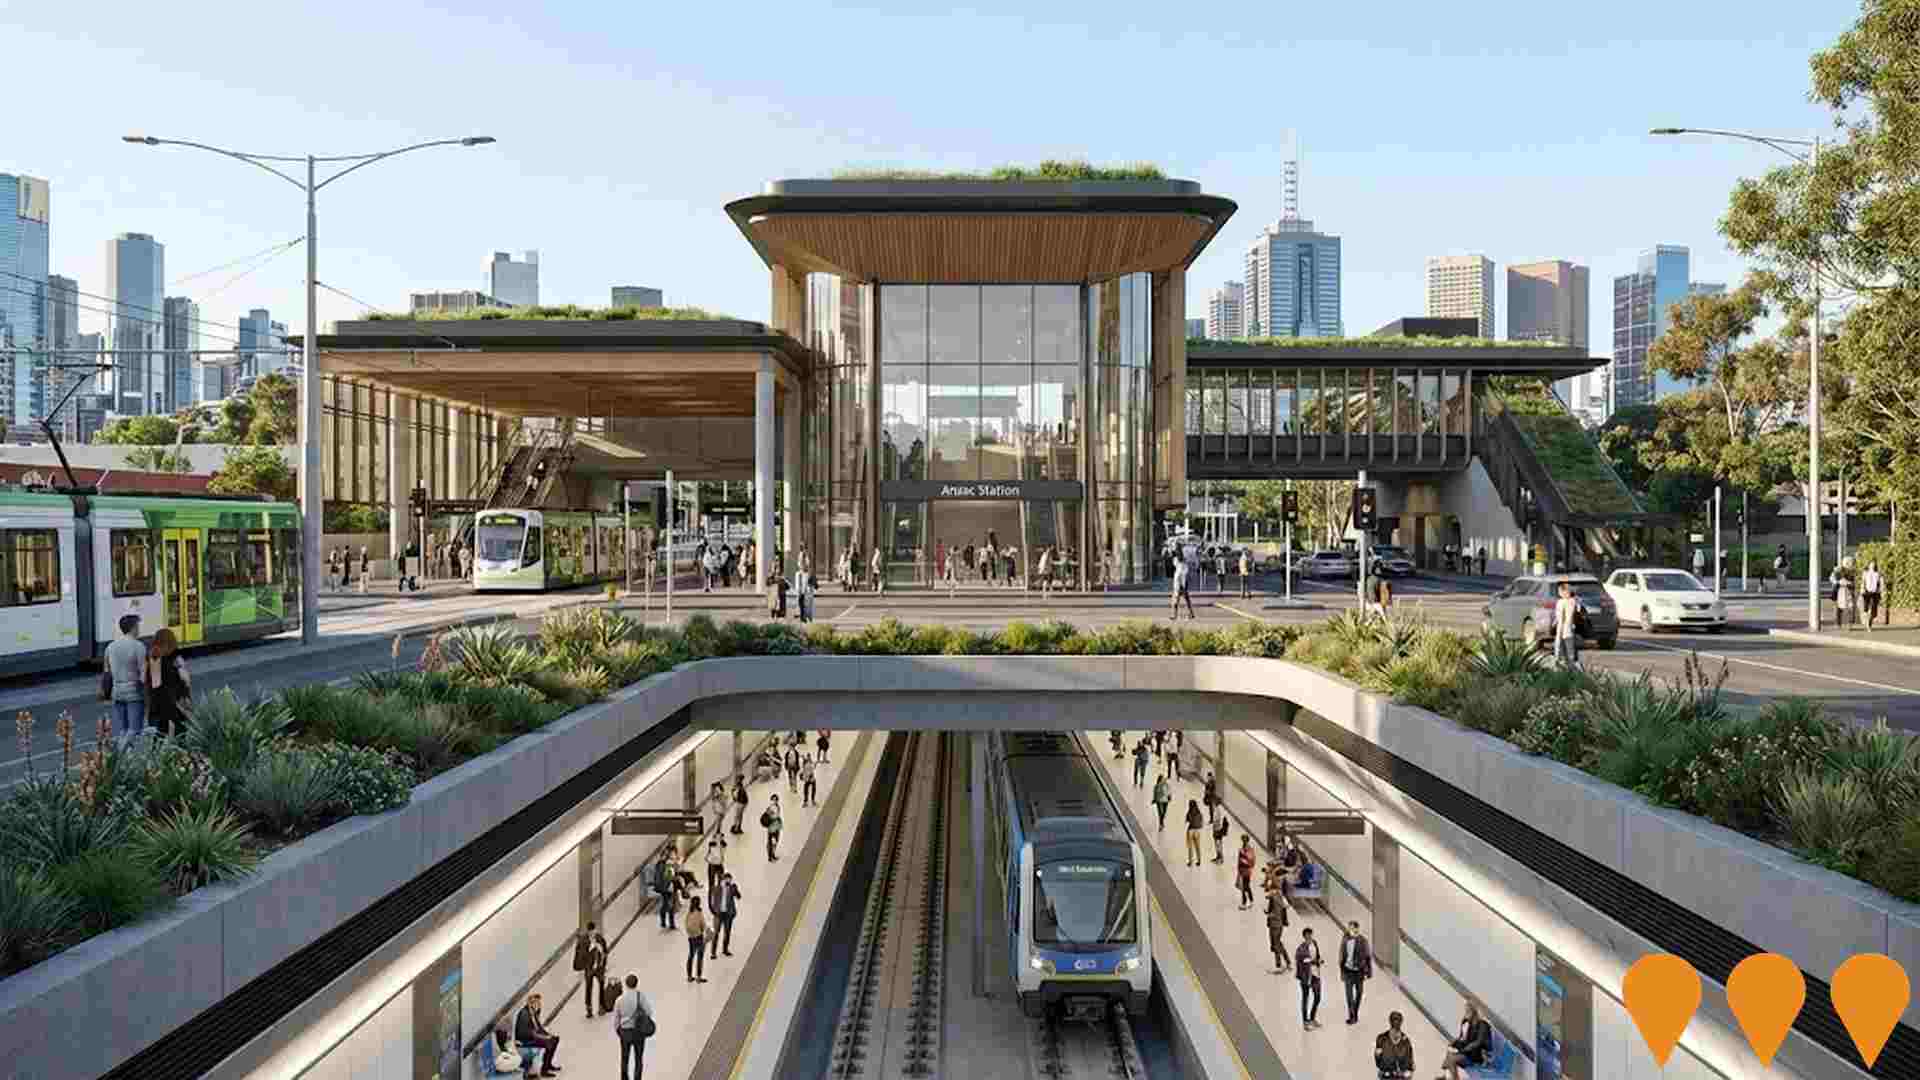
Major infrastructure developments, planning schemes, and capital works play a pivotal role in shaping local performance. AreaSearch has pinpointed a total of 19 projects expected to influence the locality. Prominent initiatives include the Queen Victoria Market Precinct Renewal, Gurrowa Place - QVM Southern Precinct, Queens Place, and the Level Crossing Removal Project, with the most relevant developments detailed below.
Professional plan users can use the search below to filter and access additional projects.
INFRASTRUCTURE SEARCH
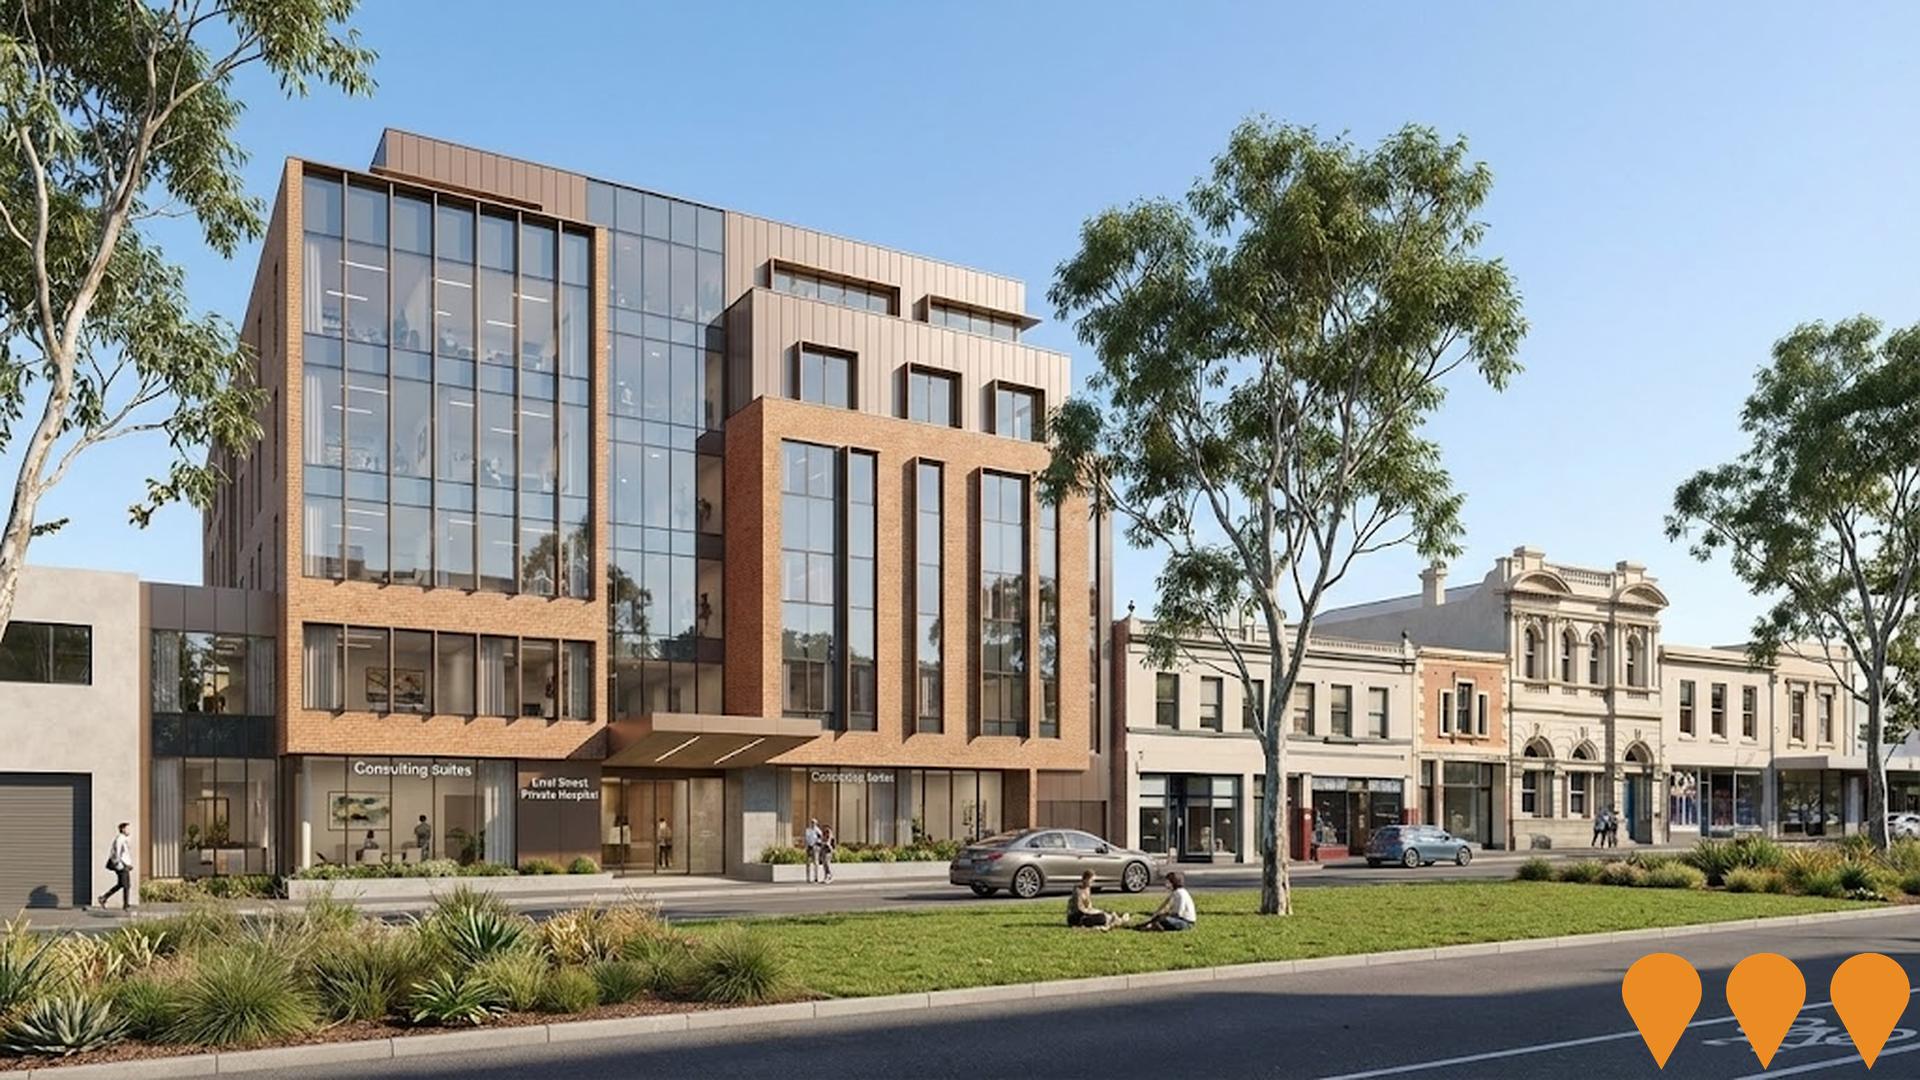
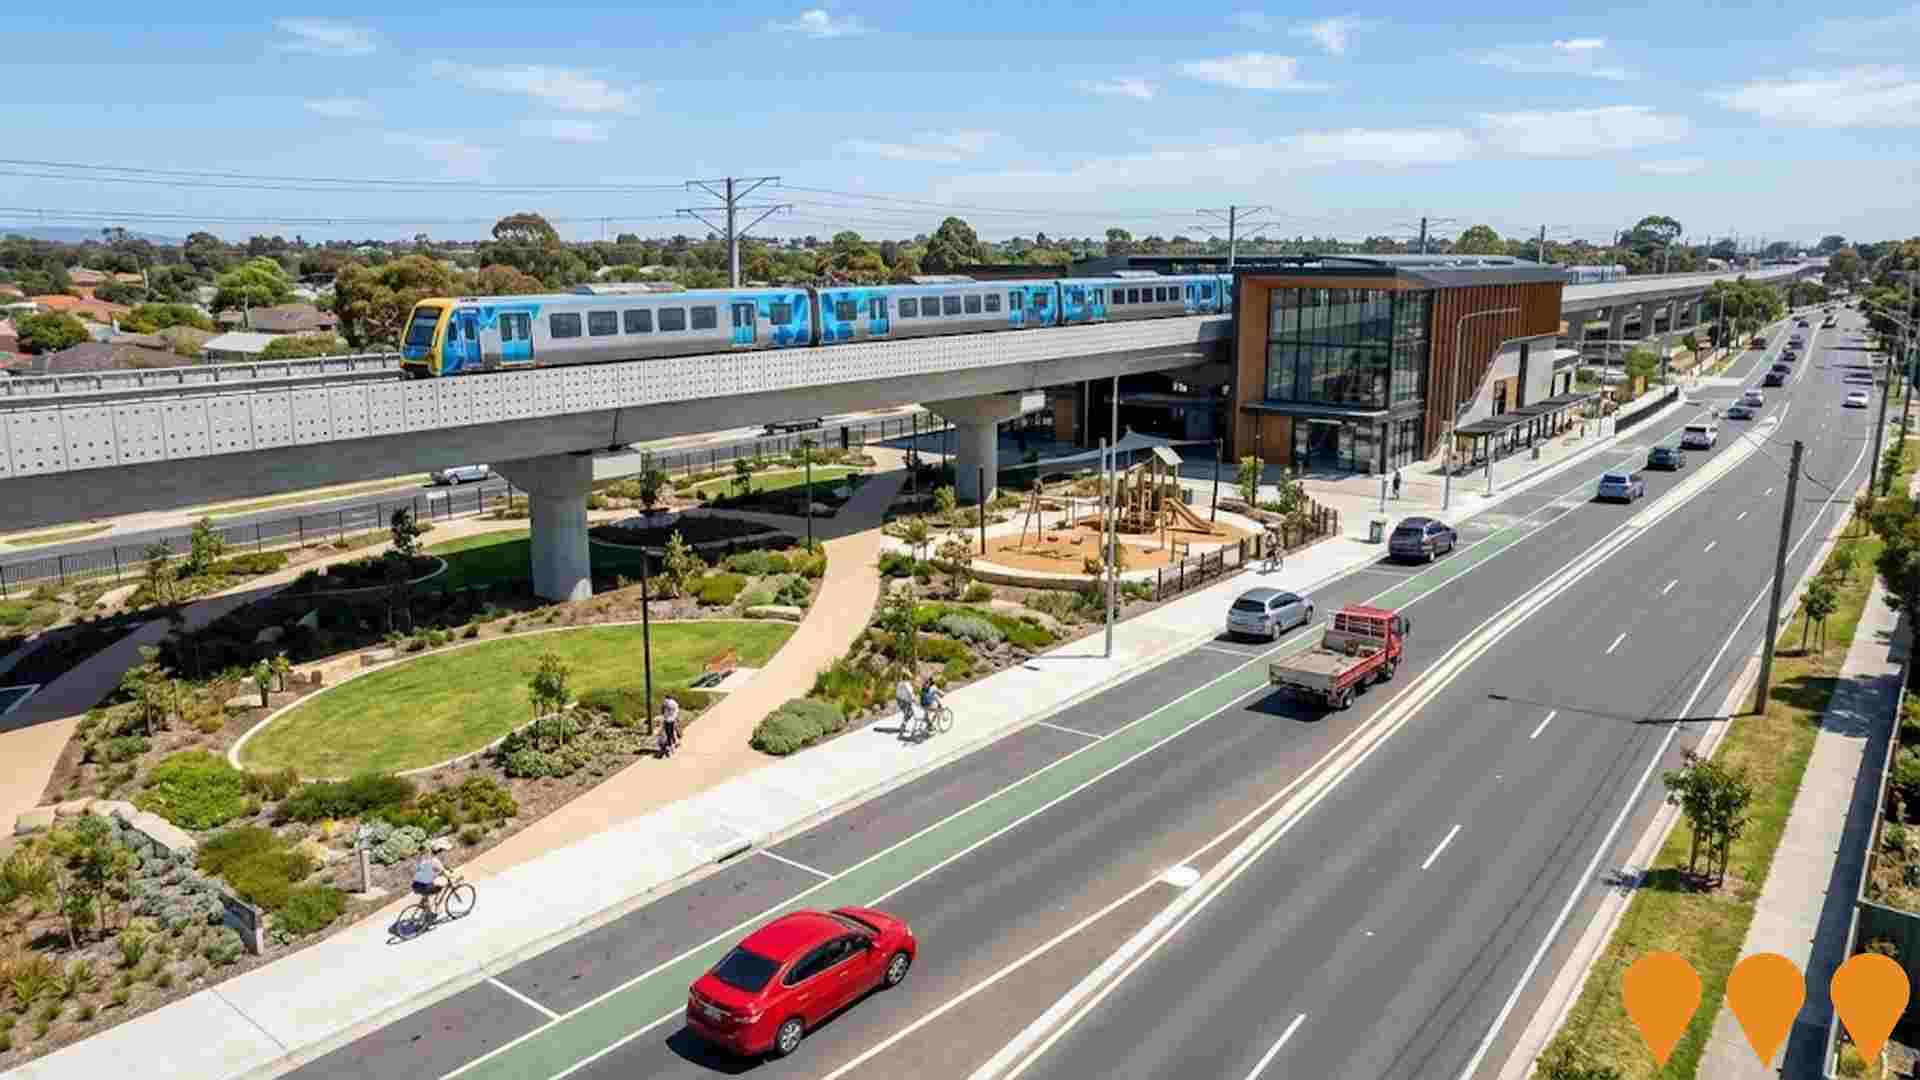
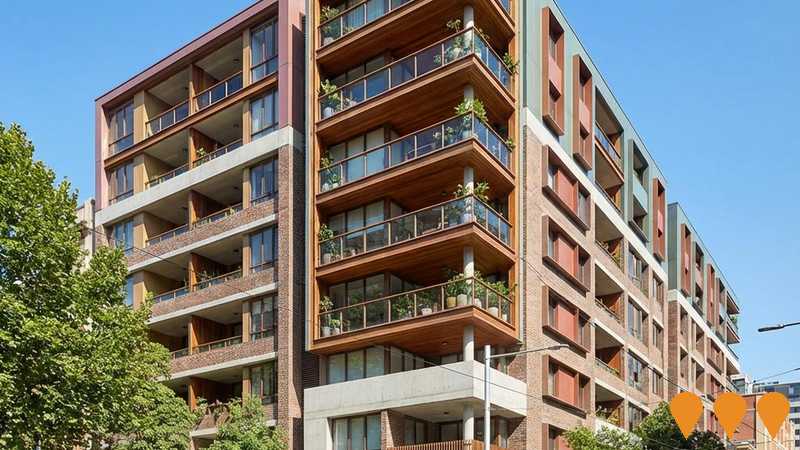
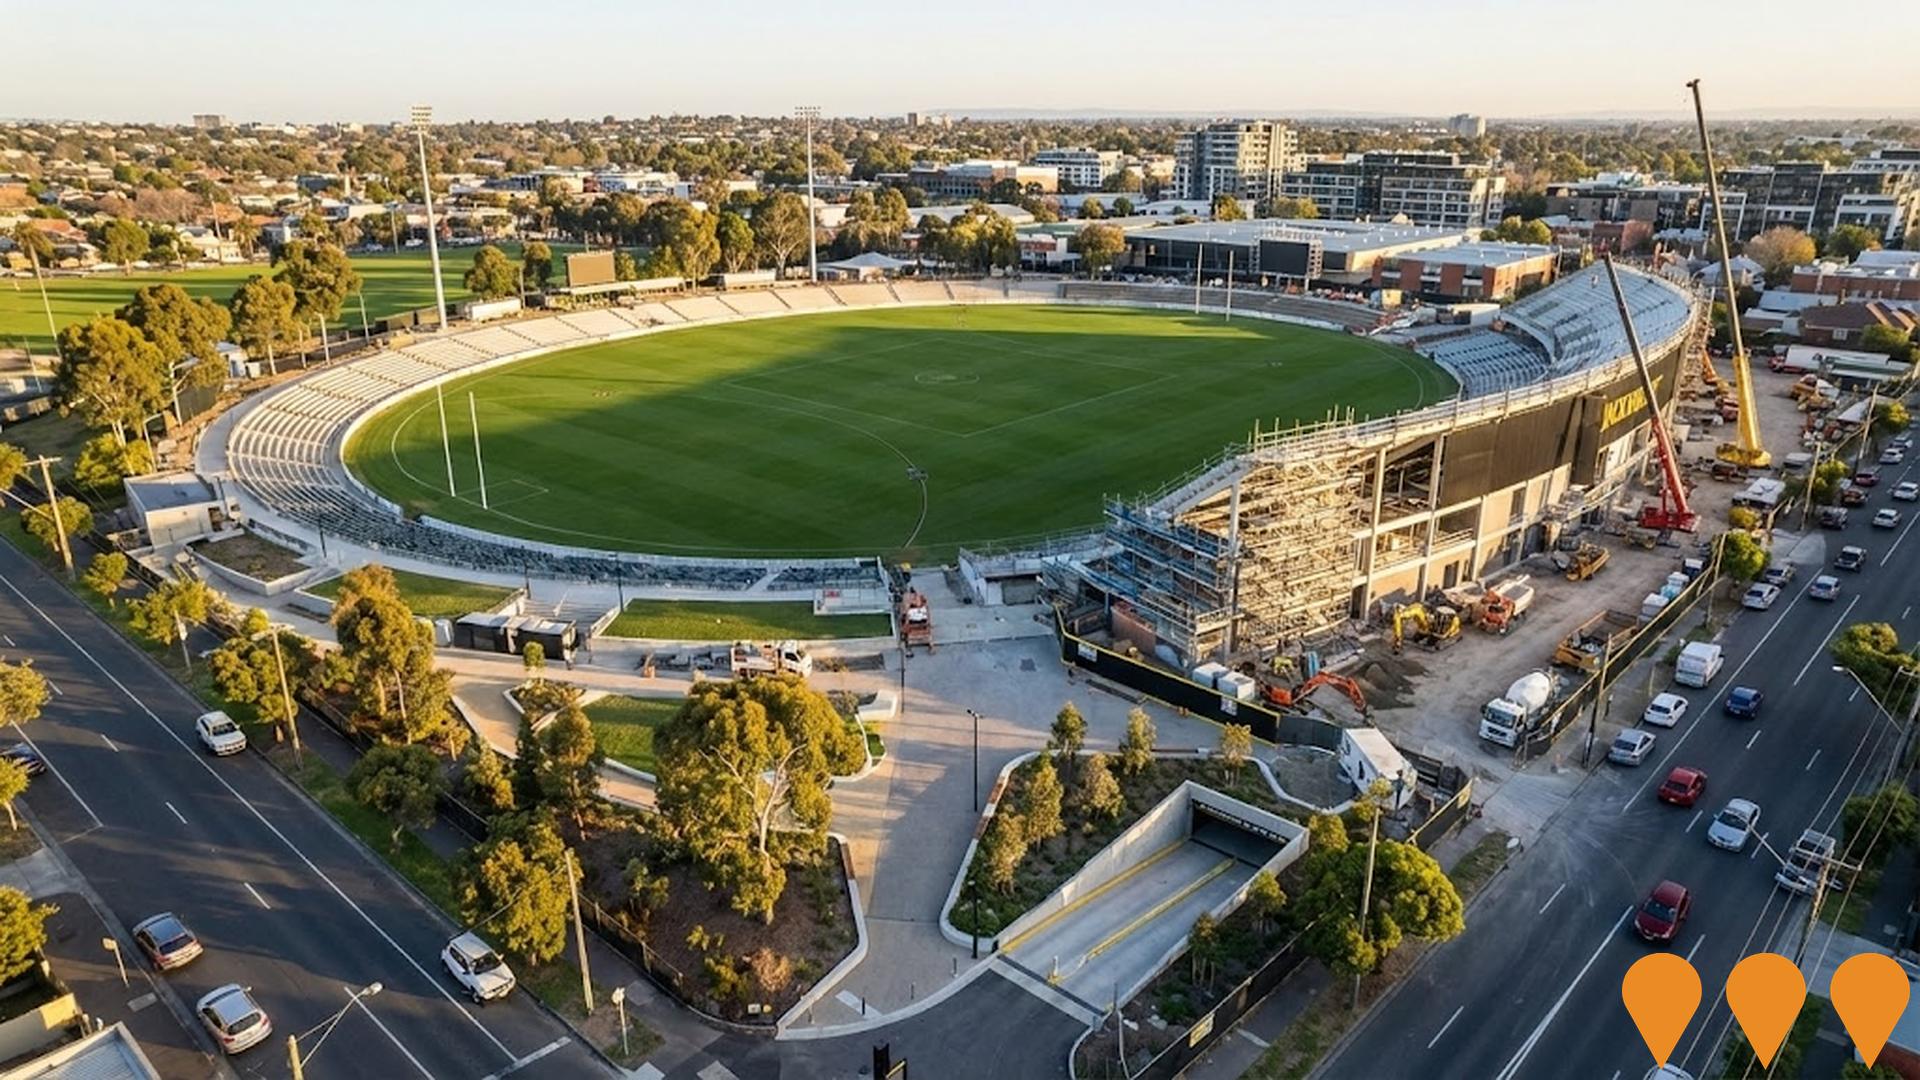
 Denotes AI-based impression for illustrative purposes only, not to be taken as definitive under any circumstances. Please follow links and conduct other investigations from the project's source for actual imagery. Developers and project owners wishing us to use original imagery please Contact Us and we will do so.
Frequently Asked Questions - Infrastructure
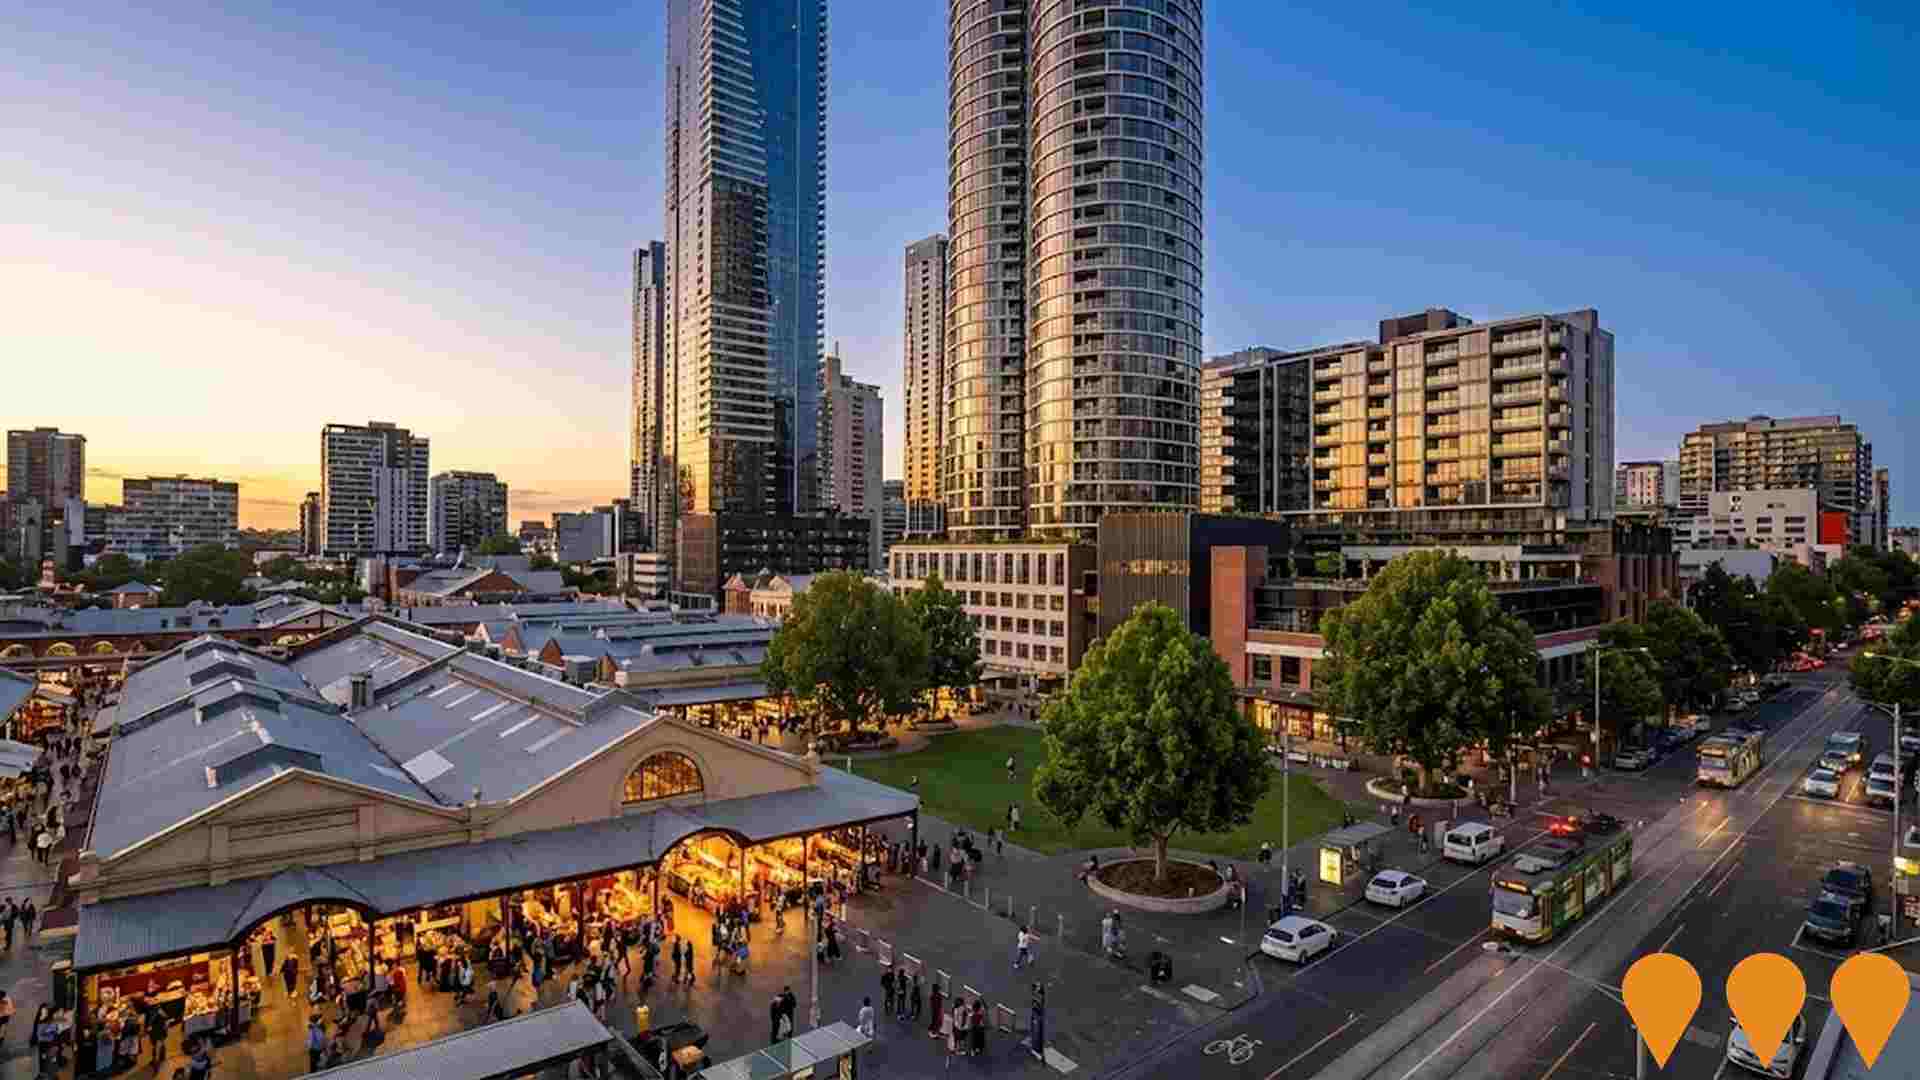
Queen Victoria Market Precinct Renewal
A transformative multi-stage program to modernize Australia's largest 19th-century market. The flagship southern precinct, Gurrowa Place, is a $1.7 billion mixed-use development delivered by Lendlease and Scape. It features three towers providing build-to-rent apartments, student accommodation, and affordable housing. Key elements include the 1.8-hectare Market Square public park replacing the current open-air car park, restoration of the heritage Franklin Street Stores into retail and hospitality, and a new 220-space basement car park. Heritage shed restorations and core trader facilities were largely completed by 2024, with site works for the southern towers commencing in May 2026.
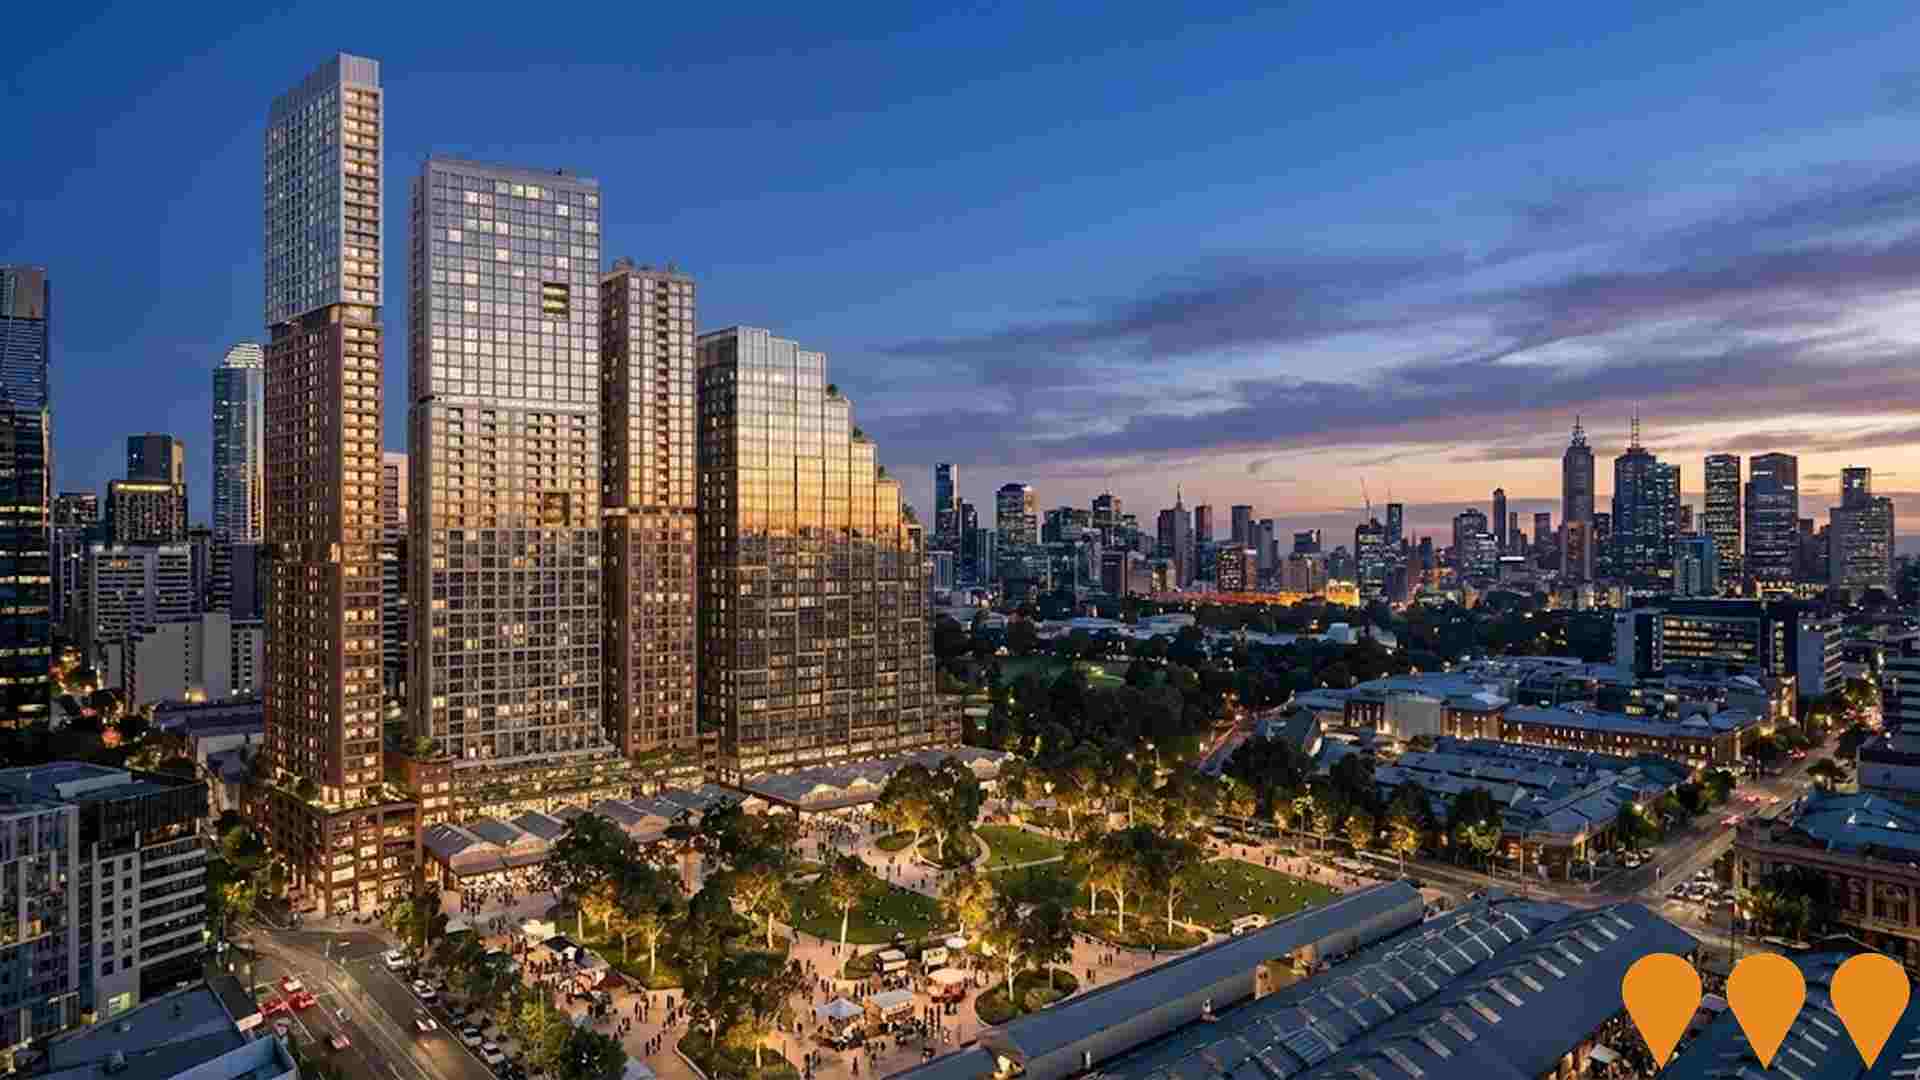
Gurrowa Place - QVM Southern Precinct
Gurrowa Place is a 1.7 billion dollar mixed-use urban renewal project delivered by Lendlease in partnership with the City of Melbourne and Scape. Located in the Queen Victoria Market Southern Precinct, the development features three distinct towers: a 28-level next-generation office building, a build-to-rent tower with approximately 560 units (including affordable housing), and a dedicated student accommodation tower with 1,100 beds. The project integrates the 1.8-hectare Market Square public park, the restoration of the heritage Franklin Street Stores into a retail and dining hub, and a new underground car park for market visitors.
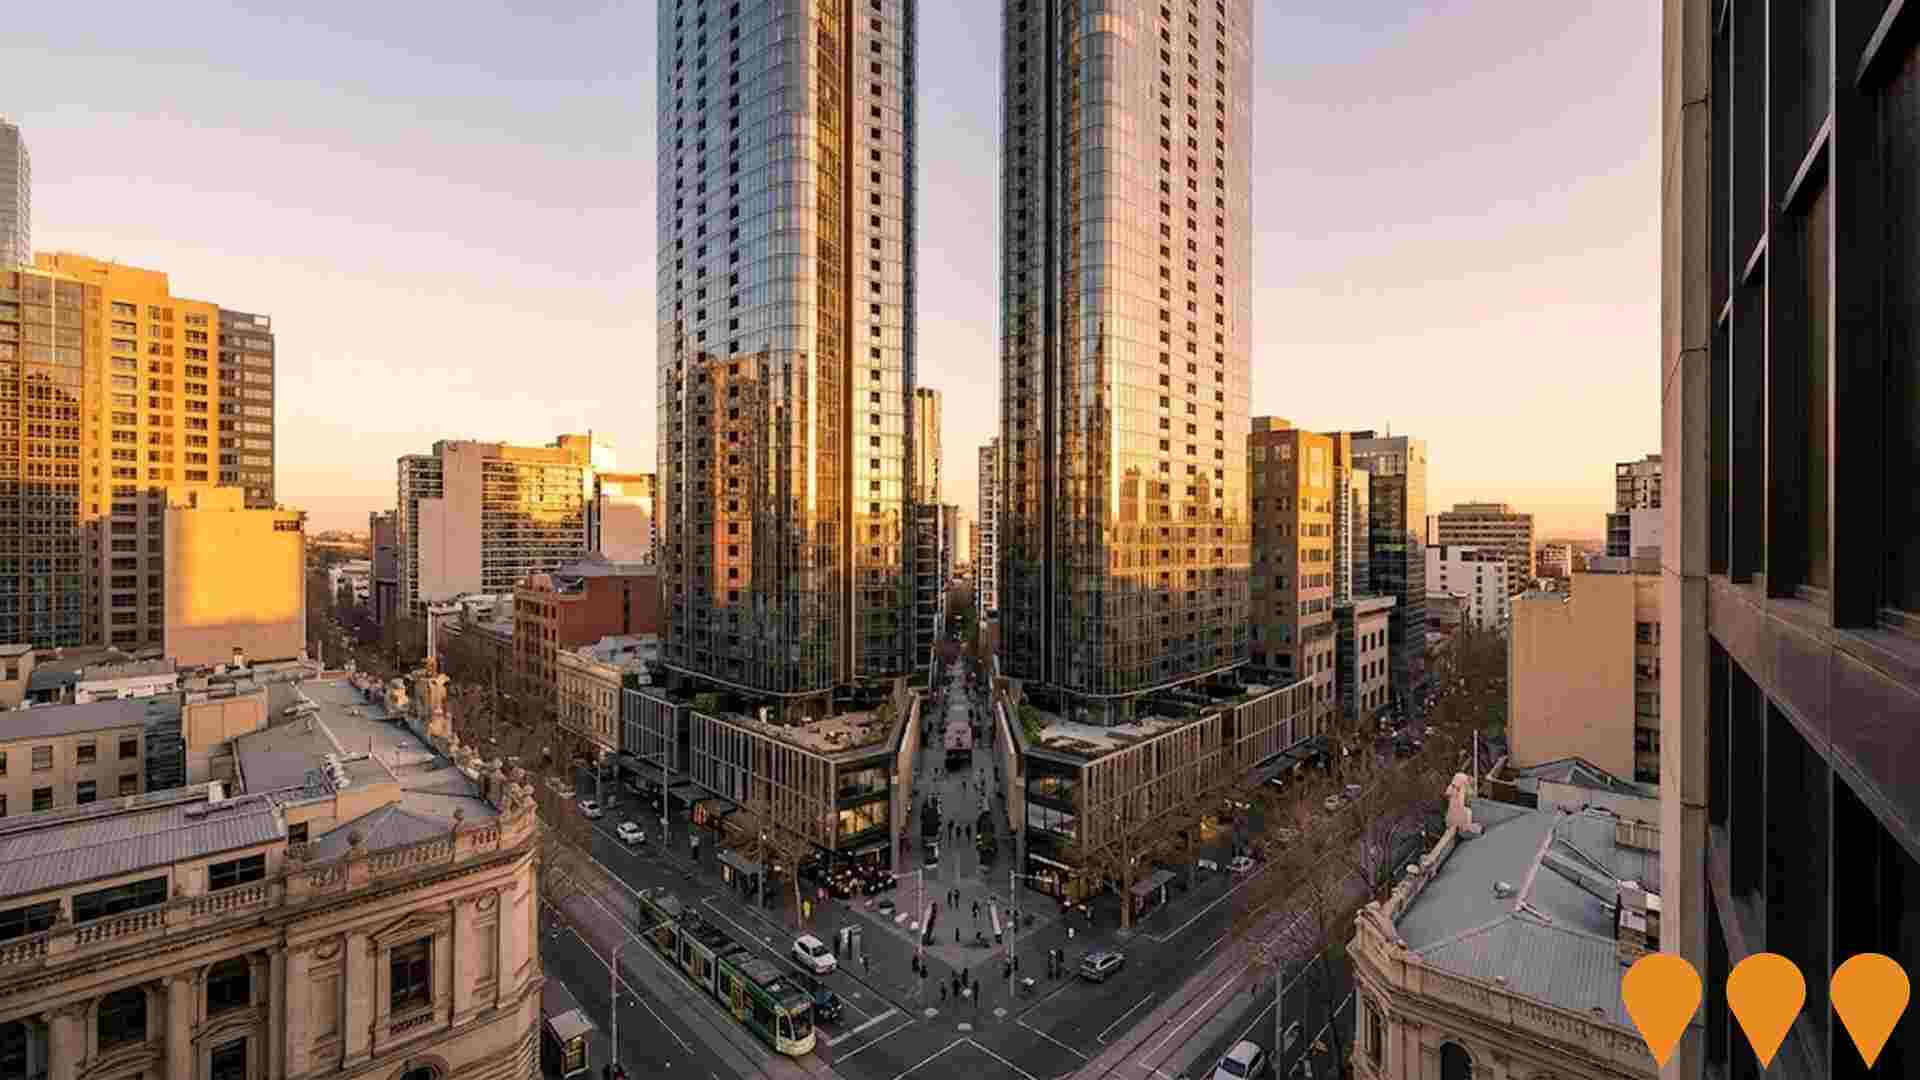
Queens Place
Queens Place is a flagship $1 billion mixed-use development featuring twin 80-storey residential skyscrapers with 1,700 luxury apartments, a retail precinct, and commercial spaces. Tower 1 is complete, while Tower 2 is in planning and development.
Greenline Project
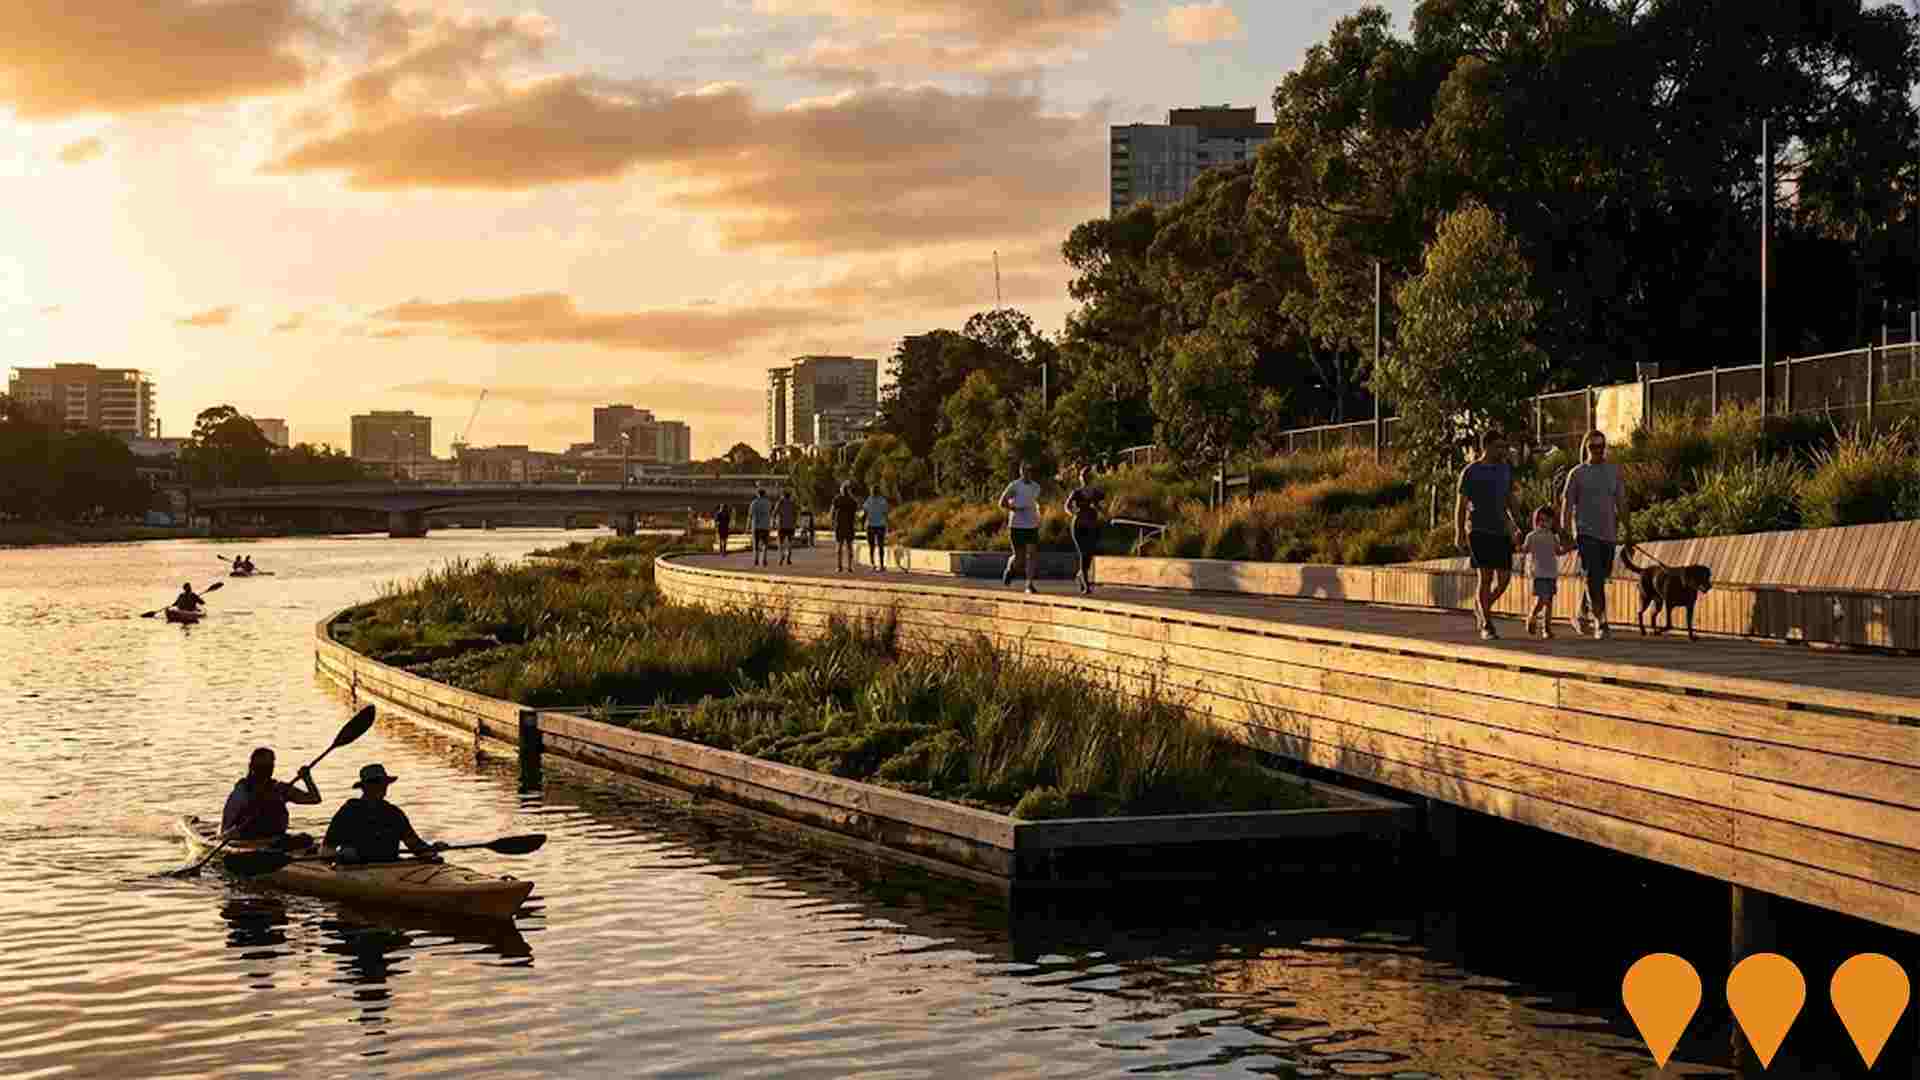
The Greenline Project is a transformational 4km urban renewal initiative creating a continuous promenade along the north bank of the Yarra River (Birrarung). Connecting five precincts from Birrarung Marr to Saltwater Wharf, the first major stage at Birrarung Marr is complete while planning and detailed design advance for the central riverfront sections. Delivered by the City of Melbourne in partnership with design studios ASPECT Studios and TCL, the project integrates native habitat restoration and Indigenous cultural design.
Elysium Fields
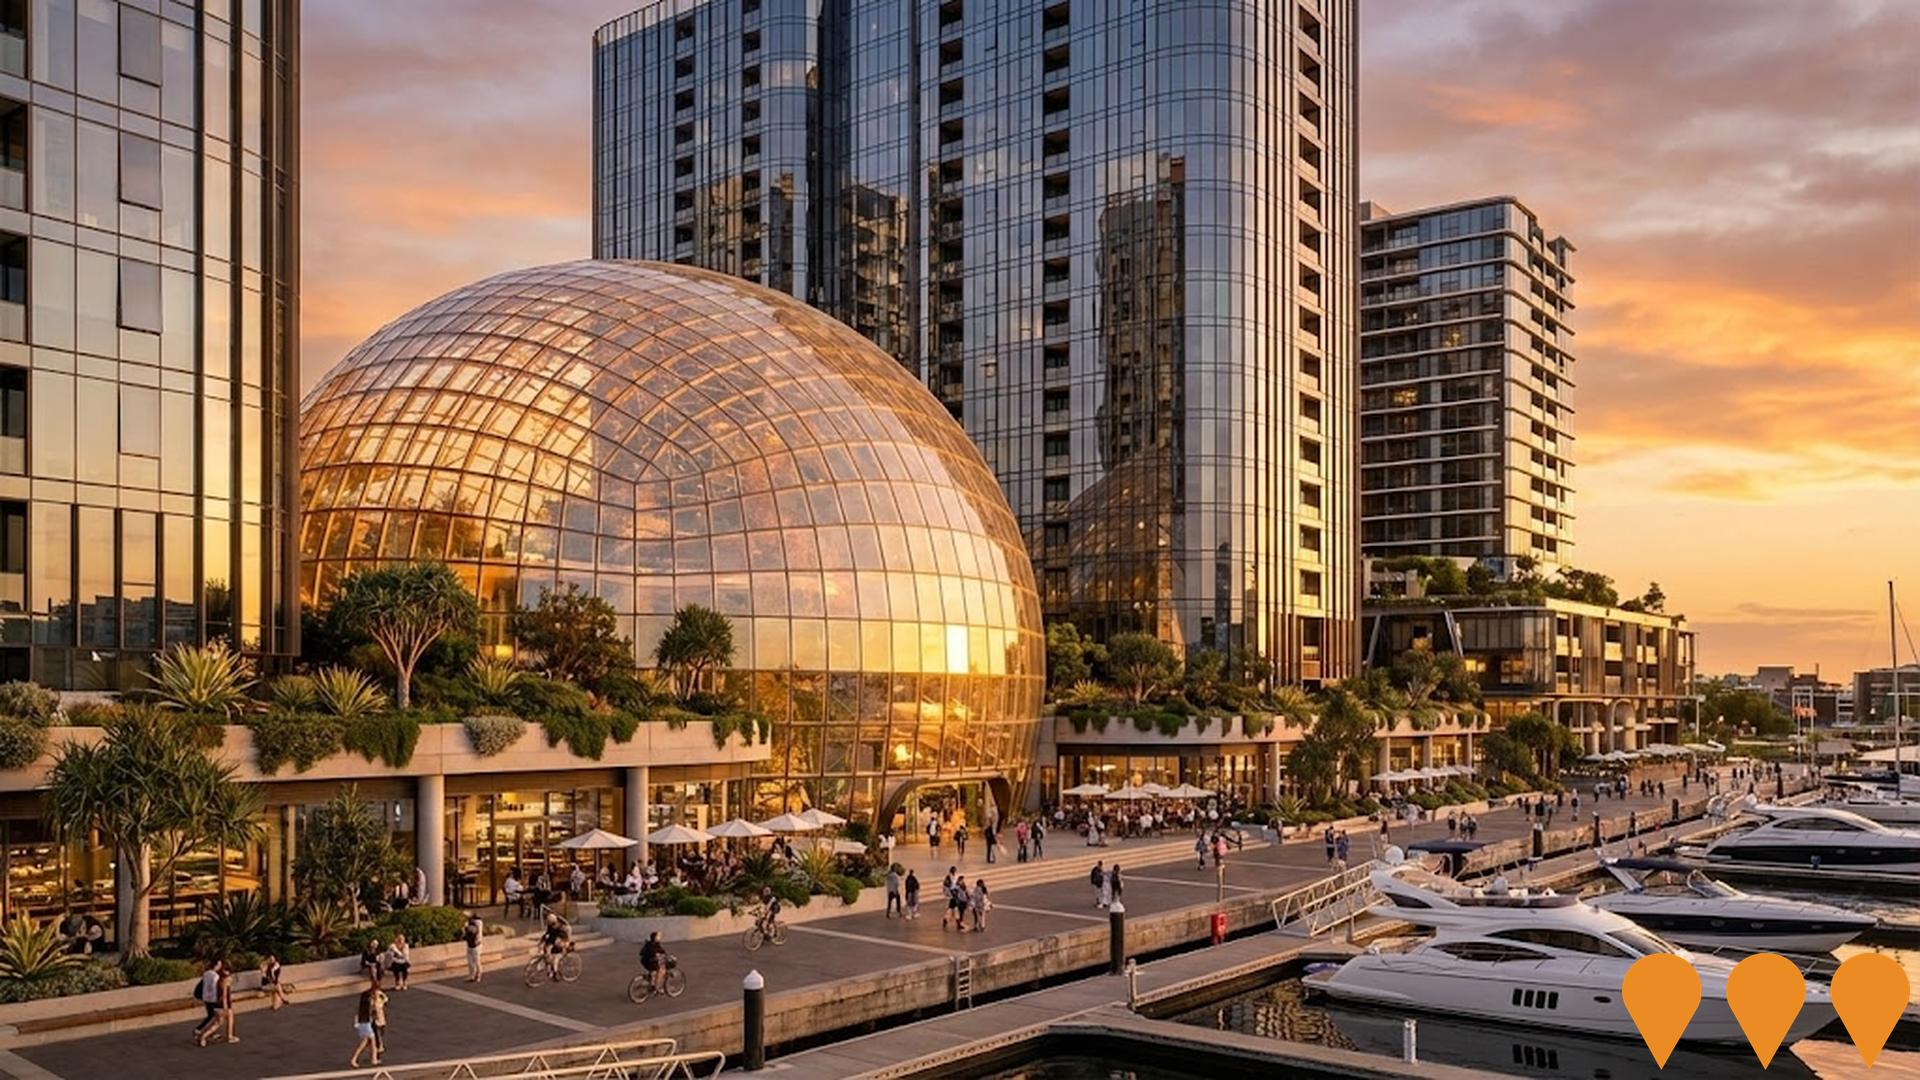
Elysium Fields is a $1.75 billion wellness-focused mixed-use precinct being developed by GURNER Group and City Harbour across a 2.7-hectare site at 208-226 Harbour Esplanade in Melbourne's Docklands. The masterplan comprises approximately 1,100 build-to-sell and build-to-rent apartments across multiple towers up to 30 storeys, paired with extensive health clubs, retail, dining, and a Veriu hotel. Construction is actively underway with builders Hamilton Marino and Maxcon delivering initial residential towers.
Melbourne Arts Precinct Transformation
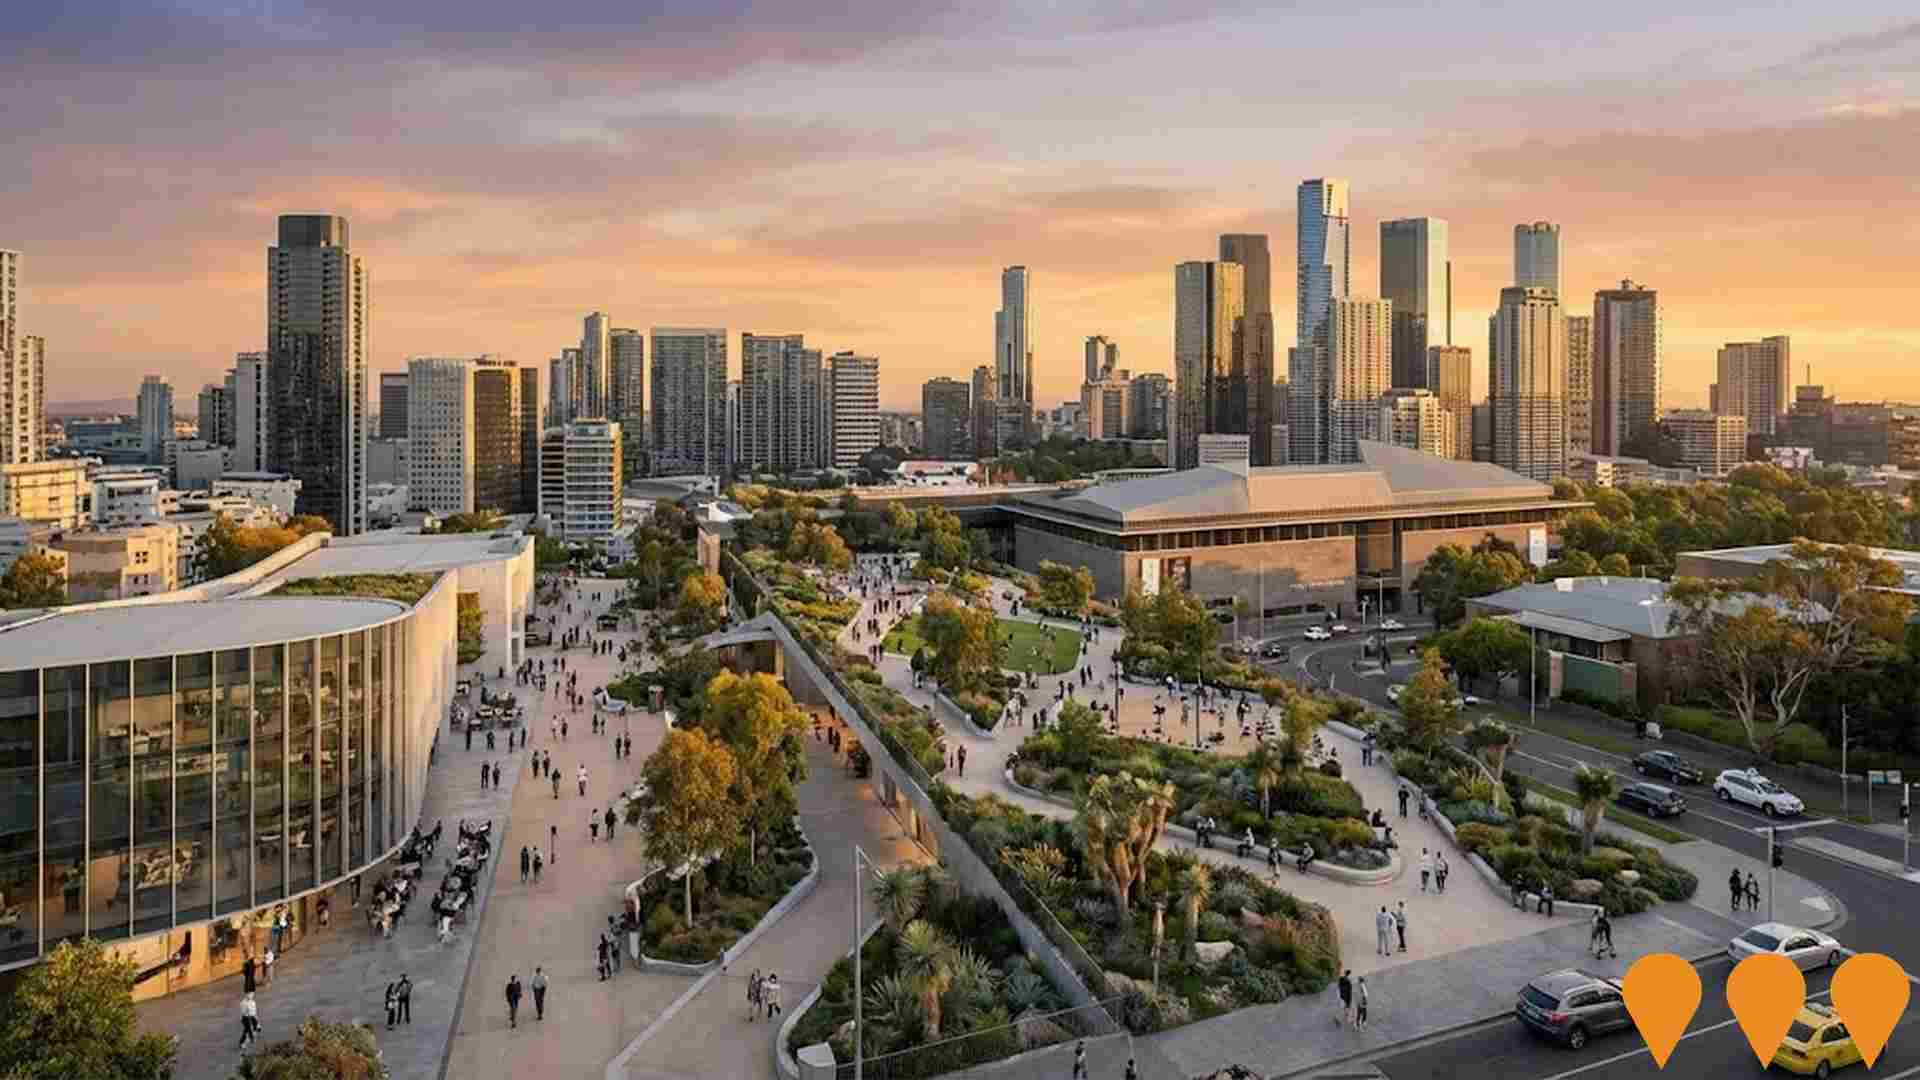
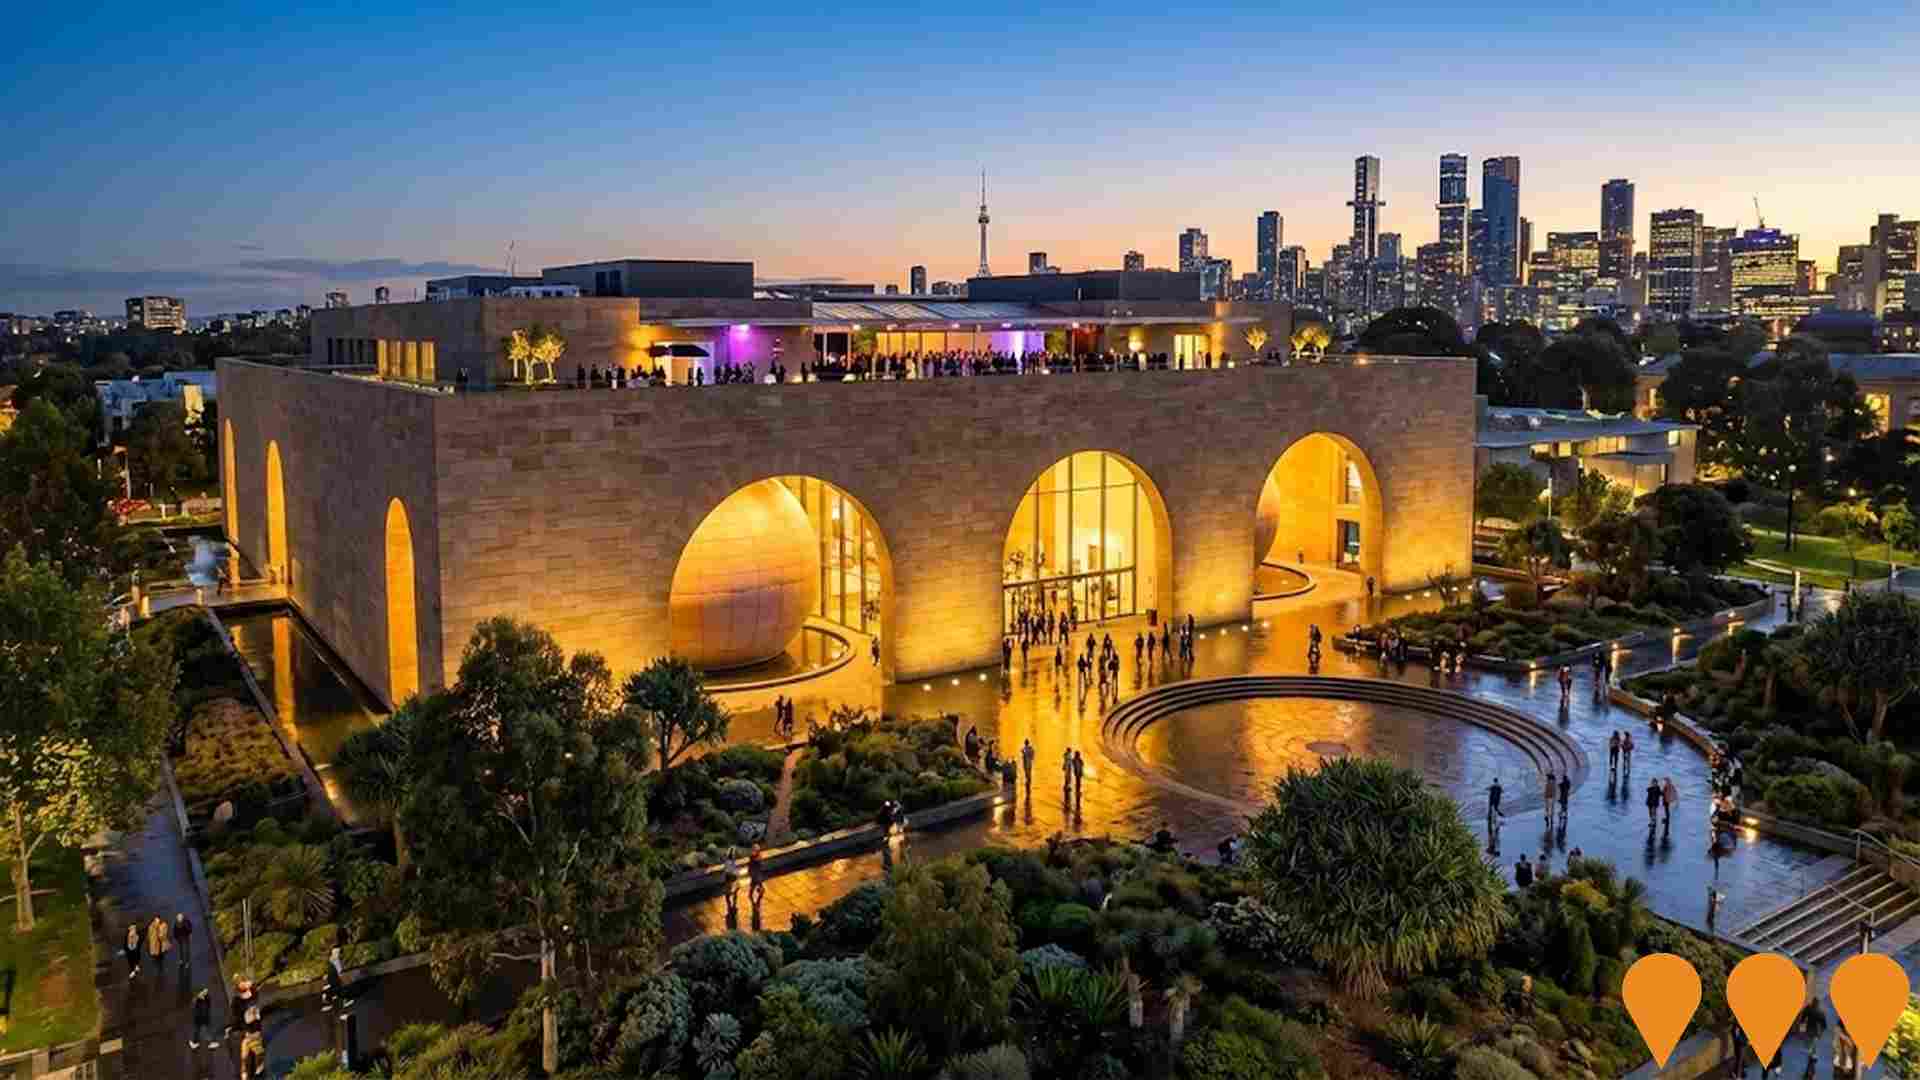
The $1.7 billion Melbourne Arts Precinct Transformation (MAPT) is a landmark cultural redevelopment overseen by MAP Co and delivered by Development Victoria. The project encompasses major upgrades to Arts Centre Melbourne's Theatres Building, the construction of The Fox: NGV Contemporary art gallery, and the creation of Laak Boorndap, an 18,000 sqm elevated urban garden. Construction is actively advancing across deep basement civil packages, with overall completion scheduled for 2028.
Ian Potter State Theatre Refurbishment
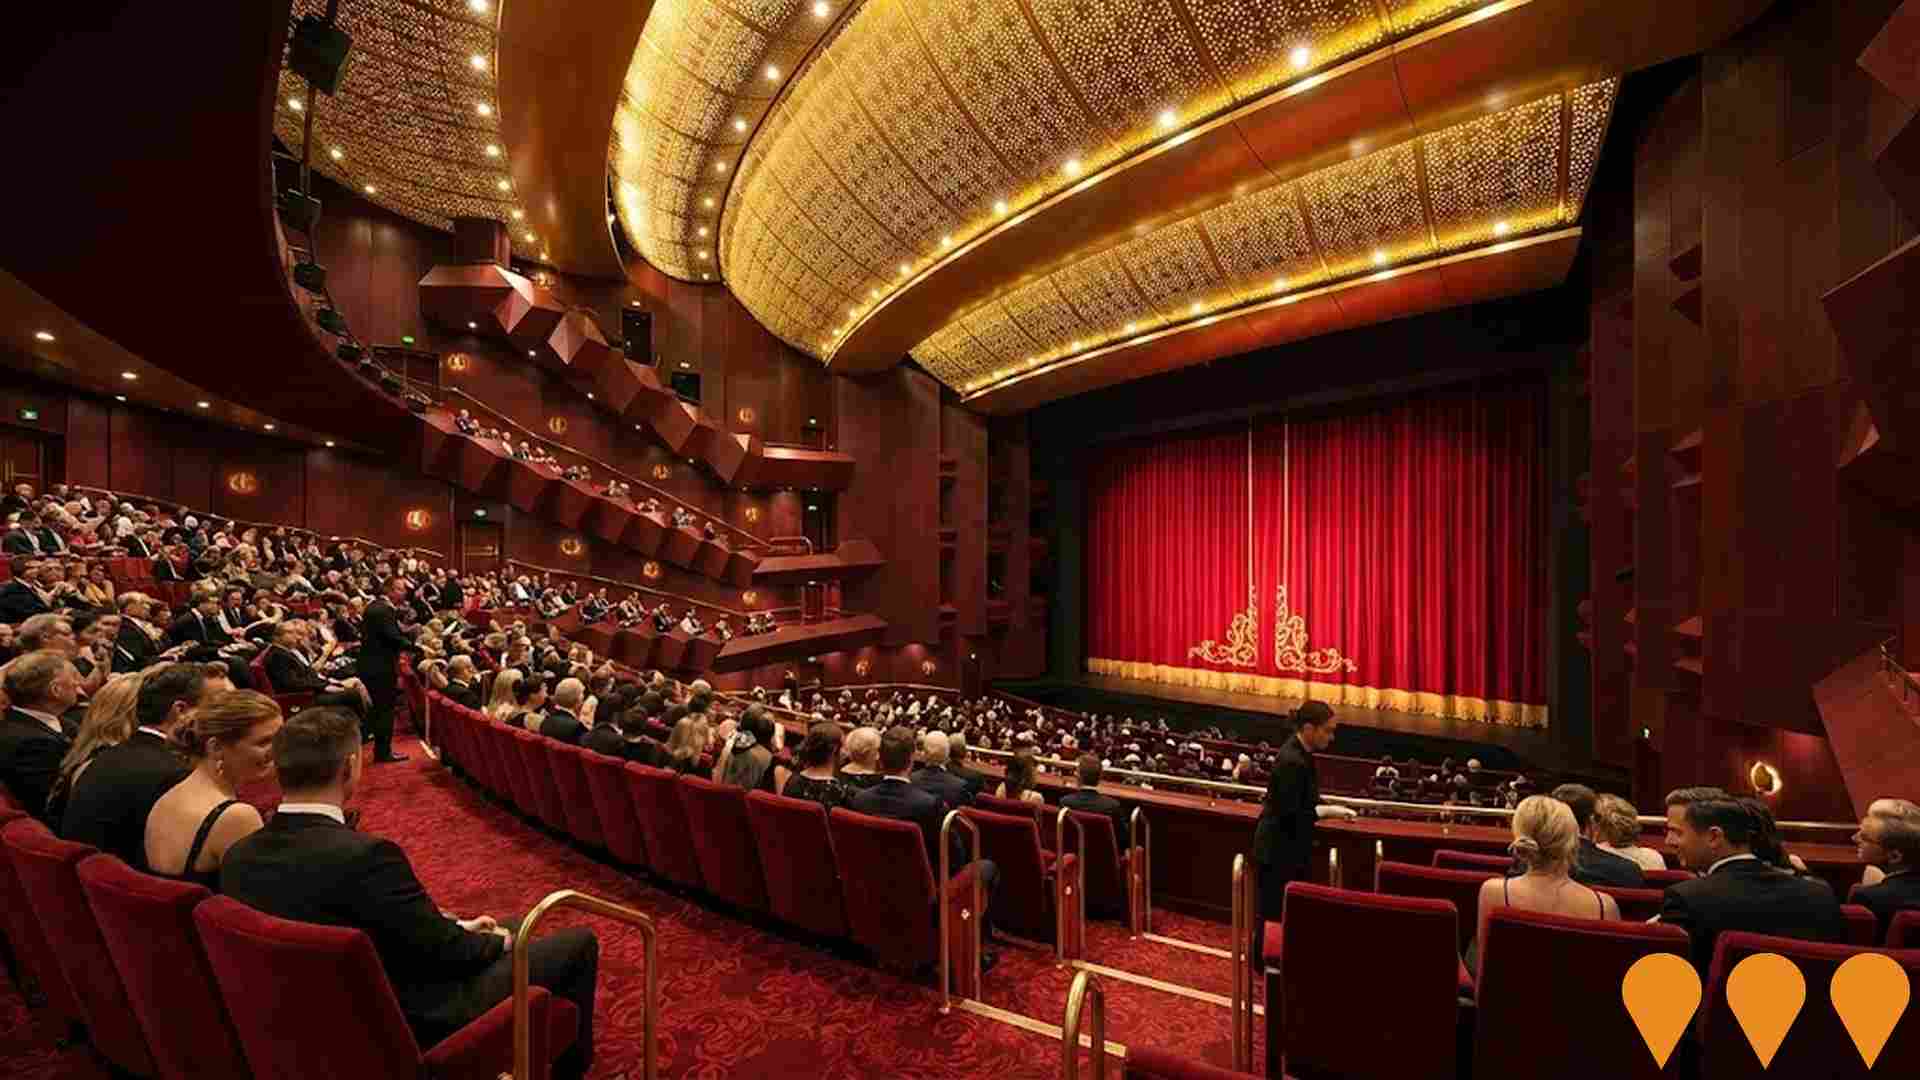
A major refurbishment of the heritage-listed State Theatre at Arts Centre Melbourne, renamed the Ian Potter State Theatre following a philanthropic donation from the Ian Potter Foundation. The first significant upgrade since the venue opened in 1984, the works expand the Theatres Building footprint by 16 percent and include new lifts and accessible seating across all three levels, full replacement of seating, refreshed interiors honouring John Truscott's original design, improved acoustics, new state-of-the-art lighting, sound and broadcast technology, and upgraded heating, cooling and fire protection systems.The project also delivers a doubled-size loading dock, a new flexible rehearsal space the same size as the State Theatre stage with an adjoining function room, a new accessible stage door, two new hospitality outlets opening onto the Laak Boorndap urban garden, and four new wheelchair accessible amenities plus two all-gender amenities in the foyers. Construction commenced in March 2024 with Lendlease as principal contractor and NH Architects leading the design. The theatre is now scheduled to reopen in October 2026, six months ahead of the original schedule, as the first completed milestone of the wider 1.7 billion dollar Melbourne Arts Precinct Transformation. My Fair Lady will be the first major musical to perform in the refurbished venue from November 2026, with The Australian Ballet and Opera Australia returning as resident companies.
The Fox: NGV Contemporary
Set to be Australia's largest gallery dedicated to contemporary art and design, The Fox: NGV Contemporary will span 30,000 square metres including more than 13,000 square metres of public exhibition space. Designed by Angelo Candalepas and Associates with a team of 20 leading architecture and engineering firms, the building will feature dramatic arched entries, a colossal 40-metre-high spherical orientating hall (the omphalos) and a dual-level rooftop terrace and sculpture garden with views over Melbourne. The gallery is the centrepiece of the Victorian Government's 1.7 billion dollar Melbourne Arts Precinct Transformation, which also delivers the 18,000 square metre Laak Boorndap urban garden and major upgrades to Arts Centre Melbourne's Theatres Building.The former Carlton United Breweries building on the site was deconstructed in 2024, with 95 per cent of materials diverted from landfill. Lendlease was appointed head contractor in March 2025 and is delivering the gallery alongside part of the Laak Boorndap deck structure and precinct services. Piling works are progressing on the site, with construction expected to support around 11,000 jobs across the wider precinct project. The gallery is targeted for completion in 2028.
17,019 residents of Melbourne CBD - North are employed, from a labour force of 17,464. Unemployment sits at 2.5%, with participation at 73.3%. Weighted for its industry mix, the area's sectors are forecast to grow about 6.8% nationally over five years. That reflects industry composition only and makes no allowance for local population growth, so in an area growing as fast as this one it understates the likely rise in local jobs. The working-day population is estimated at 35,118, about 144% of the resident population, so the area draws in more workers than it sends out. Unemployment and labour force come from ABS Small Area Labour Markets, updated quarterly; the industry and occupation profile is from the 2021 Census.
Detail
The local labour market in Melbourne CBD - North features an educated workforce with notable concentration in professional services, a low unemployment rate of 2.5%, and an estimated 3.9% expansion in jobs over the past year. By March 2026, employed residents numbered 17,019, while the local jobless rate sat 2.2% below Greater Melbourne's 4.8%. The local participation rate of 73.3% remains broadly aligned with the metropolitan figure of 70.1%. At the Census, 32.8% of workers stated they were working from home, a metric potentially shaped by Covid-19 lockdown restrictions. Resident employment is concentrated primarily across accommodation & food, professional & technical, and retail trade.
Specialisation is exceptionally pronounced in accommodation & food, where the local concentration is 3.8 times the regional level. Conversely, the construction sector represents a smaller footprint, engaging 2.9% of workers relative to 9.7% regionally. Recording 1.6 workers for every resident at the Census, the precinct serves as a major commercial center, providing more employment opportunities than it has local residents and drawing commuters from across the metropolitan area. AreaSearch combined SALM and ABS figures to show that employment grew by 3.9% and the labour force expanded by 3.7% during the year to March 2026, which led to a 0.1 percentage point decline in the unemployment rate. In contrast, Greater Melbourne experienced a 2.1% rise in employment, a 2.3% increase in the labour force, and a 0.2 percentage point increase in unemployment. Jobs and Skills Australia's national employment forecasts from Mar-26 provide additional context on potential future demand in Melbourne CBD - North. These five and ten-year projections have been overlaid with the local employment profile to estimate growth trends. National employment is projected to grow by 6.6% over five years and 13.7% over ten years, though sectoral growth rates vary widely. When applied to Melbourne CBD - North's employment mix, these industry-specific forecasts indicate local employment should rise by 6.8% over five years and 13.6% over ten years, noting that this is a simple weighting extrapolation for illustrative purposes and does not incorporate localised population projections.
Frequently Asked Questions - Employment
Median household income in Melbourne CBD - North is $1,089 a week (about $57,000 a year), with median personal income at $638 a week. ATO records put median taxable income at $29,650 a year against an average of $46,562. The average runs 57% above the median, a wider spread than most areas and a sign of a concentrated group of high earners. Household income is from the 2021 Census; taxable income is from ATO Taxation Statistics for the latest financial year available, indexed forward using the ABS Wage Price Index.
Detail
Based on AreaSearch calculations of ATO postcode data published for financial year 2023, taxpayers in the Melbourne CBD - North SA2 registered a median income of $29,650 and an average income of $46,562, lagging both the national figure and the Greater Melbourne benchmarks of $57,688 and $75,164. Adjusting for a 9.62% increase in the Wage Price Index since financial year 2023 yields updated estimates of roughly $32,502 (median) and $51,041 (average) as of March 2026. In the 2021 Census, personal, family, and household earnings all tracked between the 6th and 17th percentiles nationally.
The largest individual earnings bracket encompasses the 26.5% of workers making $800 - 1,499 weekly (6,441 residents), differing from the wider metropolitan area where the $1,500 - 2,999 band leads at 32.8%. Living costs present significant challenges, with disposable income after housing standing at 70.0% of income remaining, placing the area at the 3rd percentile, while its SEIFA income metric sits in the 7th decile.
Frequently Asked Questions - Income
Melbourne CBD - North had 8,767 occupied dwellings at the 2021 Census, 0% detached houses and 100% apartments. 9% are owned with a mortgage, 80% rented and 10% owned outright. At that Census the median rent was $361 a week and the median mortgage repayment $1,725 a month. Rent absorbs 33.1% of household income here and mortgage repayments 36.6%. Dwelling stock, tenure and housing costs are 2021 Census measures — the only source that counts dwellings at this boundary size.
Detail
The residential landscape in Melbourne CBD - North at the time of the latest Census featured no standalone houses, consisting of 100.0% other dwellings (semi-detached, apartments, 'other' dwellings), contrasting with the wider metropolitan mix of 67.9% houses and 32.1% other dwellings. Outright property ownership in Melbourne CBD - North trailed Melbourne metro at 10.4%, with remaining households holding a mortgage (9.3%) or living in rented properties (80.3%). The median monthly mortgage payment in the district stood at $1,725, below the Melbourne metro figure of $2,000, while median weekly rent was $361 compared to $390 across Melbourne metro.
Nationally, local mortgage obligations sit below the Australian average of $1,863, and weekly rents track below the countrywide benchmark of $375.
Frequently Asked Questions - Housing
Melbourne CBD - North counted 8,767 households at the 2021 Census, an estimated 12,631 today, averaging 1.7 people each. 3% are couples with children, fewer than in 98% of areas nationally, against 22% couples without children. 48% of households are people living alone, and families average 0.2 children. Household and family composition is measured only by the Census, so these are 2021 figures.
Detail
Family units account for 32.0% of all households, consisting of couples without children (21.9%), couples with children (3.4%), and single parent families (2.6%). The remaining 68.0% comprises non-family arrangements, led by single-person households at 47.7% and group living arrangements at 20.2%. The area records an average household occupancy of 1.7 people, smaller than the Greater Melbourne figure of 2.6.
Frequently Asked Questions - Households
59.4% of adults in Melbourne CBD - North hold a university qualification, including 37.5% with a bachelor degree and 19.9% with postgraduate qualifications. A further 5.9% hold a vocational qualification. 1 school serves the area. Qualifications come from the 2021 Census; school enrolments, ICSEA and results come from ACARA's current release.
Detail
Tertiary qualification levels in Melbourne CBD - North notably outstrip state and national figures, with 59.4% of the population aged 15+ holding university degrees, compared to 33.4% in VIC and 30.4% in Australia. This high level of education positions the local workforce well for knowledge-intensive sectors. Bachelor degrees represent the largest share at 37.5%, followed by postgraduate qualifications (19.9%) and graduate diplomas (2.0%). Vocational credentials account for 16.3% of formal qualifications among residents aged 15+, comprising advanced diplomas (10.4%) and certificates (5.9%). Engagement in learning is exceptionally high throughout the precinct, with 53.5% of residents currently enrolled in formal education.
Tertiary study represents the dominant category at 36.2%, while secondary education accounts for 1.2% and primary education comprises 1.1%.
Frequently Asked Questions - Education
Schools Detail
Public transport in Melbourne CBD - North reaches 34 stops on 65 routes, timetabled for about 27,900 services a week. The typical home sits about 100 m from its nearest stop. Trams carry the largest share of public transport commuters. Stop and service counts are built from operators' published GTFS timetables and refresh with each timetable release; vehicle ownership is from the 2021 Census.
Detail
The local transit network in Melbourne CBD - North encompasses 34 active transport stops operating across a blend of buses and lightrail. These facilities are served by 65 individual routes that generate 27,869 weekly passenger trips. Access to public transit is exceptional, with residents situated an average of 96 meters from their closest boarding point. Commuter travel primarily flows outward from this residential area, with walking accounting for 28% of trips and train transit representing 25%. Private vehicle ownership averages no motor vehicles per dwelling, below the broader regional standard.
At the 2021 Census, working from home was reported by 32.8% of workers, a figure that may reflect pandemic conditions. Across all transit lines, trip frequencies average 3,981 trips per day, translating to roughly 819 weekly trips per individual stop.
Frequently Asked Questions - Transport
Transport Stops Detail
88.1% of residents in Melbourne CBD - North report no long-term health condition, a healthier profile than 92% of areas nationally. 0.9% need daily assistance with core activities, and 46.3% hold private health cover. The standardised death rate runs at 4.9 per 1,000 residents. Health conditions, assistance needs and insurance are 2021 Census measures; the death rate comes from current ABS releases.
Detail
General health metrics for Melbourne CBD - North are exceptionally positive according to AreaSearch research into mortality and chronic illness rates, showing very low prevalence of common health conditions across all age groups. Private medical insurance coverage is low, held by roughly 46% of the total population (~11,253 people), compared to 56.7% across Greater Melbourne and 55.7% nationwide. Mental health conditions and asthma represent the most frequently reported ailments, affecting 5.8 and 4.3% of residents, respectively. A substantial 88.1% of the community reported having no chronic medical conditions, outpacing the 72.6% benchmark for Greater Melbourne.
Older residents aged 65 and over make up 2.4% of the local population (576 people), notably below the metropolitan proportion of 15.1%. Wellness metrics among this senior group remain strong, with national health rankings tracking in line with the wider resident population.
Frequently Asked Questions - Health
82.4% of Melbourne CBD - North residents were born overseas and 75.1% speak a language other than English at home, more culturally diverse than 99% of areas nationally. The largest reported ancestries are Chinese (43.5%) and English (8.5%). Ancestry, language and country of birth are counted only by the Census, so these are 2021 figures.
Detail
Melbourne CBD - North ranks among the most multicultural communities in the nation, with 82.4% of residents born overseas and 75.1% speaking a non-English language at home. Christianity represents the most widely held religious faith at 20.7% of the population. However, Buddhism displays the most pronounced relative representation, accounting for 13.8% of residents compared to the Greater Melbourne benchmark of 4.2%. Assessing parental country of birth, Chinese heritage forms the largest ancestry group at 43.5%, significantly exceeding the 6.5% metropolitan average. The Other category accounts for 18.4%, while English ancestry sits at 8.5%, substantially lower than the 20.1% recorded regionally.
Notable differences also appear across other backgrounds: Korean background represents 2.8% locally (vs 0.3% regionally), Vietnamese accounts for 3.1% (vs 1.9%), and Indian background comprises 4.9% (vs 4.2%).
Frequently Asked Questions - Diversity
The median resident of Melbourne CBD - North is 25, younger than 100% of areas nationally. That is 1 year younger than at the 2021 Census. 80.3% of residents are aged 15 to 34. Age cohorts are not raw Census counts: the Census split is re-based to the latest ABS population estimates and state projections.
Detail
The demographic profile of Melbourne CBD - North is largely weighted towards early adulthood prior to family formation. AreaSearch figures for August 2026 indicate that 54.7% of the local population falls into the young to middle aged adults (25 - 44) cohort, compared to 32.1% across Greater Melbourne, while middle aged and young retiree cohorts (45 - 64) represent only 4.7% locally versus 22.3% regionally. The estimated median age as at August 2026 is 25, down from 26 at the 2021 Census, sitting 12 years below the Greater Melbourne median of 37 and well under the national median of 38 recorded at the same Census.
Since the Census, the young to middle aged adults bracket expanded from 50.6% to an estimated 54.7%. This age segment is projected to deliver the largest absolute expansion by 2041, increasing by 6,258 (47%) to 19,551 people. In percentage terms, retiree and elderly cohorts (65+) are forecast to see the quickest acceleration, rising 148% to 1,430 residents.
Frequently Asked Questions - Age
Data & MethodBoundaries, Sources & Method for Melbourne CBD - North
9 of 14 data sections on this page were updated within the last 12 months — the newest current to Aug 2026.
Everything is aggregated to the SA2 boundary shown above, on a 2021 Census baseline. Only 3 sections — housing, households and cultural diversity — still wait on the 2026 Census.
The ledger — source, cycle and currency by section
| Section | Source & update cycle | Currency |
|---|---|---|
| Updated within the last 12 months 9 sections | ||
| Population | ABS, GNAF, Geoscience Australia Annual (ABS ERP) | Aug 2026 last month headline measures · 2021 Census baseline |
| Re-based to the ABS Estimated Resident Population (June 2025 release) and updated with new dwellings from GNAF address data. Current to Aug 2026, with the 2021 Census supplying the small-area baseline. | ||
| Age profile | ABS, Geoscience Australia, State governments Annual | Aug 2026 last month headline measures · 2021 Census baseline |
| Age cohorts are re-based to the latest ABS population estimates and state projections, current to Aug 2026. Each cohort is held as a Census baseline and a current estimate. | ||
| Development & approvals | ABS, GNAF Monthly (ABS approvals) | Aug 2026 last month headline measures · Jun 2026 baseline |
| Property sales & rents | Valuer General, Rental Board, ABS Weekly sales, quarterly rents | Aug 2026 last month all 21 measures |
| Sales from the state Valuer General register, refreshed weekly, and rents from quarterly rental bond lodgements. Both are read live each time this page loads, current to Aug 2026. | ||
| Infrastructure projects | Infrastructure Australia, State agencies, Local governments Daily | Jun 2026 3 months ago all 5 projects tracked here |
| Project pipeline maintained continuously from Infrastructure Australia, state agencies, local government and public announcements. Records are added and revised daily; this area was last updated Jun 2026. | ||
| Employment | ABS, DEWR, JSA Quarterly (ABS SALM) | Mar 2026 6 months ago headline measures · 2021 Census baseline |
| Unemployment and labour force from ABS Small Area Labour Markets, current to Mar 2026. The growth outlook applies Department of Employment (now Jobs and Skills Australia) forecasts for all 19 industry divisions to the local industry mix, so it measures sector composition rather than local expansion and makes no allowance for population growth. Job demand comes from the same agency via its Internet Vacancy Index; industry and occupation structure from the 2021 Census. | ||
| Education | ABS, ACARA Annual (ACARA) | Aug 2026 last month headline measures · 2021 Census baseline |
| Transport | ABS, State Transport Departments Each timetable release | Jul 2026 2 months ago headline measures · 2021 Census baseline |
| Services & amenities | Provider directories, ACECQA Continuous | Jul 2026 2 months ago all 14 measures |
| Annual and financial-year sources 2 sections | ||
| Income | ABS, ATO Annual (ATO) | FY 2023 3 years ago headline measures · 2021 Census baseline |
| ATO taxable income statistics for FY 2023, indexed forward using the Wage Price Index. Census household income provides the distribution detail. | ||
| Health | ABS, ATO Annual | 2024 2 years ago headline measures · 2021 Census baseline |
| Census-measured — next update: 2026 Census 3 sections No more current small-area source exists for these, so they are labelled as Census-measured rather than implied to be current. | ||
| Housing | ABS 5-yearly (Census) | 2021 Census next update 2026 all 30 measures |
| Households | ABS 5-yearly (Census) | 2021 Census next update 2026 all 18 measures |
| Cultural diversity | ABS, Geoscience Australia 5-yearly (Census) | 2021 Census next update 2026 all 44 measures |
"Currency" is the most recent release feeding that section. Where the Census supplies the structural baseline underneath a current headline figure, the row says so.
How the numbers are built
Population
The Census provides the small-area baseline, aggregated from mesh blocks to this boundary. It is then re-based to the ABS Estimated Resident Population (June 2025 release), and new dwellings built since Census night are counted from address data — 86 validated new addresses here. The headline figure is therefore a current estimate for Aug 2026, not a 2021 count (16,870 at the 2021 Census → 24,306 now). Annual growth rates are compound (CAGR), not simple averages.
Age profile
Cohort shares are not raw Census counts. Every cohort is held as a pair — the Census baseline and a current estimate — and the split is re-based using ERP and state population projections, current to Aug 2026. Median age is the Census median plus modelled change since. Charts that show both are labelled "2021 Census vs Current Estimate".
Property sales
Sourced from the state valuation authority's sales register — current, not Census, and refreshed weekly. Medians are calculated from settled transactions in the period shown; periods with very low transaction counts are flagged or suppressed, because a handful of sales can move a median substantially.
Rents
Derived from state rental bond lodgement data, by dwelling type and bedroom count. Bonds are lodged at the start of a new tenancy, so this reflects new lettings, not the whole rented stock.
Development & infrastructure
Building approvals come from current ABS releases; development applications are collected from council and state planning portals; the infrastructure pipeline is compiled from Infrastructure Australia and local government sources. Applications are matched to this boundary by address or coordinates, so very recent lodgements may not yet appear.
Employment & income
Industry and occupation structure comes from the Census, but the headline labour-market indicators do not. Unemployment and labour force are derived from ABS Small Area Labour Markets (quarterly). The employment outlook applies Department of Employment forecasts for all 19 industry divisions to this area's own industry mix (the agency is now Jobs and Skills Australia), as does the Internet Vacancy Index used for job demand. Because it is weighted on industry composition alone, that outlook carries no allowance for local population growth — in fast-growing areas the real rise in local jobs will typically be higher. Income combines Census household income with ATO taxable-income statistics for FY 2023, indexed forward using the Wage Price Index.
Education, transport & amenities
School enrolments, ICSEA and performance come from ACARA's current release, not the Census. Public transport stops and service frequency are derived from GTFS timetable feeds published by state transport departments. Services and amenities are proximity and count scores built from provider directories, refreshed on their own cycle. The Census contributes only the travel-to-work and qualification measures.
Rankings and benchmarks. Where we rank this area, the comparison set is every area of the same boundary type — suburbs against suburbs, SA2s against SA2s. Benchmarks compare this area against its greater capital city region and the national figure for the same measure and period.
Limits worth knowing. Small areas carry larger error margins, and the ABS introduces small random adjustments to Census counts to protect confidentiality — so totals may not sum exactly. Estimates re-based from regional data describe the area's expected trajectory, not a direct count of it. Figures are indicative for research and are not financial, planning or valuation advice.
Cross-check us. The Census baseline for this boundary is at ABS 2021 Census QuickStats (206041504). QuickStats reports 2021 only — the figures on this page are more current wherever the ledger shows a later date.