Chart Color Schemes
This analysis uses ABS Statistical Areas Level 2 (SA2) boundaries, which can materially differ from Suburbs and Localities (SAL) even when sharing similar names.
SA2 boundaries are defined by the Australian Bureau of Statistics and are designed to represent communities for statistical reporting (e.g., census and ERP).
Suburbs and Localities (SAL) represent commonly-used suburb/locality names (postal-style areas) and may use different geographic boundaries. For comprehensive analysis, consider reviewing both boundary types if available.
est. as @ -- *
ABS ERP | -- people | --
2021 Census | -- people


Curious about local property values? Filter the chart to assess the volume and appreciation (including resales) trends and regional comparisons, or scroll to the map below view this information at an individual property level.


Find a Recent Sale

Sales Detail
East Melbourne has an estimated 5,246 residents, up from 4,896 at the 2021 Census — a change of 350 people, or 7.1%. Overseas migration accounts for 100.0% of that increase. That puts 1,809 residents on each square kilometre. Population is estimated from ABS Estimated Resident Population releases and GNAF address data, re-based from the 2021 Census and updated annually.
Detail
As of Aug 2026, the estimated population of East Melbourne stands at approximately 5,246 according to AreaSearch analysis. This represents an addition of 350 people (7.1%) relative to the 2021 Census, when 4,896 people were recorded. These figures are derived from the ABS estimated resident population of 5,245 as of June 2025 alongside post-Census address validation. The current population density corresponds to 1,809 persons per square kilometer, exceeding the typical benchmark across locations evaluated nationally by AreaSearch. With an expansion of 7.1% since census, the locality trails state growth (9.5%) by only 2.4 percentage points, highlighting solid underlying demographic momentum.
Recent gains were almost exclusively propelled by overseas migration, which served as the primary catalyst for growth. Projections utilised by AreaSearch incorporate ABS/Geoscience Australia data released in 2024 with a 2022 baseline for each SA2. Where SA2 coverage is absent, VIC State Government Regional/LGA projections released in 2023 are applied via a weighted aggregation approach from LGA to SA2 geographies. Age cohort growth rates derived from these models are similarly integrated across all locations for the period covering 2032 to 2041. Looking ahead, AreaSearch models indicate demographic growth tracking above median benchmarks across evaluated statistical areas, with East Melbourne projected to add 771 persons to 2041 based on the most recent annual ERP figures, translating to an aggregate increase of 14.7% over the 16 years.
Frequently Asked Questions - Population
65 new dwellings have been approved in East Melbourne over the past five years, an average of 13 a year. That is 2.7 approvals per 1,000 residents. Figures come from ABS building approvals aggregated to this SA2 boundary and are updated monthly as the ABS releases them.
Detail
Dwelling approvals in East Melbourne have held at an average of roughly 13 new residences annually, totaling 65 homes across the past 5 financial years (between FY-22 and FY-26). In the context of recent population contraction, this level of development activity represents sound relative volume for purchasers, with newly approved dwellings carrying an average expected construction value of $1,786,000 as developers prioritize high-end, premium developments. Furthermore, substantial local commercial development is evident, with $541.8 million in commercial approvals recorded this financial year. Per capita residential construction in East Melbourne is notably subdued when compared to Greater Melbourne, sitting 83.0% below regional average per person.
Such tight construction volumes generally underpin capital values and sustained buyer demand for established dwellings. Activity is also under the national average, indicating established urban maturity and probable planning restrictions. All recent residential approvals have comprised townhouses or apartments, delivering higher-density housing formats that cater well to downsizers, investors, and entry-level purchasers seeking accessible price points. According to the latest AreaSearch quarterly estimate, future forecasts indicate East Melbourne will add 770 residents by 2041. Should current rates of development persist, future residential additions could fall short of demographic expansion, likely intensifying market competition among buyers and bolstering local property values.
Frequently Asked Questions - Development
Development applications around East Melbourne
SOURCE: Planning portals and council registers, compiled by AreaSearch. Distance & bearing measured from the suburb midpoint.
AreaSearch tracks 10 current infrastructure and development projects inside East Melbourne, worth an estimated $896 million. A further 190 sit in the immediately surrounding suburbs, taking the tracked pipeline within reach of the area to $71.5 billion. 73 are already under construction and 92 are due for completion within three years. The pipeline spans residential development, business parks & technology hubs and communities, precincts & urban renewal. Records are compiled from Infrastructure Australia, state agencies, council planning portals and public announcements, reviewed and updated daily, then ranked by proximity, construction stage, completion horizon and project scale.
Detail
Local economic and property performance is heavily shaped by urban planning, transport initiatives, and major capital works. AreaSearch has tracked a total of 78 key projects with potential influence over the surrounding market, prominently featuring the Punt Road Oval Redevelopment, Simpson Street Residential Development, The Fox: NGV Contemporary, and 250 Albert Street.
Professional plan users can use the search below to filter and access additional projects.
INFRASTRUCTURE SEARCH
 Denotes AI-based impression for illustrative purposes only, not to be taken as definitive under any circumstances. Please follow links and conduct other investigations from the project's source for actual imagery. Developers and project owners wishing us to use original imagery please Contact Us and we will do so.
Frequently Asked Questions - Infrastructure
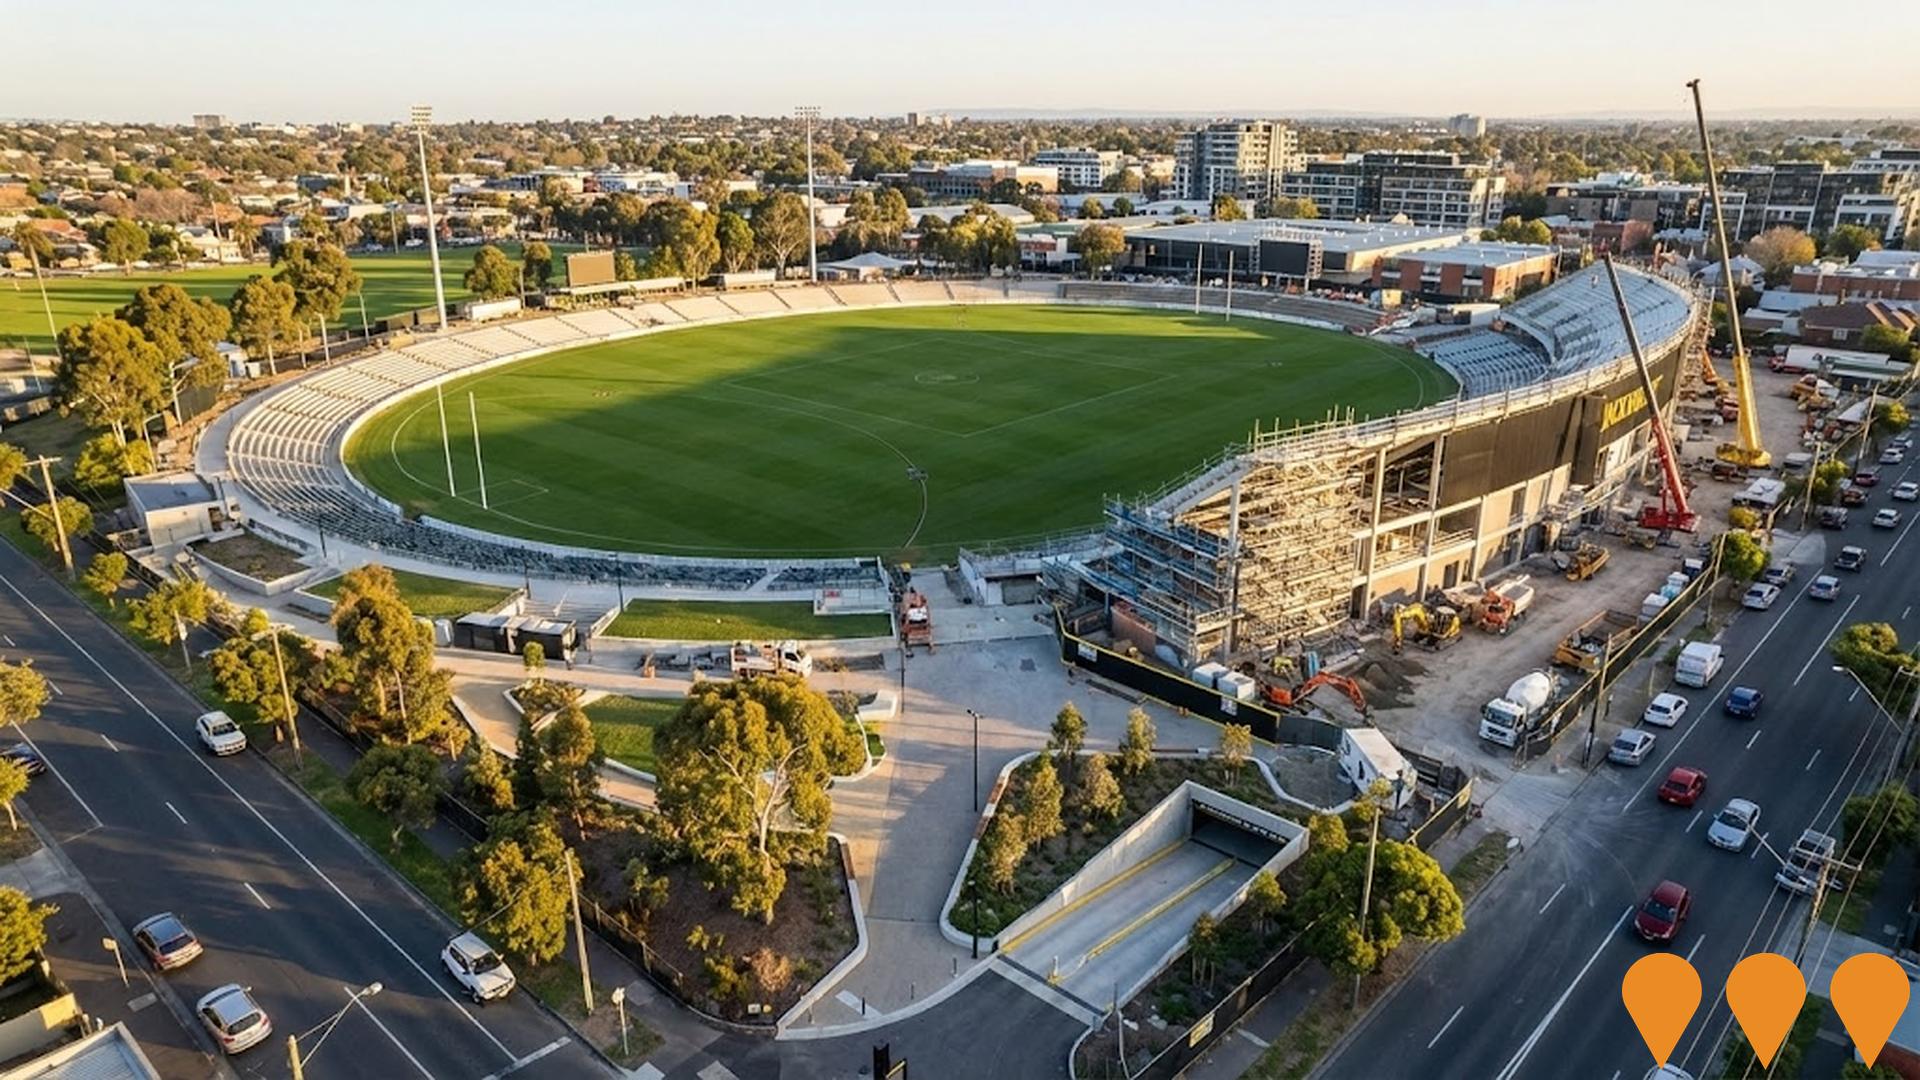
Punt Road Oval Redevelopment
A major transformation of the Richmond Football Club's home, featuring a new Jack Dyer Stand with a spectator capacity of 8,000. As of early 2026, construction is progressing with the car park structure nearing completion and the new stand footprint widening. The project includes elite training and administration facilities for AFL and AFLW teams, a realigned MCG-sized oval, and a three-level underground car park. It also houses the William Cooper Centre for community and indigenous programs, including the Korin Gamadji Institute and Melbourne Indigenous Transition School.The design incorporates salvaged bricks from the original historic stand to preserve the site's heritage.
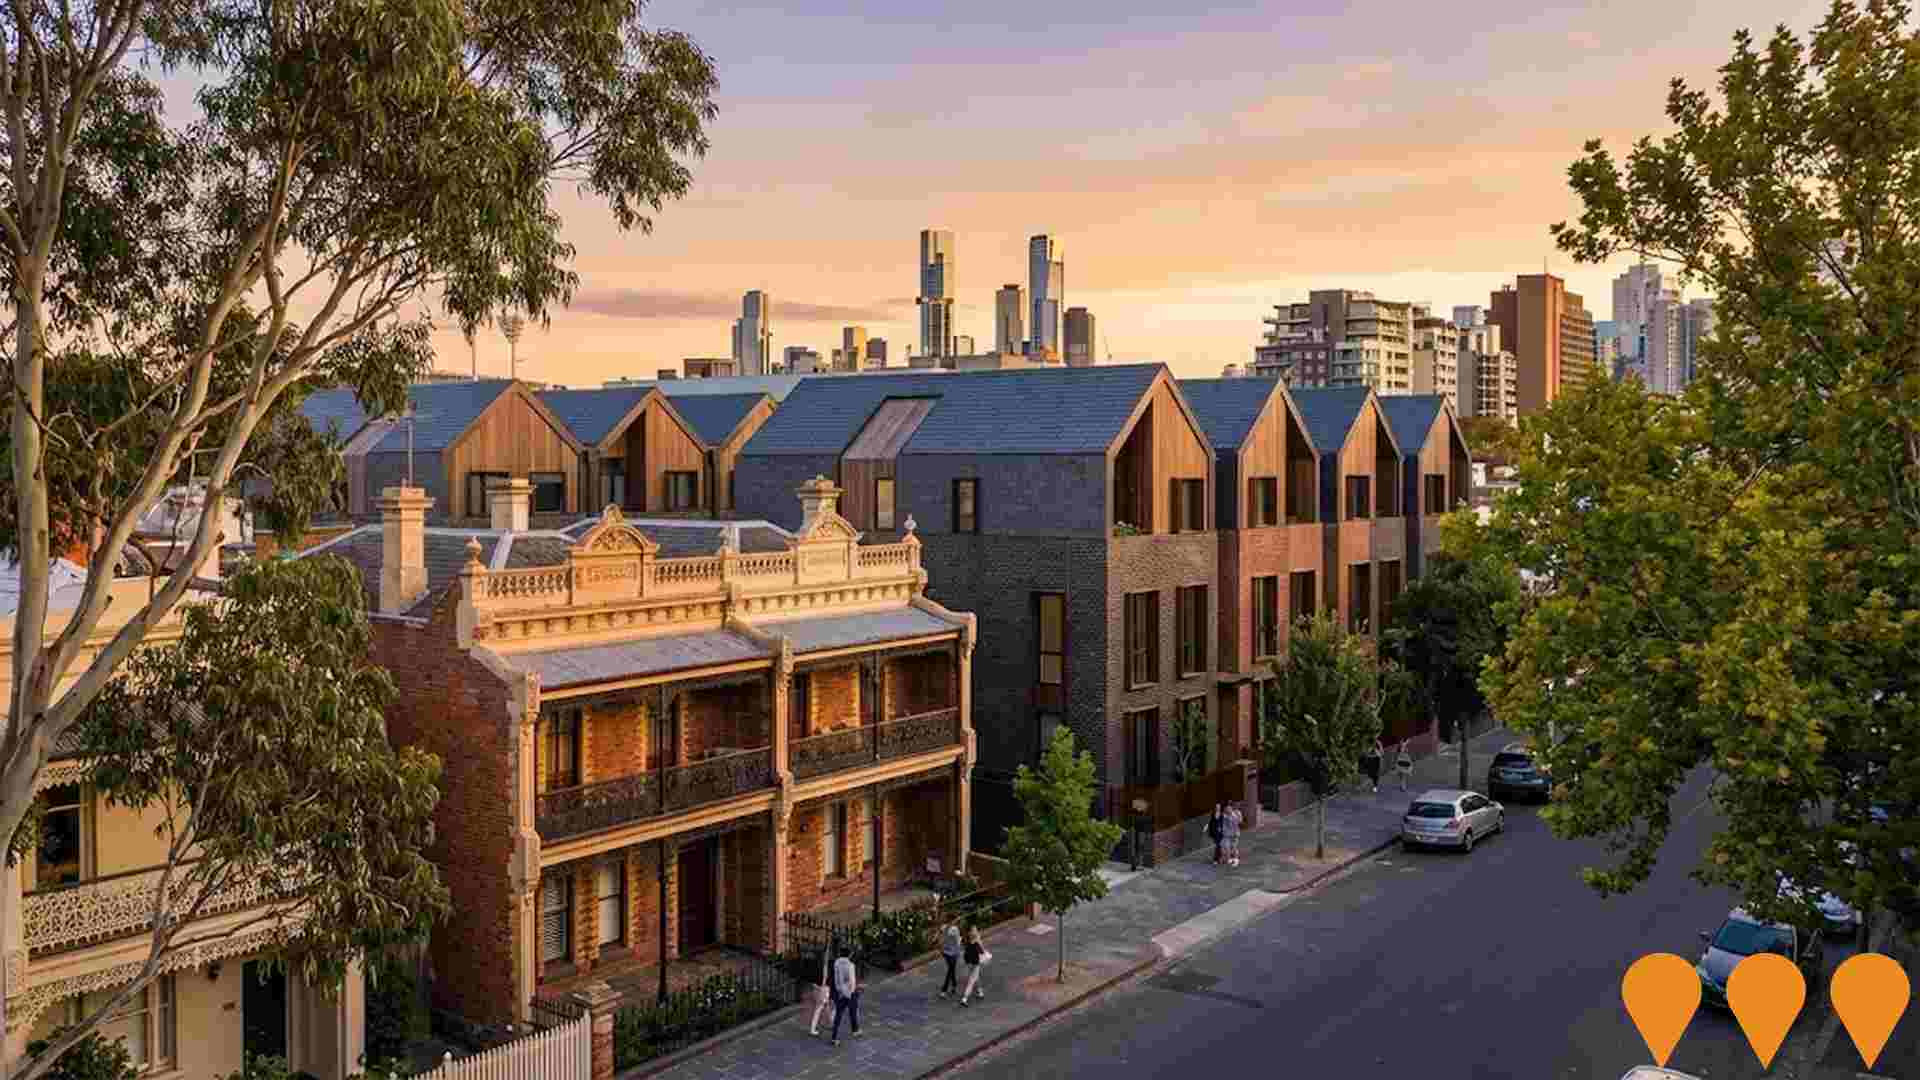
Simpson Street Residential Development
A residential development by Abadeen Group to construct nine three-storey townhouses on a heritage-listed site in East Melbourne. The project involves the partial demolition and redevelopment of the existing structures.
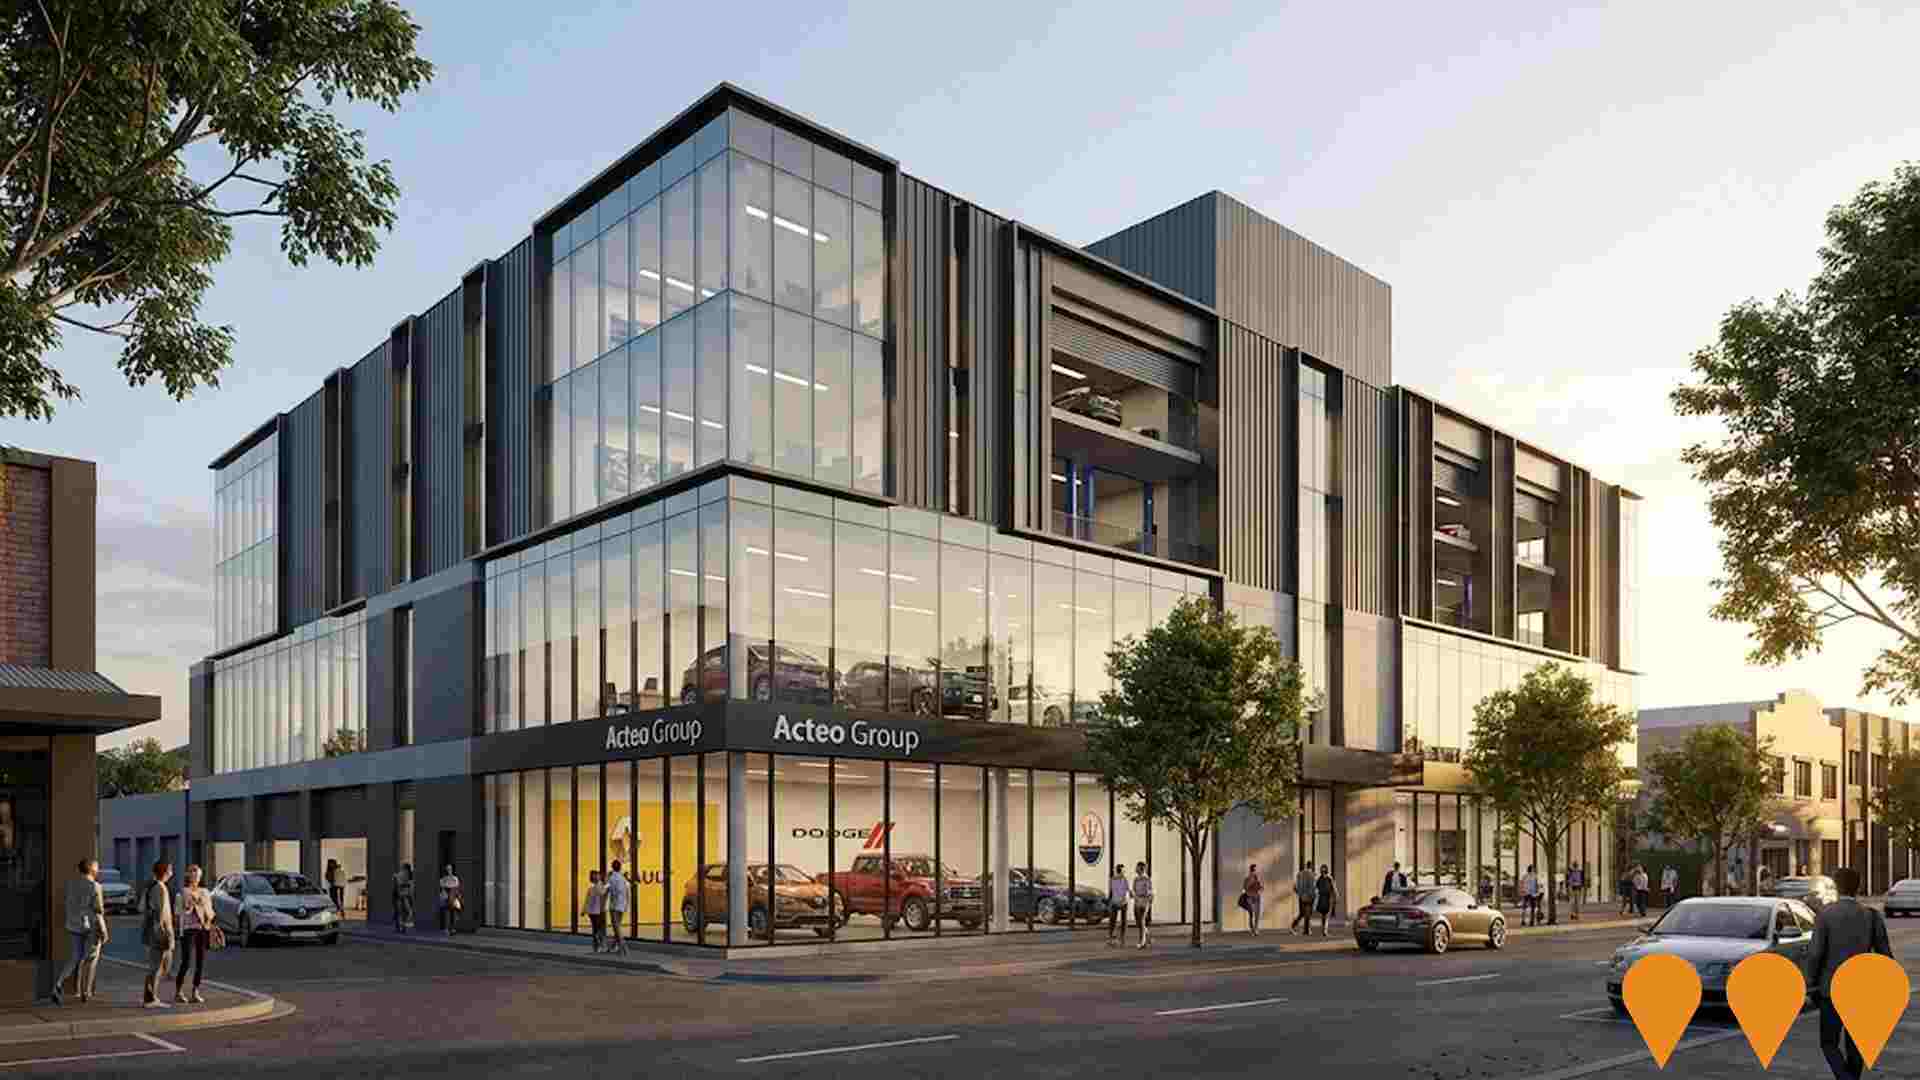
Acteo Group Collingwood Showroom
A four-storey automotive sales and service facility designed by David Earle Architects for Acteo Group (Ateco). The development involves the amalgamation of several sites to create a flagship showroom hub for brands including Maserati, Renault, and Dodge Ram. The facility features ground-floor vehicle displays, upper-level workshops and repair stations, and rooftop vehicle storage, replacing a former pharmacy and industrial warehouse buildings.
Greenline Project
The Greenline Project is a transformational 4km urban renewal initiative creating a continuous promenade along the north bank of the Yarra River (Birrarung). Connecting five precincts from Birrarung Marr to Saltwater Wharf, the first major stage at Birrarung Marr is complete while planning and detailed design advance for the central riverfront sections. Delivered by the City of Melbourne in partnership with design studios ASPECT Studios and TCL, the project integrates native habitat restoration and Indigenous cultural design.
Melbourne Arts Precinct Transformation
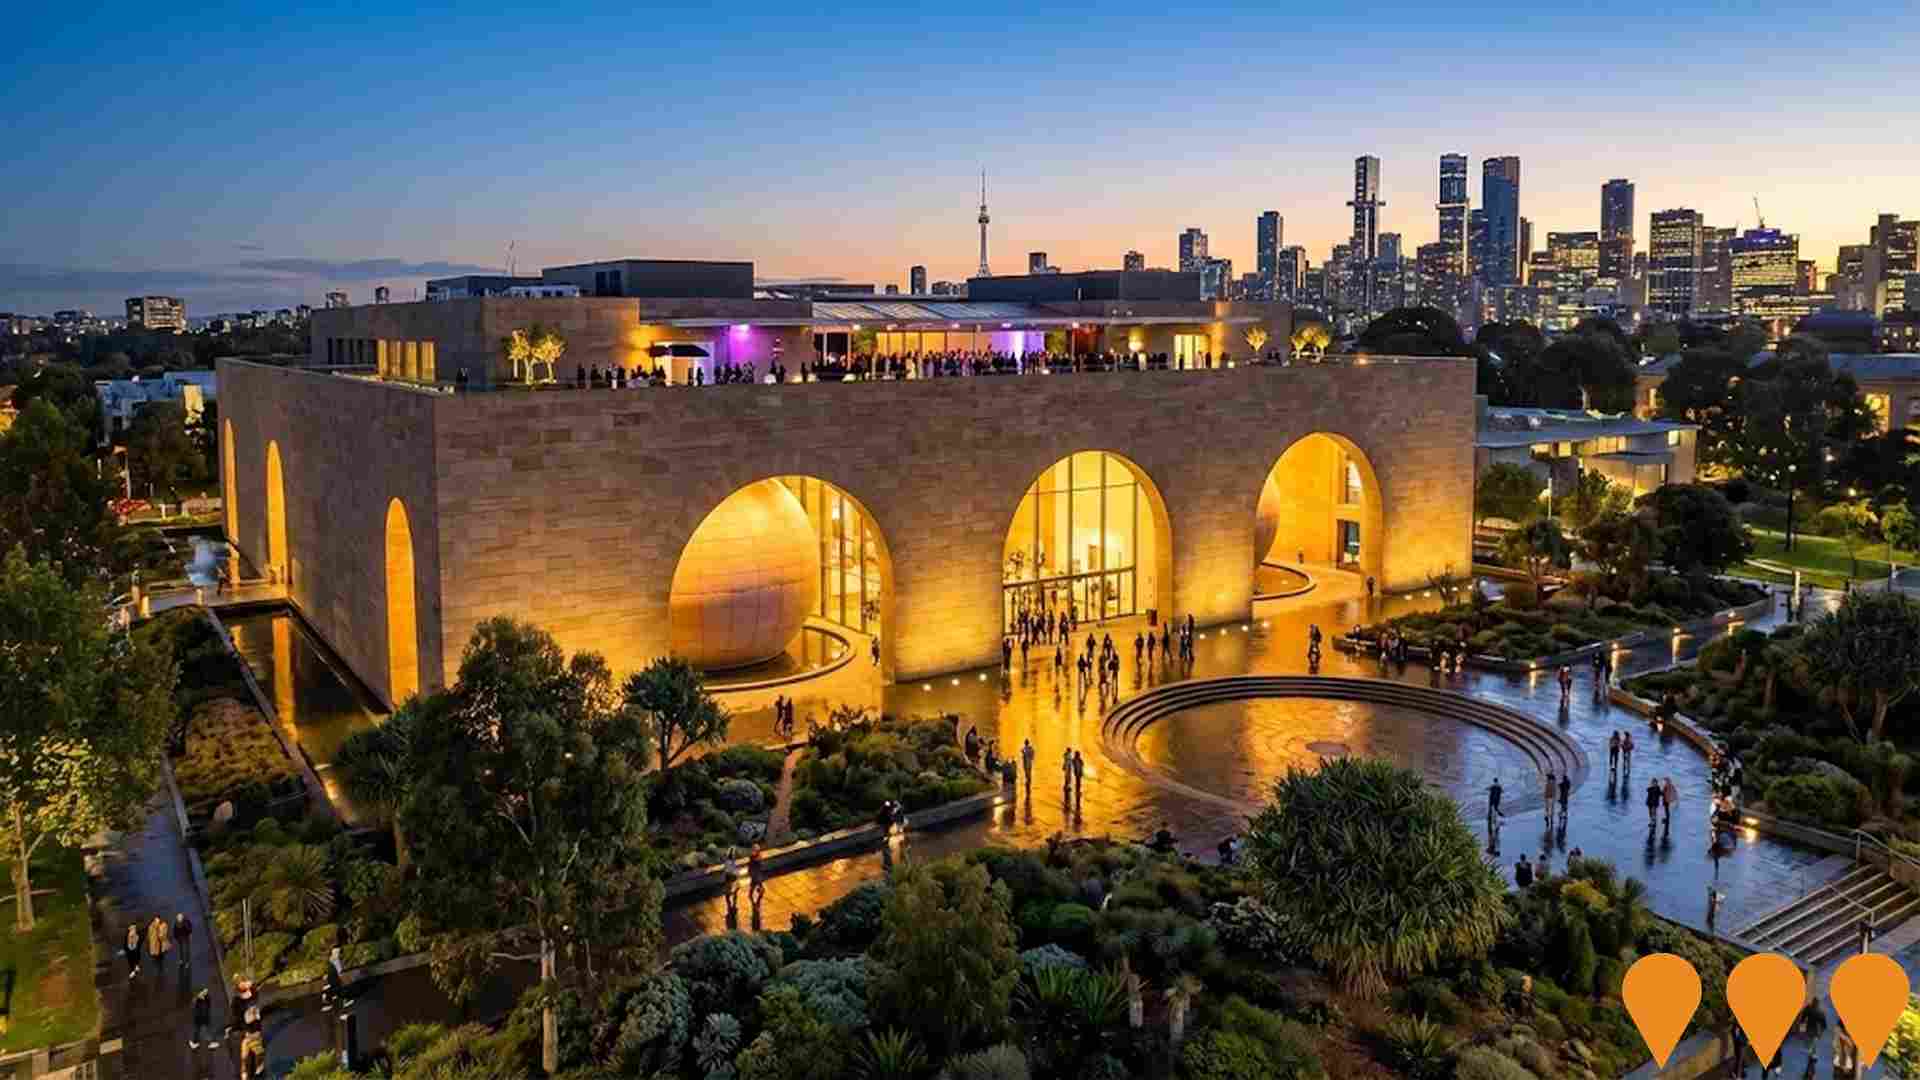
The $1.7 billion Melbourne Arts Precinct Transformation (MAPT) is a landmark cultural redevelopment overseen by MAP Co and delivered by Development Victoria. The project encompasses major upgrades to Arts Centre Melbourne's Theatres Building, the construction of The Fox: NGV Contemporary art gallery, and the creation of Laak Boorndap, an 18,000 sqm elevated urban garden. Construction is actively advancing across deep basement civil packages, with overall completion scheduled for 2028.
90-100 Bridge Road, Richmond
A six-storey mixed-use development featuring 1,639 sqm of specialist medical suites across the first four floors, 1,253 sqm of premium office space, and 89 sqm of ground-floor retail. Designed by Wardle (formerly John Wardle Architects), the project involves the demolition of existing structures to create a contemporary healthcare and commercial hub on an amalgamated 941.7 sqm site. The building includes two basement levels with 19 car parking spaces and extensive end-of-trip facilities. A portion of the office space is designated as a satellite office for the legal firm Arnold, Thomas and Becker.
Fairfield by Marriott and Apartments by Marriott Bonvoy Richmond
A dual-branded hotel development comprising Australia's first Fairfield by Marriott and Apartments by Marriott Bonvoy. The six-storey project includes 100 hotel rooms and 26 apartment-style units with full kitchens. The development also features a restaurant, cafe/bar, and end-of-trip facilities. It is being delivered in two stages, with the apartment component opening in 2026 and the hotel following in 2028.
Ian Potter State Theatre Refurbishment
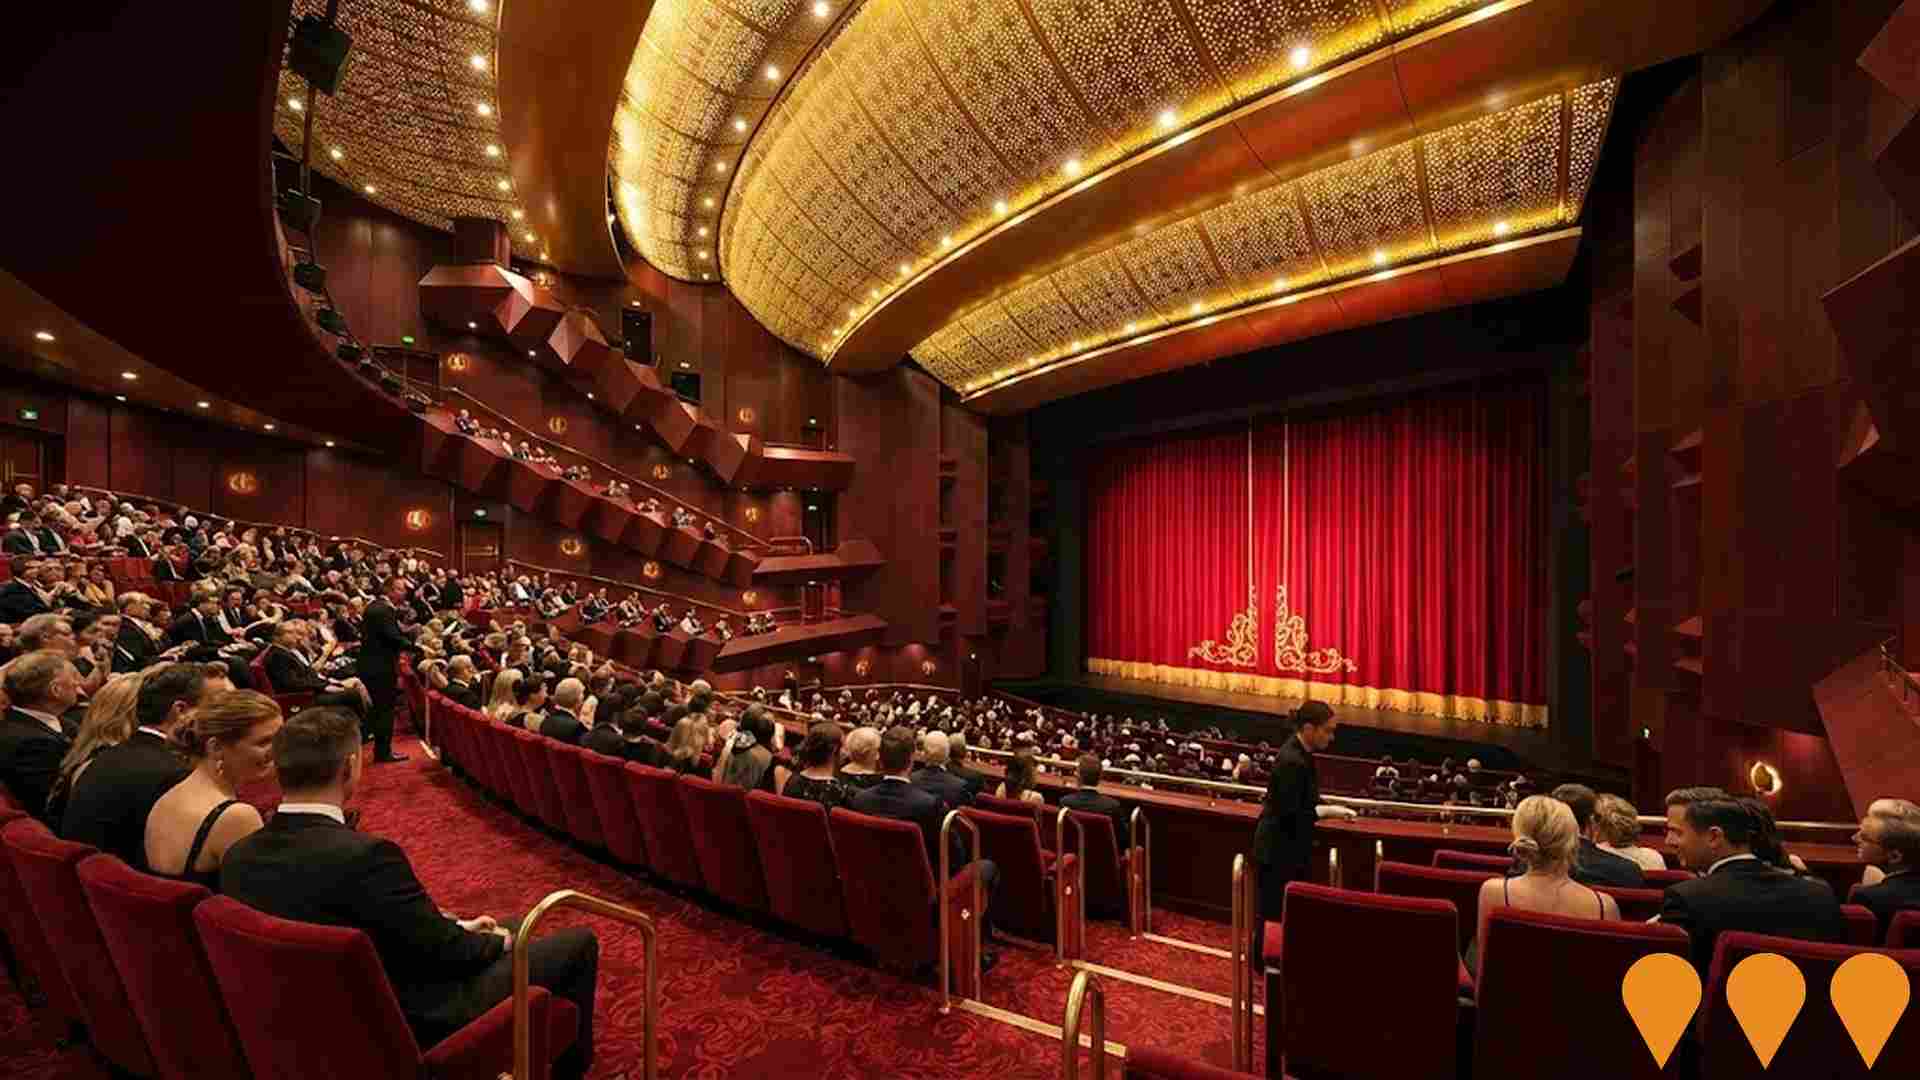
A major refurbishment of the heritage-listed State Theatre at Arts Centre Melbourne, renamed the Ian Potter State Theatre following a philanthropic donation from the Ian Potter Foundation. The first significant upgrade since the venue opened in 1984, the works expand the Theatres Building footprint by 16 percent and include new lifts and accessible seating across all three levels, full replacement of seating, refreshed interiors honouring John Truscott's original design, improved acoustics, new state-of-the-art lighting, sound and broadcast technology, and upgraded heating, cooling and fire protection systems.The project also delivers a doubled-size loading dock, a new flexible rehearsal space the same size as the State Theatre stage with an adjoining function room, a new accessible stage door, two new hospitality outlets opening onto the Laak Boorndap urban garden, and four new wheelchair accessible amenities plus two all-gender amenities in the foyers. Construction commenced in March 2024 with Lendlease as principal contractor and NH Architects leading the design. The theatre is now scheduled to reopen in October 2026, six months ahead of the original schedule, as the first completed milestone of the wider 1.7 billion dollar Melbourne Arts Precinct Transformation. My Fair Lady will be the first major musical to perform in the refurbished venue from November 2026, with The Australian Ballet and Opera Australia returning as resident companies.
3,654 residents of East Melbourne are employed, from a labour force of 3,776. Unemployment sits at 3.2%, with participation at 75.9%. Weighted for its industry mix, the area's sectors are forecast to grow about 7.6% nationally over five years. That reflects industry composition only and makes no allowance for local population growth. The working-day population is estimated at 14,347, about 2.7 times the resident population, so the area draws in more workers than it sends out. Unemployment and labour force come from ABS Small Area Labour Markets, updated quarterly; the industry and occupation profile is from the 2021 Census.
Detail
East Melbourne features an exceptionally skilled labour market with a prominent concentration in professional services, an unemployment rate of just 3.2%, and annual employment growth estimated at 3.4%. There are 3,654 employed residents as of March 2026. The local unemployment rate sits 1.5% below the Greater Melbourne benchmark of 4.8%, while the labour force participation rate reaches an elevated 75.9% compared to 70.1% across Greater Melbourne. Census records show 54.1% of local workers operated from home, though this metric was influenced by Covid-19 restrictions. Resident employment centers predominantly on professional & technical, health care & social assistance, and education & training sectors.
The local economy displays an intense concentration in professional & technical fields, where the employment proportion is 2.1 times the regional level. Conversely, construction represents only 3.8% of the local workforce compared to 9.7% across Greater Melbourne. Hosting 4.2 workers for every resident at the Census, East Melbourne operates as a prominent regional employment hub that draws workers from surrounding communities. AreaSearch assessment of ABS and SALM figures indicates that over the year to March 2026, local employment expanded by 3.4% while the labour force rose by 3.7%, resulting in a 0.3 percentage points uptick in the unemployment rate. By comparison, Greater Melbourne recorded employment growth of 2.1%, a 2.3% rise in the labour pool, and a 0.2 percentage points lift in unemployment. Sector projections from Jobs and Skills Australia as of Mar-26 provide additional context regarding future employment trends across five and ten-year horizons. Nationally, overall jobs are projected to rise by 6.6% over five years and 13.7% over ten years, with distinct variation across industries. When these sectoral projections are weighted against the East Melbourne workforce profile, local employment is projected to expand by 7.6% over five years and 15.2% over ten years (note that this illustrative weighting exercise excludes localized population projections).
Frequently Asked Questions - Employment
Median household income in East Melbourne is $2,345 a week (about $122,000 a year), with median personal income at $1,532 a week. ATO records put median taxable income at $78,554 a year against an average of $144,989. The average runs 85% above the median, a wider spread than most areas and a sign of a concentrated group of high earners. Household income is from the 2021 Census; taxable income is from ATO Taxation Statistics for the latest financial year available, indexed forward using the ABS Wage Price Index.
Detail
Aggregated postcode ATO statistics from AreaSearch for financial year 2023 indicate a median taxpayer income of $78,554 and an average of $144,989 across the East Melbourne SA2, standing well above typical Australian benchmarks and significantly higher than the Greater Melbourne median of $57,688 and average of $75,164. Adjusting for a 9.62% Wage Price Index increase since financial year 2023 yields updated estimates of approximately $86,111 (median) and $158,937 (average) as of March 2026. Data from the 2021 Census shows household, family and personal earnings in the area ranking between the 85th and 97th percentiles nationally.
The primary income bracket encompasses 30.1% of residents earning $1,500 - 2,999 weekly (1,579 residents), mirroring the wider regional proportion of 32.8%. Furthermore, 41.7% of households record weekly incomes exceeding $3,000, underpinning local purchasing capacity. Even with housing costs taking up 15.4% of earnings, disposable income remains in the 85th percentile, placing the area in the 10th decile on the SEIFA income index.
Frequently Asked Questions - Income
East Melbourne had 2,396 occupied dwellings at the 2021 Census, 3% detached houses and 74% apartments. 18% are owned with a mortgage, 54% rented and 28% owned outright. At that Census the median rent was $480 a week and the median mortgage repayment $2,383 a month, a total housing cost higher than 84% of areas nationally. Rent absorbs 20.5% of household income here and mortgage repayments 23.5%. Dwelling stock, tenure and housing costs are 2021 Census measures — the only source that counts dwellings at this boundary size.
Detail
According to the latest Census, the housing landscape in East Melbourne was heavily weighted toward medium and high-density living, with separate houses accounting for 3.2% of dwellings and 96.7% comprised of other dwellings (semi-detached, apartments, 'other' dwellings), contrasting with 67.9% houses and 32.1% other dwellings across Melbourne metro. Outright home ownership stood at 27.5%, trailing the metropolitan baseline, with 18.3% of dwellings owned with a mortgage and 54.2% occupied by renters. Mortgage holders paid a median monthly repayment of $2,383, substantially higher than the Melbourne metro figure of $2,000 and the Australian average of $1,863.
Median weekly rent reached $480, notably above both the Melbourne metro benchmark of $390 and the national figure of $375.
Frequently Asked Questions - Housing
East Melbourne counted 2,396 households at the 2021 Census, an estimated 2,567 today, averaging 1.8 people each. 10% are couples with children, fewer than in 97% of areas nationally, against 36% couples without children. 43% of households are people living alone, and families average 0.9 children. Household and family composition is measured only by the Census, so these are 2021 figures.
Detail
Family households represent 49.9% of all domestic arrangements in East Melbourne, consisting of couples without children at 35.5%, couples with children at 9.6%, and single parent families at 3.3%. Non-family living arrangements account for the remaining 50.1%, with lone person households representing 43.1% and group households making up 7.1%. The area records an average household size of 1.8 people, which is notably lower than the Greater Melbourne benchmark of 2.6.
Frequently Asked Questions - Households
67.4% of adults in East Melbourne hold a university qualification, including 39.8% with a bachelor degree and 21.8% with postgraduate qualifications. A further 6.3% hold a vocational qualification. Qualifications come from the 2021 Census.
Detail
East Melbourne displays remarkable academic qualifications, with 67.4% of residents aged 15+ holding a tertiary degree, markedly outperforming the Australian standard of 30.4% and the VIC benchmark of 33.4%. This solid educational profile underpins a strong capability in professional and knowledge-intensive sectors. Bachelor degrees make up 39.8% of qualifications, postgraduate qualifications constitute 21.8%, and graduate diplomas account for 5.8%. Vocational education accounts for 15.8% of formal credentials among individuals aged 15+, consisting of advanced diplomas (9.5%) and certificates (6.3%). A significant 20.7% of the local population is enrolled in formal education.
Within this cohort, tertiary education comprises 10.6%, primary education accounts for 3.1%, and secondary education represents 2.8%.
Frequently Asked Questions - Education
Schools Detail
Public transport in East Melbourne reaches 49 stops on 46 routes, timetabled for about 22,100 services a week. The typical home sits about 160 m from its nearest stop. Trams carry the largest share of public transport commuters. Households keep an average of 0.6 vehicles. Stop and service counts are built from operators' published GTFS timetables and refresh with each timetable release; vehicle ownership is from the 2021 Census.
Detail
Public transport networks in East Melbourne encompass 49 active transport stops across a combination of lightrail and buses, with 46 distinct routes providing 22,113 weekly passenger trips. Network connectivity is exceptionally high, placing residents an average of 157 meters from their nearest transit stop. Commuting patterns reflect an outward flow from this largely residential enclave, with 46% travelling by car, 28% walking, and 6% using trains. Vehicle availability averages 0.6 per dwelling, trailing regional norms, while 54.1% of workers reported working from home according to 2021 Census data collected under COVID-19 pandemic conditions.
Across all transit routes, service frequency averages 3,159 trips per day, which equates to roughly 451 weekly trips per individual stop.
Frequently Asked Questions - Transport
Transport Stops Detail
69.4% of residents in East Melbourne report no long-term health condition. 3.8% need daily assistance with core activities, and 84.9% hold private health cover. The standardised death rate runs at 5.5 per 1,000 residents. Health conditions, assistance needs and insurance are 2021 Census measures; the death rate comes from current ABS releases.
Detail
Health indicators across East Melbourne are favorable based on AreaSearch analysis of mortality and chronic illness rates, with low incidence of common health issues across younger and older demographics alike. Private health insurance coverage is extensive, encompassing approximately 85% of the total population (4,453 people), compared to 56.7% in Greater Melbourne and 55.7% nationally. Mental health conditions and arthritis represent the most prevalent diagnosed ailments locally, affecting 8.8 and 7.2% of residents respectively, whereas 69.4% reported having no diagnosed health conditions, compared to 72.6% across Greater Melbourne. Health measures among residents aged under 65 exceed standard levels.
Seniors aged 65 and over comprise 23.2% of the local population (1,217 people), above the 15.1% proportion seen across Greater Melbourne, with senior health rankings demonstrating exceptional standing relative to national standards.
Frequently Asked Questions - Health
29.1% of East Melbourne residents were born overseas and 14.9% speak a language other than English at home. The largest reported ancestries are English (27.3%) and Australian (16.7%). Ancestry, language and country of birth are counted only by the Census, so these are 2021 figures.
Detail
East Melbourne exhibits a notable level of cultural diversity, with 29.1% of residents born overseas and 14.9% speaking a language other than English at home. Christianity forms the most widespread religious affiliation, representing 39.7% of the community. Judaism shows a distinctive presence, accounting for 0.7% of the population compared to 1.0% across Greater Melbourne. Regarding parentage, the leading ancestries across East Melbourne are English at 27.3% (exceeding the regional benchmark of 20.1%), Australian at 16.7%, and Irish at 12.8% (above the 6.5% regional proportion). Other ancestries also show distinct representation relative to regional benchmarks, including Scottish at 9.9% (vs 5.6% regionally), Polish at 0.9% (vs 0.8%), and French at 0.7% (vs 0.5%).
Frequently Asked Questions - Diversity
The median resident of East Melbourne is 40. That is 2 years younger than at the 2021 Census. 36.3% of residents are aged 15 to 34. Age cohorts are not raw Census counts: the Census split is re-based to the latest ABS population estimates and state projections.
Detail
The demographic profile of East Melbourne skews older than the surrounding metropolitan area. Based on estimates updated to August 2026, 42.8% of the community consists of young to middle aged adults (25 - 44), compared to 32.1% across Greater Melbourne, while children and young adults (0 - 24) account for only 13.9% versus 30.5% regionally. The estimated median age is 40 as at August 2026, down from 42 at the 2021 Census yet remaining 3 years above the Greater Melbourne median of 37 recorded at the 2021 Census. The proportion of middle aged and young retiree residents (45 - 64) decreased from 24.9% at Census time to an estimated 20.0%.
Long-term forecasts indicate that the 65+ cohort will drive most demographic growth through 2041, increasing by 431 residents (35%) to reach 1,648, while younger age brackets are projected to decline.
Frequently Asked Questions - Age
Data & MethodBoundaries, Sources & Method for East Melbourne
9 of 14 data sections on this page were updated within the last 12 months — the newest current to Sep 2026.
Everything is aggregated to the SA2 boundary shown above, on a 2021 Census baseline. Only 3 sections — housing, households and cultural diversity — still wait on the 2026 Census.
The ledger — source, cycle and currency by section
| Section | Source & update cycle | Currency |
|---|---|---|
| Updated within the last 12 months 9 sections | ||
| Population | ABS, GNAF, Geoscience Australia Annual (ABS ERP) | Aug 2026 2 months ago headline measures · 2021 Census baseline |
| Re-based to the ABS Estimated Resident Population (June 2025 release) and updated with new dwellings from GNAF address data. Current to Aug 2026, with the 2021 Census supplying the small-area baseline. | ||
| Age profile | ABS, Geoscience Australia, State governments Annual | Aug 2026 2 months ago headline measures · 2021 Census baseline |
| Age cohorts are re-based to the latest ABS population estimates and state projections, current to Aug 2026. Each cohort is held as a Census baseline and a current estimate. | ||
| Development & approvals | ABS, GNAF Monthly (ABS approvals) | Aug 2026 2 months ago headline measures · Jul 2026 baseline |
| Property sales & rents | Valuer General, Rental Board, ABS Weekly sales, quarterly rents | Sep 2026 last month all 21 measures |
| Sales from the state Valuer General register, refreshed weekly, and rents from quarterly rental bond lodgements. Both are read live each time this page loads, current to Sep 2026. | ||
| Infrastructure projects | Infrastructure Australia, State agencies, Local governments Daily | May 2026 5 months ago all 10 projects tracked here |
| Project pipeline maintained continuously from Infrastructure Australia, state agencies, local government and public announcements. Records are added and revised daily; this area was last updated May 2026. | ||
| Employment | ABS, DEWR, JSA Quarterly (ABS SALM) | Mar 2026 7 months ago headline measures · 2021 Census baseline |
| Unemployment and labour force from ABS Small Area Labour Markets, current to Mar 2026. The growth outlook applies Department of Employment (now Jobs and Skills Australia) forecasts for all 19 industry divisions to the local industry mix, so it measures sector composition rather than local expansion and makes no allowance for population growth. Job demand comes from the same agency via its Internet Vacancy Index; industry and occupation structure from the 2021 Census. | ||
| Education | ABS, ACARA Annual (ACARA) | Sep 2026 last month headline measures · 2021 Census baseline |
| Transport | ABS, State Transport Departments Each timetable release | Jul 2026 3 months ago headline measures · 2021 Census baseline |
| Services & amenities | Provider directories, ACECQA Continuous | Sep 2026 last month all 14 measures |
| Annual and financial-year sources 2 sections | ||
| Income | ABS, ATO Annual (ATO) | FY 2023 3 years ago headline measures · 2021 Census baseline |
| ATO taxable income statistics for FY 2023, indexed forward using the Wage Price Index. Census household income provides the distribution detail. | ||
| Health | ABS, ATO Annual | 2024 2 years ago headline measures · 2021 Census baseline |
| Census-measured — next update: 2026 Census 3 sections No more current small-area source exists for these, so they are labelled as Census-measured rather than implied to be current. | ||
| Housing | ABS 5-yearly (Census) | 2021 Census next update 2026 all 30 measures |
| Households | ABS 5-yearly (Census) | 2021 Census next update 2026 all 18 measures |
| Cultural diversity | ABS, Geoscience Australia 5-yearly (Census) | 2021 Census next update 2026 all 44 measures |
"Currency" is the most recent release feeding that section. Where the Census supplies the structural baseline underneath a current headline figure, the row says so.
How the numbers are built
Population
The Census provides the small-area baseline, aggregated from mesh blocks to this boundary. It is then re-based to the ABS Estimated Resident Population (June 2025 release), and new dwellings built since Census night are counted from address data. The headline figure is therefore a current estimate for Aug 2026, not a 2021 count (4,896 at the 2021 Census → 5,246 now). Annual growth rates are compound (CAGR), not simple averages.
Age profile
Cohort shares are not raw Census counts. Every cohort is held as a pair — the Census baseline and a current estimate — and the split is re-based using ERP and state population projections, current to Aug 2026. Median age is the Census median plus modelled change since. Charts that show both are labelled "2021 Census vs Current Estimate".
Property sales
Sourced from the state valuation authority's sales register — current, not Census, and refreshed weekly. Medians are calculated from settled transactions in the period shown; periods with very low transaction counts are flagged or suppressed, because a handful of sales can move a median substantially.
Rents
Derived from state rental bond lodgement data, by dwelling type and bedroom count. Bonds are lodged at the start of a new tenancy, so this reflects new lettings, not the whole rented stock.
Development & infrastructure
Building approvals come from current ABS releases; development applications are collected from council and state planning portals; the infrastructure pipeline is compiled from Infrastructure Australia and local government sources. Applications are matched to this boundary by address or coordinates, so very recent lodgements may not yet appear.
Employment & income
Industry and occupation structure comes from the Census, but the headline labour-market indicators do not. Unemployment and labour force are derived from ABS Small Area Labour Markets (quarterly). The employment outlook applies Department of Employment forecasts for all 19 industry divisions to this area's own industry mix (the agency is now Jobs and Skills Australia), as does the Internet Vacancy Index used for job demand. Because it is weighted on industry composition alone, that outlook carries no allowance for local population growth — in fast-growing areas the real rise in local jobs will typically be higher. Income combines Census household income with ATO taxable-income statistics for FY 2023, indexed forward using the Wage Price Index.
Education, transport & amenities
School enrolments, ICSEA and performance come from ACARA's current release, not the Census. Public transport stops and service frequency are derived from GTFS timetable feeds published by state transport departments. Services and amenities are proximity and count scores built from provider directories, refreshed on their own cycle. The Census contributes only the travel-to-work and qualification measures.
Rankings and benchmarks. Where we rank this area, the comparison set is every area of the same boundary type — suburbs against suburbs, SA2s against SA2s. Benchmarks compare this area against its greater capital city region and the national figure for the same measure and period.
Limits worth knowing. Small areas carry larger error margins, and the ABS introduces small random adjustments to Census counts to protect confidentiality — so totals may not sum exactly. Estimates re-based from regional data describe the area's expected trajectory, not a direct count of it. Figures are indicative for research and are not financial, planning or valuation advice.
Cross-check us. The Census baseline for this boundary is at ABS 2021 Census QuickStats (206041119). QuickStats reports 2021 only — the figures on this page are more current wherever the ledger shows a later date.