Chart Color Schemes
This analysis uses ABS Statistical Areas Level 2 (SA2) boundaries, which can materially differ from Suburbs and Localities (SAL) even when sharing similar names.
SA2 boundaries are defined by the Australian Bureau of Statistics and are designed to represent communities for statistical reporting (e.g., census and ERP).
Suburbs and Localities (SAL) represent commonly-used suburb/locality names (postal-style areas) and may use different geographic boundaries. For comprehensive analysis, consider reviewing both boundary types if available.
est. as @ -- *
ABS ERP | -- people | --
2021 Census | -- people


Curious about local property values? Filter the chart to assess the volume and appreciation (including resales) trends and regional comparisons, or scroll to the map below view this information at an individual property level.


Find a Recent Sale

Sales Detail
Light has an estimated 10,646 residents, up from 9,797 at the 2021 Census — a change of 849 people, or 8.7%. Growth has averaged 1.6% a year over five years. 170 new addresses have been validated here since Census night. Interstate and internal migration accounts for 74.0% of that increase. Fewer than ten people live on each square kilometre, across a boundary that takes in surrounding rural land. Population is estimated from ABS Estimated Resident Population releases and GNAF address data, re-based from the 2021 Census and updated annually.
Detail
According to research conducted by AreaSearch, Light has a resident count of approximately 10,646 as of Aug 2026. This marks an expansion of 849 individuals (8.7%) relative to the 2021 Census tally of 9,797 residents. This demographic movement incorporates the ABS June 2025 estimated resident population figure of 10,631 alongside 170 validated new addresses identified following the Census. The resulting population density stands at 9.6 persons per square kilometer, ensuring a spacious living environment. Expanding at 8.7% post the 2021 census, Light outpaced the Rest of SA (6.2%) and the wider SA4 region, positioning it at the forefront of regional growth.
Interstate migration served as the primary growth engine, accounting for roughly 74.0% of recent population additions, with natural increase and overseas arrivals also contributing positively. Projections prepared by ABS/Geoscience Australia (published in 2024 using 2022 baseline figures) are utilized by AreaSearch across SA2 locations. Where SA2 coverage is absent, or for periods extending beyond 2032, figures from the 2023 SA State Government's Regional/LGA age-cohort projections (built on 2021 data) are integrated via a weighted aggregation framework translating LGA growth to the SA2 level. Driven by prevailing demographic momentum, population growth is projected to exceed the median for national non-metropolitan zones, with the district expected to add 1,933 persons by 2041 under latest annual ERP data, representing a cumulative 18.0% gain across the 16 years.
Frequently Asked Questions - Population
238 new dwellings have been approved in Light over the past five years, an average of 47 a year. That places the area in the 72nd percentile for residential development activity nationally, about 4 approvals per 1,000 residents a year. Of the 48 dwellings approved in the latest reporting year, 100% were detached houses and the rest townhouses or apartments. Figures come from ABS building approvals aggregated to this SA2 boundary and are updated monthly as the ABS releases them.
Detail
Residential building approvals in Light have averaged roughly 47 dwellings annually, accumulating to 238 residential approvals throughout the prior 5 financial years (between FY-22 and FY-26). Over this same span (between FY-22 and FY-26), the area recorded an average intake of 3.4 new residents per home constructed, creating a notable supply shortfall that typically heightens buyer competition and drives prices upward, with residential construction costs averaging $333,000 per dwelling. Furthermore, the present financial year has registered $29.0 million in commercial project approvals, demonstrating robust commercial sector development. Per capita building activity in Light sits 14.0% below the Rest of SA benchmark, placing the district in the 58th percentile across all assessed locations nationwide.
Recent construction has centered exclusively on separate houses, preserving a spacious low-density neighborhood fabric well-suited to family buyers seeking room. A ratio of roughly 261 people per dwelling approval characterizes this emerging market. Projections derived from the latest AreaSearch quarterly estimate indicate Light will gain 1,918 residents through to 2041. If residential construction volumes remain at current levels, housing completions may fall short of demographic expansion, likely driving stronger buyer competition and reinforcing upward price momentum.
Frequently Asked Questions - Development
Development applications around Light
Loading development applications…
| Lodged | Address | Description | Type | Distance | Status |
|---|
SOURCE: Planning portals and council registers, compiled by AreaSearch. Distance & bearing measured from the suburb midpoint.
AreaSearch tracks 3 current infrastructure and development projects inside Light, worth an estimated $63 million. A further 93 sit in the immediately surrounding suburbs, taking the tracked pipeline within reach of the area to $24.1 billion. 43 are already under construction and 49 are due for completion within three years. The pipeline spans communities, precincts & urban renewal, residential development and transport & logistics. Records are compiled from Infrastructure Australia, state agencies, council planning portals and public announcements, reviewed and updated daily, then ranked by proximity, construction stage, completion horizon and project scale.
Detail
Local economic and social outcomes are substantially shaped by capital works, strategic planning schemes, and regional infrastructure investments. A total of 19 major initiatives have been documented by AreaSearch as having potential influence across the district. Prominent developments include the Freeling West Code Amendment, the Barossa Lifestyle (Barossa Co-op Redevelopment), the Barossa Growth and Infrastructure Investment Strategy, and the Sovereign Estate, with priority projects detailed below.
Professional plan users can use the search below to filter and access additional projects.
INFRASTRUCTURE SEARCH
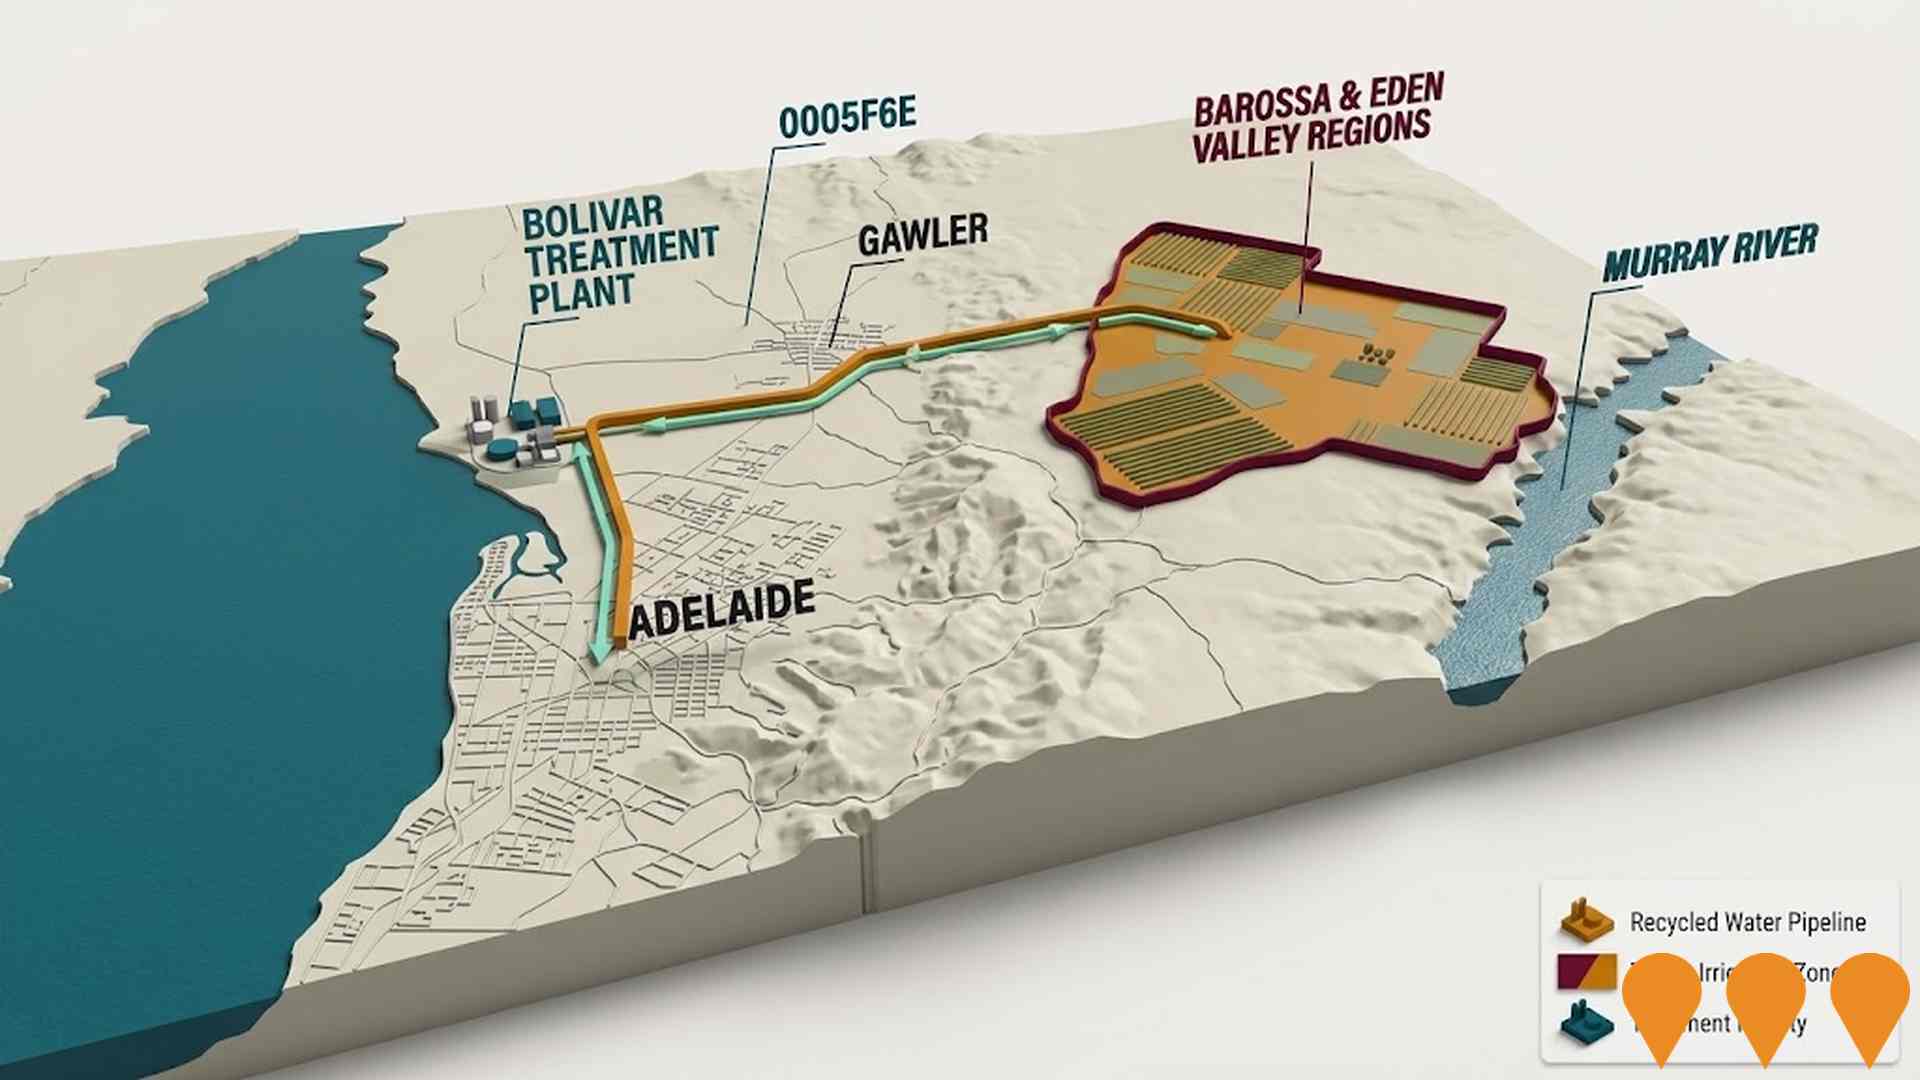
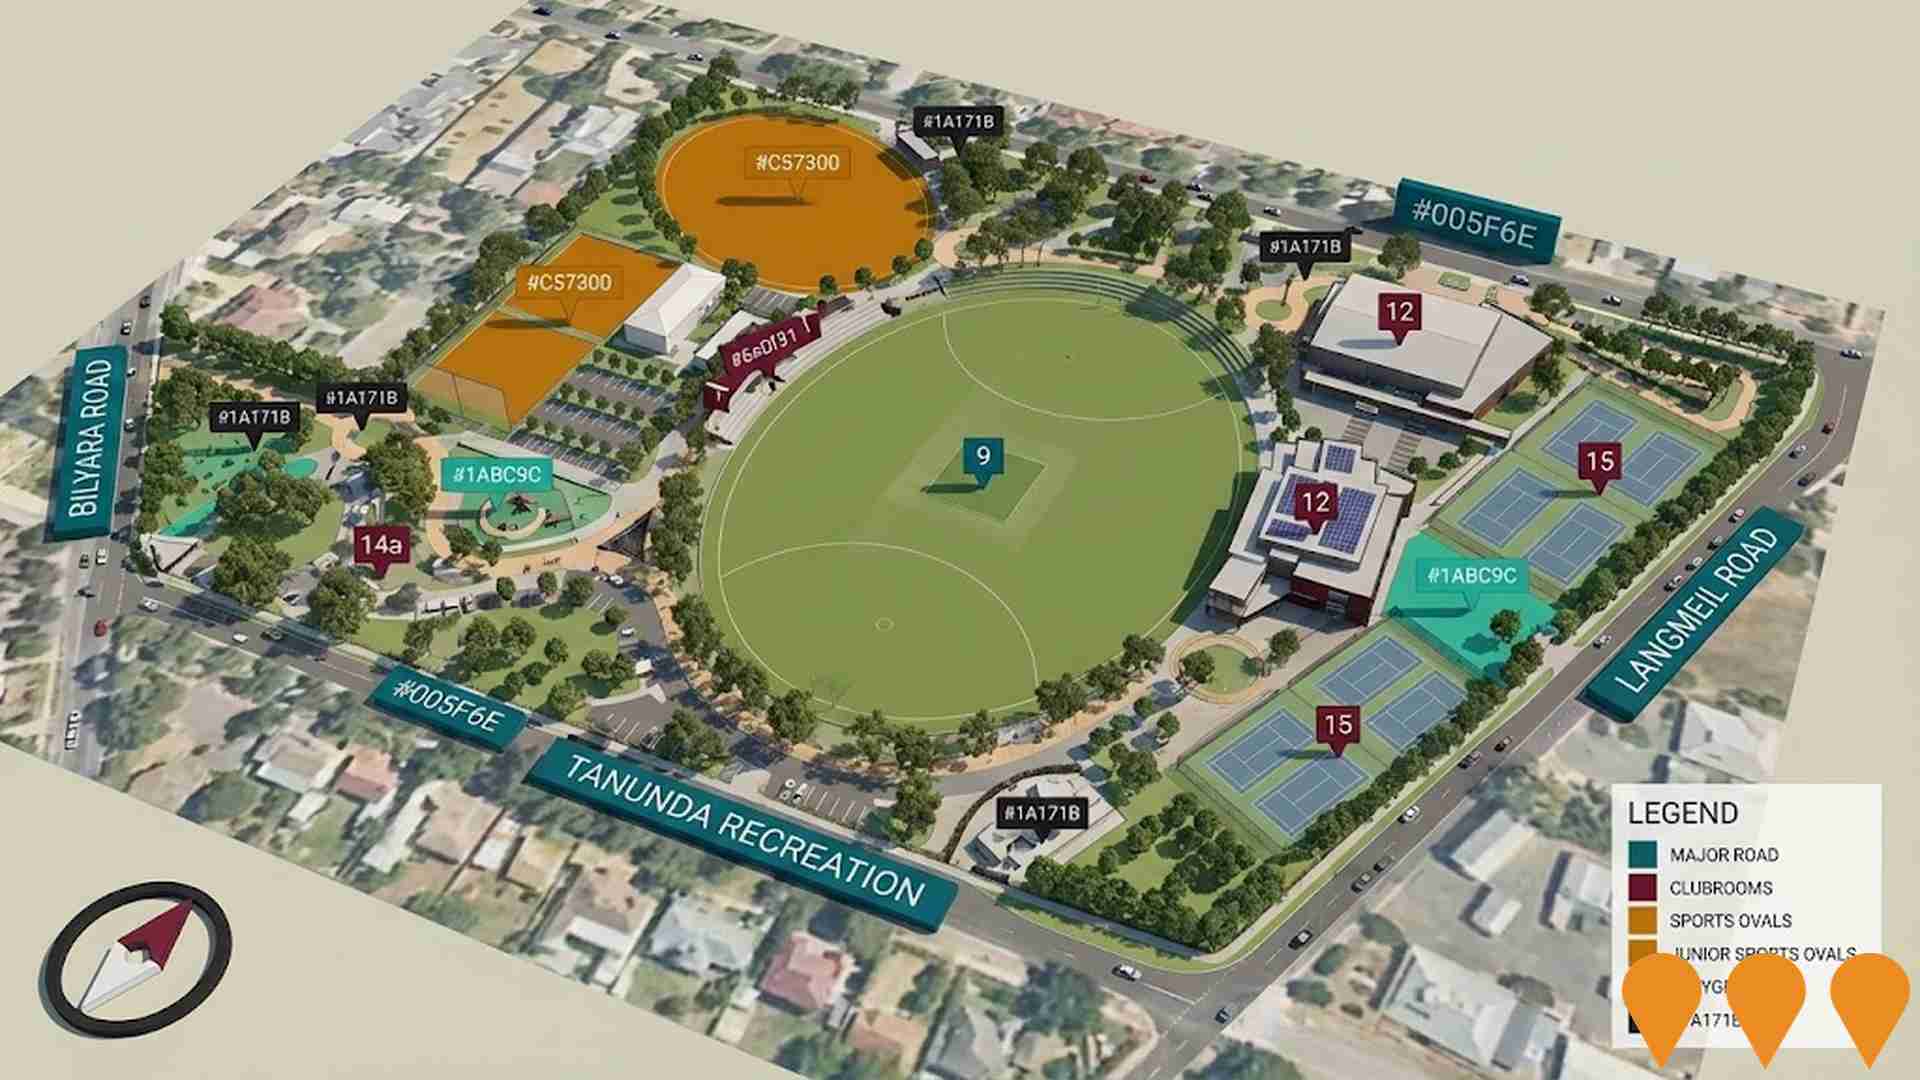
 Denotes AI-based impression for illustrative purposes only, not to be taken as definitive under any circumstances. Please follow links and conduct other investigations from the project's source for actual imagery. Developers and project owners wishing us to use original imagery please Contact Us and we will do so.
Frequently Asked Questions - Infrastructure
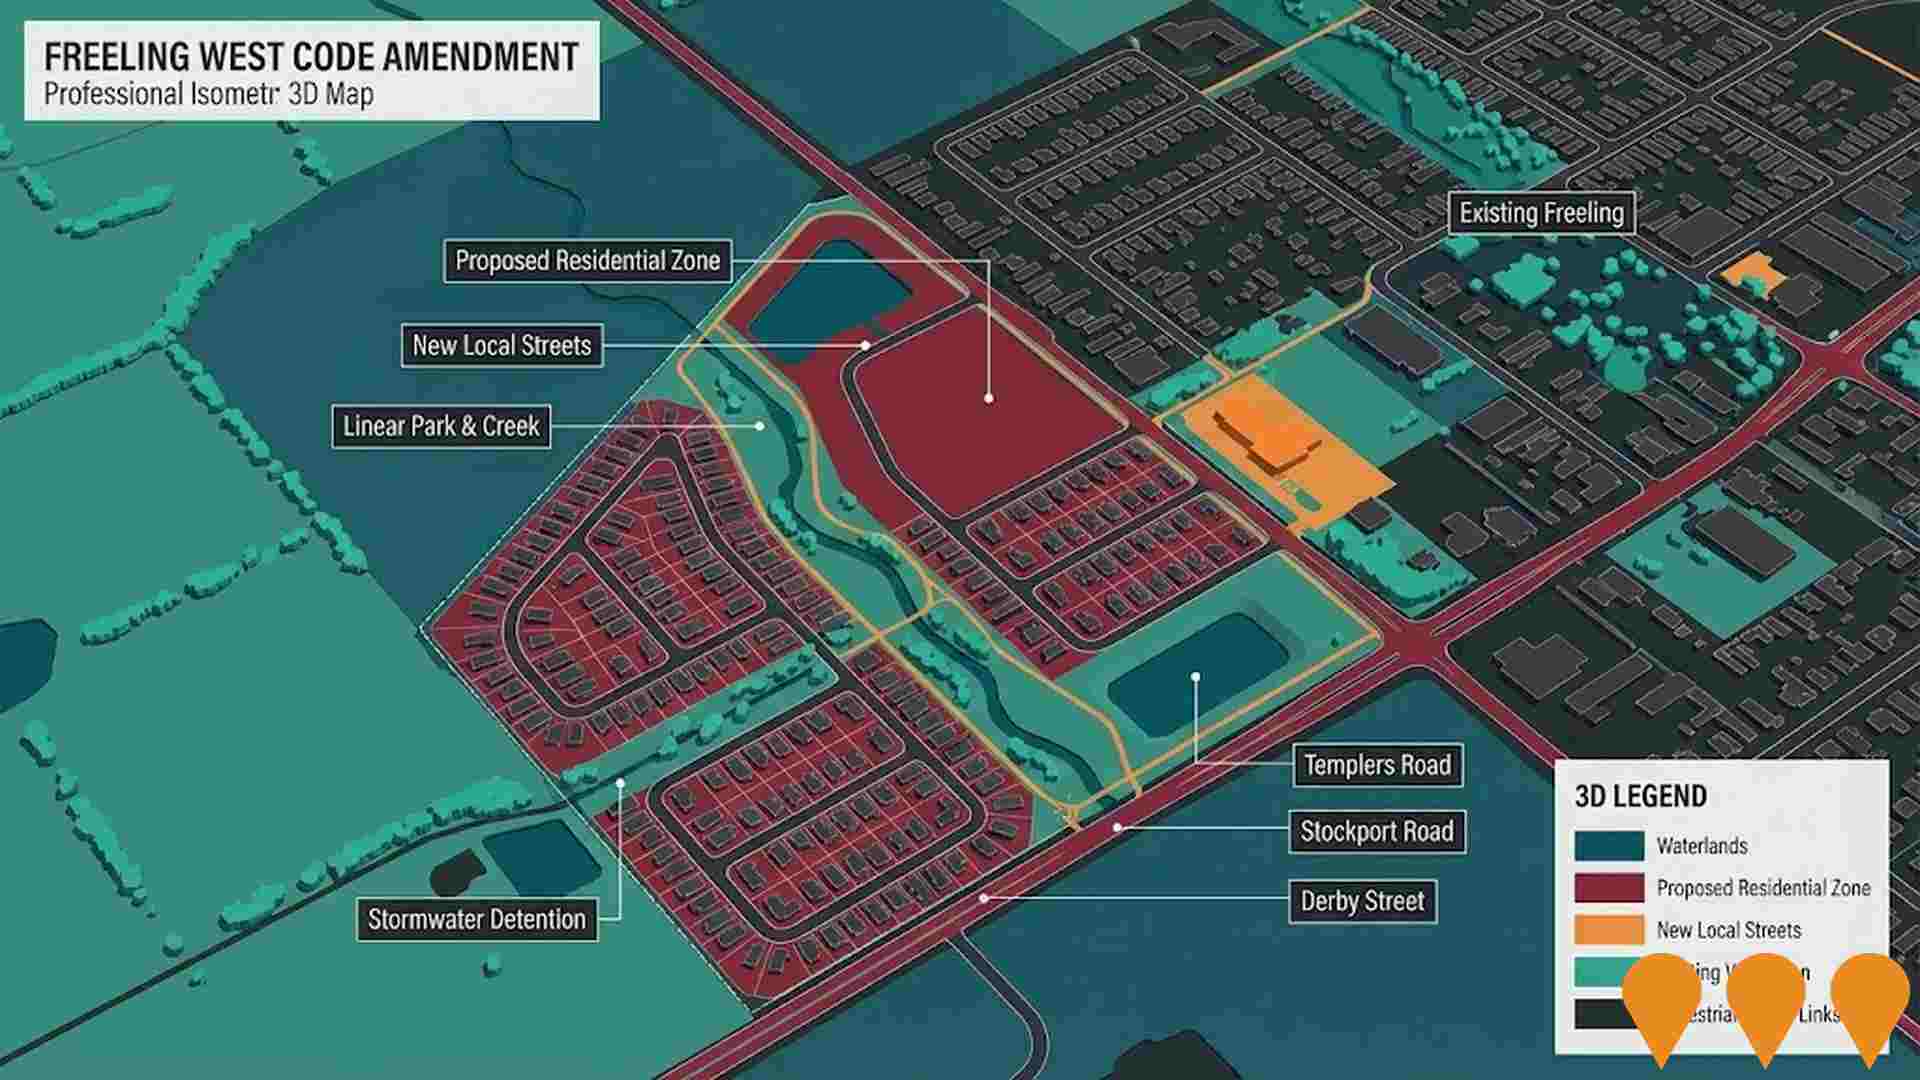
Freeling West Code Amendment
Code Amendment to rezone approximately 20 hectares of Rural Zoned land on the western side of Freeling, between Templers Road and Stockport Road adjacent to Derby Street, to the Suburban Neighbourhood Zone. The amendment is intended to enable a new low density residential neighbourhood of around 185 to 250 housing allotments, with a concept plan showing new local streets, linear open space along the existing creek, pedestrian and cycle links, stormwater detention areas and upgraded access to Templers Road and Stockport Road.The amendment was initiated on 21 March 2024, and the first round of public consultation ran from 1 October 2025 to 26 November 2025. It is now progressing to the Determination stage. Walton Rural Pty Ltd is the proponent (designated entity), with MasterPlan SA engaged to prepare the amendment and lead community consultation.
Kidman Rise
Kidman Rise is a residential land estate on the northern edge of Kapunda, offering large lots ranging from 437m2 to 1045m2, oriented for northern sun. Situated an hour from Adelaide, between Clare and Barossa valleys. The land has historical connection to Sidney Kidman.
George Street Estate, Williamstown
George Street Estate is a proposed 6.22 hectare residential subdivision on Lot 9 George Street in Williamstown, within The Barossa Council area. The land has been marketed as one of the last major land development opportunities in the town, with concept plans showing a new house and land estate subject to council approval and planning consent. The site has been sold but remains listed as in planning, with no confirmed named developer; SA Homes & Acreage has acted as the selling and marketing agent for the land.
Barossa Lifestyle (Barossa Co-op Redevelopment)
A redevelopment project transforming the 'Barossa Home Living' building in Nuriootpa into 'Barossa Lifestyle', a modern retail store. The project aims to bring together top brands, diverse products, and enhance customer experience. Full completion is expected by June 2025.
Barossa Growth and Infrastructure Investment Strategy
The Barossa Council's 30-year Growth and Infrastructure Investment Strategy coordinates land use planning, infrastructure priorities and growth management across the Barossa while protecting the region's wine, food, tourism, heritage and lifestyle character. Council authorised the Phase 1 strategy on 18 March 2025 after consultation. Phase 1 focuses on residential infill in Nuriootpa, Tanunda and Angaston, infrastructure priorities and housing supply, while some tourism and employment proposals continue to Phase 2 investigations. The related Concordia Growth Area is now a major delivery focus after State Government finalisation of the Code Amendment and concept plan in September 2025, with infrastructure planning for about 12,000 homes and more than 30,000 residents over 30 years.
Sovereign Estate
A residential land release development in Tanunda offering various sized allotments for new homes within walking distance to the town centre and surrounded by vineyards.
Gembrook Estate
A significant premium land release master-planned community in Tanunda, offering spacious, title-ready allotments. It boasts panoramic views of the Barossa Ranges and is located near Faith Lutheran Private School, minutes from world-class wineries. Stages 1 and 2 are nearly sold out, with Stages 3 & 4 now available.
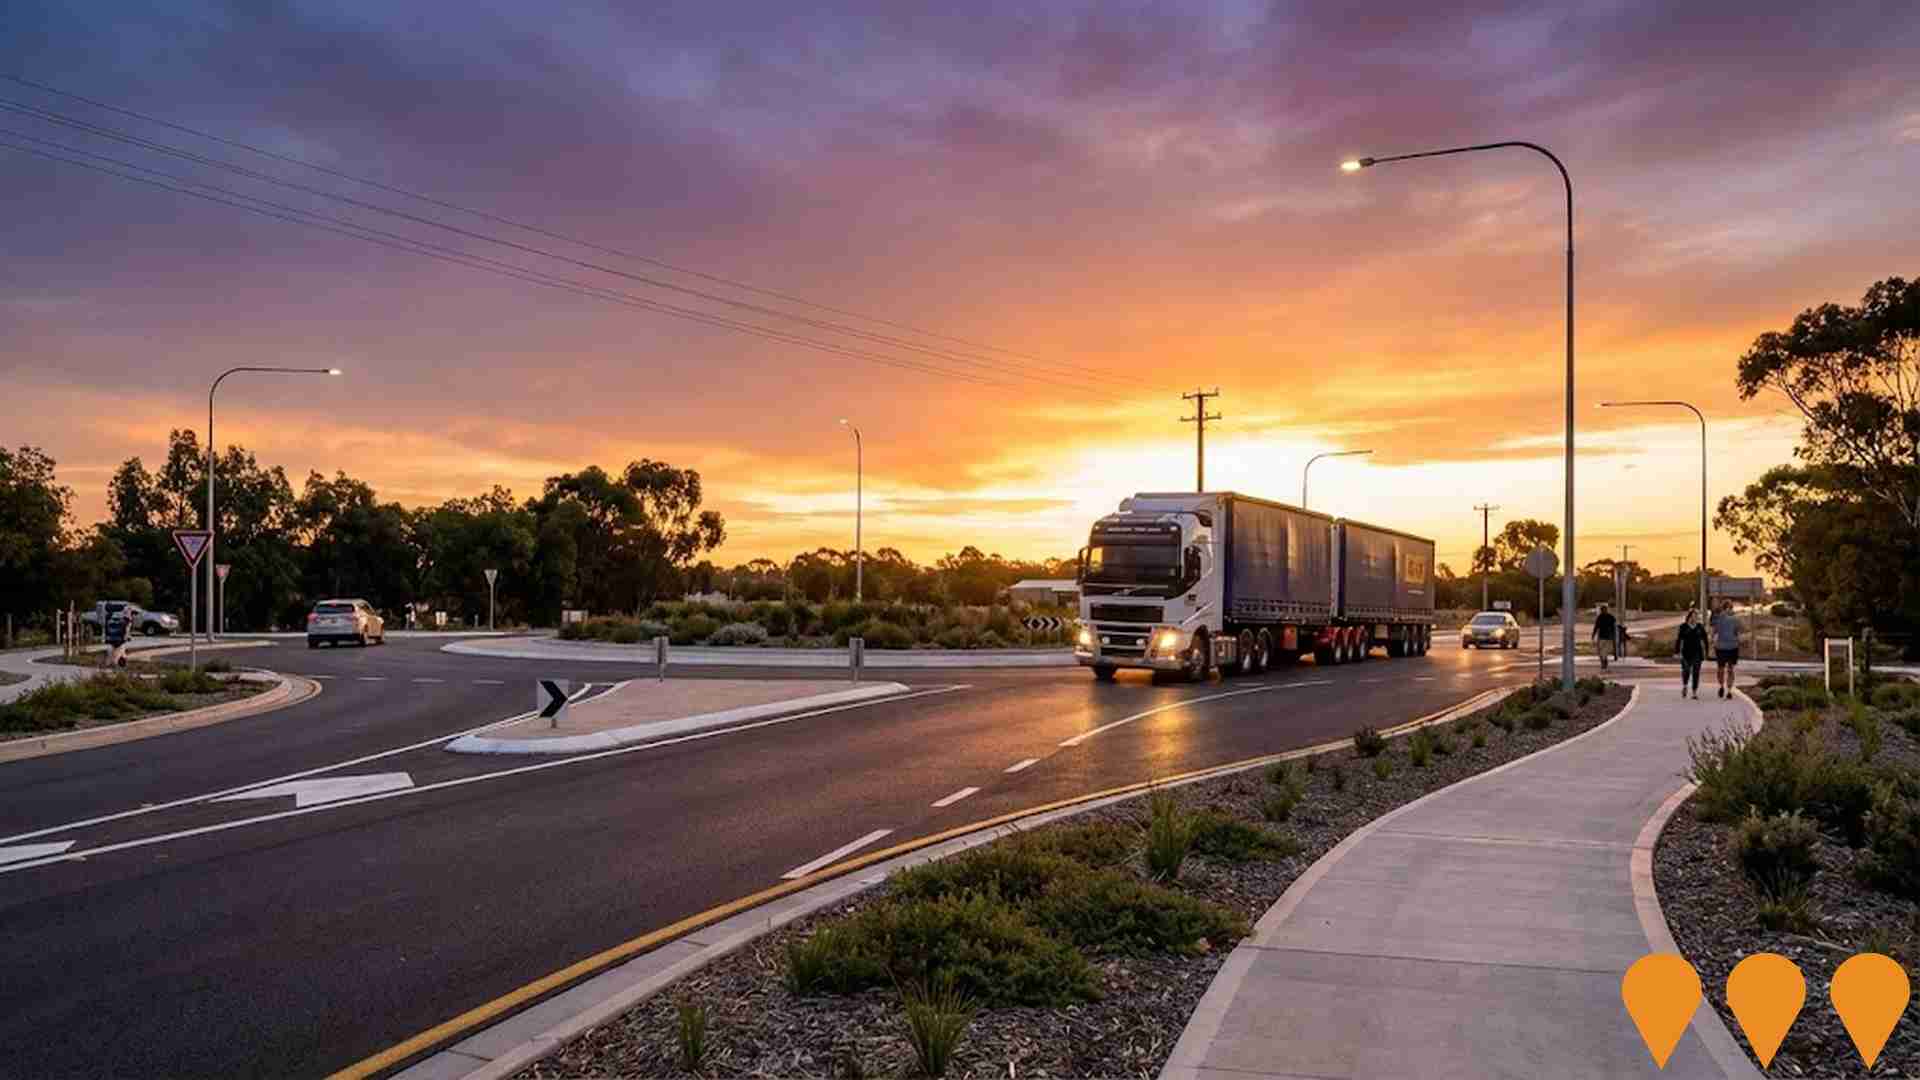
Kroemer Crossing Roundabout Upgrade
Improvement of safety and access at Kroemer's Crossing, Tanunda, by installing a roundabout to improve safety for all road users and allow greater freight access to surrounding businesses. This $6 million project was funded by the Australian and South Australian Governments, The Barossa Council, and Pernod Ricard Winemakers Pty Ltd.
5,507 residents of Light are employed, from a labour force of 5,653. Unemployment sits at 2.6%, with participation at 64.8%. Weighted for its industry mix, the area's sectors are forecast to grow about 5.1% nationally over five years. That reflects industry composition only and makes no allowance for local population growth. The working-day population is estimated at 9,527, about 89% of the resident population, so more people leave the area for work than travel in. Unemployment and labour force come from ABS Small Area Labour Markets, updated quarterly; the industry and occupation profile is from the 2021 Census.
Detail
The local labour market features an even mix of professional and industrial occupations, underpinned by a prominent manufacturing presence, a minimal jobless rate of 2.6%, and 3.8% estimated jobs growth over the prior year. In March 2026, 5,507 residents were actively employed, while unemployment sat 2.9% under the Regional SA level of 5.5%, supported by an elevated labour participation rate of 64.8% (versus 58.3% for Regional SA). Census returns showed a modest 10.6% of workers operating from home, a metric that may have experienced Covid-19 lockdown influences. The primary employment sectors for residents are manufacturing, health care & social assistance, and agriculture, forestry & fishing.
Specialization is particularly pronounced in manufacturing, where local workforce representation is 1.6 times the regional benchmark. Conversely, agriculture, forestry & fishing accounts for only 11.0% of local jobs, trailing the 14.5% seen across Regional SA. When comparing Census place-of-work counts with resident totals, the district displays a relatively small base of internal employment opportunities. AreaSearch evaluation of ABS and SALM metrics indicates that over the 12-month period to March 2026, resident employment expanded by 3.8% against a 3.5% workforce expansion, lowering the unemployment rate by 0.3 percentage points. In comparison, Regional SA observed a 1.2% employment rise, a 2.6% increase in the labour pool, and a 1.4 percentage points rise in unemployment. Long-term outlooks from Jobs and Skills Australia (dated Mar-26) provide context on potential sector trajectories. Nationally, total employment is projected to expand by 6.6% across five years and 13.7% across ten years, though individual industry rates vary widely. Aligning these sector projections with the local economic structure suggests employment in Light could grow by 5.1% across five years and 11.7% across ten years (this represents an unadjusted weighting extrapolation for context, excluding localized demographic shifts).
Frequently Asked Questions - Employment
Median household income in Light is $1,544 a week (about $80,000 a year), with median personal income at $729 a week. ATO records put median taxable income at $53,341 a year against an average of $62,270. Household income is from the 2021 Census; taxable income is from ATO Taxation Statistics for the latest financial year available, indexed forward using the ABS Wage Price Index.
Detail
Based on ATO postcode records for financial year 2023 compiled by AreaSearch, the Light SA2 area recorded a median taxpayer earnings figure of $53,341 alongside an average of $62,270. While beneath the nationwide standard, these metrics exceed Regional SA ($48,920 median and $58,933 average). Applying the 10.17% Wage Price Index rise recorded since financial year 2023 elevates current March 2026 income estimates to roughly $58,766 (median) and $68,603 (average). Census findings position local personal, family, and household earnings modestly between the 34th and 38th percentiles. In terms of earnings brackets, 35.7% of residents (3,800 individuals) earn between $1,500 - 2,999, mirroring wider regional territory patterns where 27.5% share this band.
Household financial commitments leave 87.9% of income intact after housing outlays, though overall disposable income sits below average in the 43rd percentile.
Frequently Asked Questions - Income
Light had 3,487 occupied dwellings at the 2021 Census, 97% detached houses and 0% apartments. 49% are owned with a mortgage, 14% rented and 37% owned outright. At that Census the median rent was $260 a week and the median mortgage repayment $1,328 a month. Rent absorbs 16.8% of household income here and mortgage repayments 19.8%. Dwelling stock, tenure and housing costs are 2021 Census measures — the only source that counts dwellings at this boundary size.
Detail
Census records indicate the residential profile in Light is heavily concentrated in separate houses (97.3%), with semi-detached dwellings, units, and alternative formats making up just 2.8%, compared to Regional SA with 88.5% houses and 11.5% other dwellings. Outright property ownership in Light was 36.8%, sitting behind the regional benchmark, while 48.9% of properties were held under a mortgage and 14.3% were rented. Typical monthly mortgage payments stood at $1,328, noticeably higher than the Regional SA median of $1,153, while weekly rental costs were $260 against $220 regionally. In the national context, local mortgage servicing remains well below the Australian average of $1,863, with rents also sitting materially below the nationwide figure of $375.
Frequently Asked Questions - Housing
Light counted 3,487 households at the 2021 Census, an estimated 3,789 today, averaging 2.6 people each. 33% are couples with children, against 32% couples without children. 23% of households are people living alone, and families average 1.8 children. Household and family composition is measured only by the Census, so these are 2021 figures.
Detail
Family units constitute the vast majority of local living arrangements at 75.2%, made up of couples with children (32.8%), couples without children (31.6%), and single parent households (10.3%). Non-family dwellings represent the remaining 24.8%, consisting of single-person households at 22.7% and shared group accommodation at 2.0%. The typical household size stands at 2.6 people, higher than the Regional SA average of 2.3.
Frequently Asked Questions - Households
15.7% of adults in Light hold a university qualification, including 12.2% with a bachelor degree and 1.9% with postgraduate qualifications. A further 31.6% hold a vocational qualification. 5 schools serve the area, with 1,273 enrolment places and an average ICSEA of 987 against a national benchmark of 1,000. Qualifications come from the 2021 Census; school enrolments, ICSEA and results come from ACARA's current release.
Detail
Educational attainment profiles show tertiary qualification rates of 15.7%, which fall below the nationwide level of 30.4%, highlighting a clear focus area for future skills development. Among degree holders, bachelor qualifications represent 12.2%, postgraduate awards constitute 1.9%, and graduate diplomas account for 1.6%. Vocational education is strongly represented, with 41.0% of the population aged 15+ possessing technical credentials, including certificates (31.6%) and advanced diplomas (9.4%). Active participation in study is strong throughout the community, with 29.5% of residents enrolled in formal education courses. This cohort comprises 12.6% attending primary school, 7.6% in secondary education, and 4.4% undertaking tertiary studies.
Frequently Asked Questions - Education
Schools Detail
Getting around Light means driving: households keep an average of 2.0 vehicles, and scheduled services reach only a handful of stops. Service data is built from operators' published GTFS timetables; vehicle ownership is from the 2021 Census.
Detail
The local transit network comprises 28 active transport stops throughout Light, connected across 8 individual routes that deliver a combined 45 weekly passenger trips. Public transit access is moderate, with residents located an average of 543 meters from their nearest transit node. Due to the area's predominantly residential setting, outbound commuting is widespread, with private vehicles serving as the primary transport mode for 92% of commuters and 5% traveling on foot. Dwellings maintain an average of 2.0 motor vehicles, outperforming regional standards. Only 10.6% of workers operated from home at the 2021 Census, a metric potentially shaped by prevailing COVID-19 settings.
Public transport operations provide an average frequency of 6 trips per day across the network, translating to roughly 1 weekly trips per individual stop.
Frequently Asked Questions - Transport
Transport Stops Detail
64.8% of residents in Light report no long-term health condition. 5.7% need daily assistance with core activities, and 50.4% hold private health cover. The standardised death rate runs at 5.8 per 1,000 residents. Health conditions, assistance needs and insurance are 2021 Census measures; the death rate comes from current ABS releases.
Detail
Health analyses by AreaSearch reveal elevated mortality figures and chronic disease incidence affecting both younger and older cohorts, alongside a relatively modest private health insurance uptake of roughly 50% (~5,365 people). This insurance coverage sits below the nationwide benchmark of 55.7%. Asthma and mental health conditions rank as the most prevalent health issues in the locality, recorded at 9.8 and 9.5% of the population respectively, while 64.8% of individuals reported no long-term medical conditions, surpassing the 62.5% figure across Regional SA. Health challenges are pronounced among working-age individuals with high chronic condition rates.
Residents aged 65 and over make up 20.5% of the community (2,186 people), below the Regional SA proportion of 27.1%, yet national comparative condition rates remain elevated.
Frequently Asked Questions - Health
Light is largely Australian-born, at 88.8% of residents, with 2.2% speaking a language other than English at home. The largest reported ancestries are English (32.5%) and Australian (32.3%). Ancestry, language and country of birth are counted only by the Census, so these are 2021 figures.
Detail
Cultural diversity measures place Light below wider averages, with 88.8% of residents native-born Australians, 91.9% holding Australian citizenship, and 97.8% communicating only in English at home. Christianity forms the predominant religious affiliation, adhered to by 45.1% of the local population, closely aligning with the 45.2% recorded for Regional SA. Regarding parental lineage and heritage, the three most common backgrounds among Light residents are English (32.5%), Australian (32.3%), and German (12.2%). Other specific cultural backgrounds display localized variances, such as Welsh ancestry accounting for 0.5% in Light (matching 0.5% regionally) and Dutch representing 1.2% (compared to 1.3% across the region).
Frequently Asked Questions - Diversity
The median resident of Light is 40. 25.2% of residents are aged 15 to 34. Age cohorts are not raw Census counts: the Census split is re-based to the latest ABS population estimates and state projections.
Detail
The demographic profile in Light is noticeably younger than that of Regional SA. As at August 2026, residents aged 0 - 24 represent 31.1% of the populace, compared to 26.4% across Regional SA, while senior cohorts aged 65+ make up only 20.5% against 27.1% regionally. The median age is estimated at 40, matching the 2021 Census figure and remaining 7 years younger than the Regional SA median of 47 recorded at that same Census. Over the post-Census period, mature working-age and early retiree groups aged 45 - 64 reduced their share from 27.8% down to an estimated 24.5%.
By 2041, the sharpest expansion will occur in the 65+ demographic, which is projected to grow by 852 residents (39%) to reach 3,039.
Frequently Asked Questions - Age
Data & MethodBoundaries, Sources & Method for Light
9 of 14 data sections on this page were updated within the last 12 months — the newest current to Oct 2026.
Everything is aggregated to the SA2 boundary shown above, on a 2021 Census baseline. Only 3 sections — housing, households and cultural diversity — still wait on the 2026 Census.
The ledger — source, cycle and currency by section
| Section | Source & update cycle | Currency |
|---|---|---|
| Updated within the last 12 months 9 sections | ||
| Population | ABS, GNAF, Geoscience Australia Annual (ABS ERP) | Aug 2026 2 months ago headline measures · 2021 Census baseline |
| Re-based to the ABS Estimated Resident Population (June 2025 release) and updated with new dwellings from GNAF address data. Current to Aug 2026, with the 2021 Census supplying the small-area baseline. | ||
| Age profile | ABS, Geoscience Australia, State governments Annual | Aug 2026 2 months ago headline measures · 2021 Census baseline |
| Age cohorts are re-based to the latest ABS population estimates and state projections, current to Aug 2026. Each cohort is held as a Census baseline and a current estimate. | ||
| Development & approvals | ABS, GNAF Monthly (ABS approvals) | Aug 2026 2 months ago headline measures · Jul 2026 baseline |
| Property sales & rents | Valuer General, Rental Board, ABS Weekly sales, quarterly rents | Oct 2026 this month headline measures · Sep 2026 baseline |
| Sales from the state Valuer General register, refreshed weekly, and rents from quarterly rental bond lodgements. Both are read live each time this page loads, current to Oct 2026. | ||
| Infrastructure projects | Infrastructure Australia, State agencies, Local governments Daily | Aug 2026 2 months ago all 3 projects tracked here |
| Project pipeline maintained continuously from Infrastructure Australia, state agencies, local government and public announcements. Records are added and revised daily; this area was last updated Aug 2026. | ||
| Employment | ABS, DEWR, JSA Quarterly (ABS SALM) | Mar 2026 7 months ago headline measures · 2021 Census baseline |
| Unemployment and labour force from ABS Small Area Labour Markets, current to Mar 2026. The growth outlook applies Department of Employment (now Jobs and Skills Australia) forecasts for all 19 industry divisions to the local industry mix, so it measures sector composition rather than local expansion and makes no allowance for population growth. Job demand comes from the same agency via its Internet Vacancy Index; industry and occupation structure from the 2021 Census. | ||
| Education | ABS, ACARA Annual (ACARA) | Sep 2026 last month headline measures · 2021 Census baseline |
| Transport | ABS, State Transport Departments Each timetable release | Jul 2026 3 months ago headline measures · 2021 Census baseline |
| Services & amenities | Provider directories, ACECQA Continuous | Sep 2026 last month all 14 measures |
| Annual and financial-year sources 2 sections | ||
| Income | ABS, ATO Annual (ATO) | FY 2023 3 years ago headline measures · 2021 Census baseline |
| ATO taxable income statistics for FY 2023, indexed forward using the Wage Price Index. Census household income provides the distribution detail. | ||
| Health | ABS, ATO Annual | 2024 2 years ago headline measures · 2021 Census baseline |
| Census-measured — next update: 2026 Census 3 sections No more current small-area source exists for these, so they are labelled as Census-measured rather than implied to be current. | ||
| Housing | ABS 5-yearly (Census) | 2021 Census next update 2026 all 30 measures |
| Households | ABS 5-yearly (Census) | 2021 Census next update 2026 all 18 measures |
| Cultural diversity | ABS, Geoscience Australia 5-yearly (Census) | 2021 Census next update 2026 all 44 measures |
"Currency" is the most recent release feeding that section. Where the Census supplies the structural baseline underneath a current headline figure, the row says so.
How the numbers are built
Population
The Census provides the small-area baseline, aggregated from mesh blocks to this boundary. It is then re-based to the ABS Estimated Resident Population (June 2025 release), and new dwellings built since Census night are counted from address data — 170 validated new addresses here. The headline figure is therefore a current estimate for Aug 2026, not a 2021 count (9,797 at the 2021 Census → 10,646 now). Annual growth rates are compound (CAGR), not simple averages.
Age profile
Cohort shares are not raw Census counts. Every cohort is held as a pair — the Census baseline and a current estimate — and the split is re-based using ERP and state population projections, current to Aug 2026. Median age is the Census median plus modelled change since. Charts that show both are labelled "2021 Census vs Current Estimate".
Property sales
Sourced from the state valuation authority's sales register — current, not Census, and refreshed weekly. Medians are calculated from settled transactions in the period shown; periods with very low transaction counts are flagged or suppressed, because a handful of sales can move a median substantially.
Rents
Derived from state rental bond lodgement data, by dwelling type and bedroom count. Bonds are lodged at the start of a new tenancy, so this reflects new lettings, not the whole rented stock.
Development & infrastructure
Building approvals come from current ABS releases; development applications are collected from council and state planning portals; the infrastructure pipeline is compiled from Infrastructure Australia and local government sources. Applications are matched to this boundary by address or coordinates, so very recent lodgements may not yet appear.
Employment & income
Industry and occupation structure comes from the Census, but the headline labour-market indicators do not. Unemployment and labour force are derived from ABS Small Area Labour Markets (quarterly). The employment outlook applies Department of Employment forecasts for all 19 industry divisions to this area's own industry mix (the agency is now Jobs and Skills Australia), as does the Internet Vacancy Index used for job demand. Because it is weighted on industry composition alone, that outlook carries no allowance for local population growth — in fast-growing areas the real rise in local jobs will typically be higher. Income combines Census household income with ATO taxable-income statistics for FY 2023, indexed forward using the Wage Price Index.
Education, transport & amenities
School enrolments, ICSEA and performance come from ACARA's current release, not the Census. Public transport stops and service frequency are derived from GTFS timetable feeds published by state transport departments. Services and amenities are proximity and count scores built from provider directories, refreshed on their own cycle. The Census contributes only the travel-to-work and qualification measures.
Rankings and benchmarks. Where we rank this area, the comparison set is every area of the same boundary type — suburbs against suburbs, SA2s against SA2s. Benchmarks compare this area against its greater capital city region and the national figure for the same measure and period.
Limits worth knowing. Small areas carry larger error margins, and the ABS introduces small random adjustments to Census counts to protect confidentiality — so totals may not sum exactly. Estimates re-based from regional data describe the area's expected trajectory, not a direct count of it. Figures are indicative for research and are not financial, planning or valuation advice.
Cross-check us. The Census baseline for this boundary is at ABS 2021 Census QuickStats (405011111). QuickStats reports 2021 only — the figures on this page are more current wherever the ledger shows a later date.