Chart Color Schemes
This analysis uses ABS Statistical Areas Level 2 (SA2) boundaries, which can materially differ from Suburbs and Localities (SAL) even when sharing similar names.
SA2 boundaries are defined by the Australian Bureau of Statistics and are designed to represent communities for statistical reporting (e.g., census and ERP).
Suburbs and Localities (SAL) represent commonly-used suburb/locality names (postal-style areas) and may use different geographic boundaries. For comprehensive analysis, consider reviewing both boundary types if available.
est. as @ -- *
ABS ERP | -- people | --
2021 Census | -- people


Curious about local property values? Filter the chart to assess the volume and appreciation (including resales) trends and regional comparisons, or scroll to the map below view this information at an individual property level.


Find a Recent Sale

Sales Detail
Banks has an estimated 5,043 residents, down from 5,100 at the 2021 Census — a change of 57 people, or 1.1%. That puts 2,241 residents on each square kilometre. Population is estimated from ABS Estimated Resident Population releases and GNAF address data, re-based from the 2021 Census and updated annually.
Detail
As of Aug 2026, AreaSearch estimates the population of Banks to be roughly 5,043 residents. This represents a contraction of 57 people (1.1%) relative to the 5,100 people documented in the 2021 Census. This adjustment is derived from the ABS estimated resident population figure of 5,038 recorded as of June 2025 alongside 3 validated new addresses registered following the Census. The resulting population density stands at 2,241 persons per square kilometer, exceeding the typical benchmark across nationwide areas analyzed by AreaSearch. In contrast to the 1.1% reduction seen in Banks post-census, the broader SA3 territory registered a 1.4% expansion, underscoring contrasting demographic trajectories.
Natural increase served as the primary contributor to local demographic growth, accounting for roughly 74.4% of total population additions over recent timeframes. Projections utilized by AreaSearch incorporate ABS/Geoscience Australia models for SA2 regions published in 2024 using 2022 as their starting baseline. For locations outside this dataset, or for horizons extending beyond 2032, age cohort expansion rates from ACT Government SA2 projections (also anchored to 2022) are applied. Looking at upcoming demographic trajectories across this timeframe, projections outline a shrinking populace, with modeling indicating the local count will drop by 255 persons by 2041. Even so, targeted expansion is expected among specific age brackets, prominently within the 65 to 74 demographic, which is slated to increase by 57 people. Additional details can be found in the age analysis section.
Frequently Asked Questions - Population
Detail
Residential building approvals in Banks have remained negligible over recent periods, recording 4 homes approved across the past 5 financial years (between FY-22 and FY-26). Because approximately 5.2 new residents arrived annually for each home built throughout the past 5 financial years (between FY-22 and FY-26), housing demand heavily outpaces newly added supply, a scenario that typically drives up values and intensifies competition among buyers. Meanwhile, newly constructed residences carry an average construction value of $532,000, signaling that development activity is concentrated on higher-end, premium housing. When measured against Australian Capital Territory, construction in Banks is exceptionally subdued, running 89.0% below the regional per-capita benchmark.
Such restricted additions of new housing commonly bolster pricing and demand across the established market, despite a recent pickup in activity. These rates also trail national norms, highlighting the suburb's established footprint and potential zoning or planning constraints. Moreover, recent residential building has consisted entirely of standalone houses, preserving the neighborhood's low-density suburban layout geared toward family living and generous space. Developers are delivering standalone dwellings at a higher proportion than the existing stock indicates (79.0% at Census), underscoring sustained appetite for family-oriented housing. A metric of approximately 5023 people per approval further reflects an established, low-turnover urban profile. Given that demographic modeling points to a steady or contracting population base, residential demand pressures in Banks could soften, potentially fostering advantageous conditions for purchasers.
Frequently Asked Questions - Development
Development applications around Banks
Loading development applications…
| Lodged | Address | Description | Type | Distance | Status |
|---|
SOURCE: Planning portals and council registers, compiled by AreaSearch. Distance & bearing measured from the suburb midpoint.
AreaSearch tracks one current infrastructure or development project inside Banks, worth an estimated $120 million. A further 16 sit in the immediately surrounding suburbs, taking the tracked pipeline within reach of the area to $2.4 billion. 1 are already under construction and 4 are due for completion within three years. The pipeline spans residential development, health & medical and transport & logistics. Records are compiled from Infrastructure Australia, state agencies, council planning portals and public announcements, reviewed and updated daily, then ranked by proximity, construction stage, completion horizon and project scale.
Detail
Local infrastructure investment, planning frameworks, and major developments play a pivotal role in shaping an area's trajectory. Currently, no major projects have been identified by AreaSearch as having a direct expected impact on the immediate locality. Broader regional initiatives include Southquay Greenway Stage 2 - Block 1 Section 80 Public Housing, Lanyon Marketplace Improvements, Monaro Highway Safety Upgrades, and Big Canberra Battery (Williamsdale BESS), with primary developments outlined below.
Professional plan users can use the search below to filter and access additional projects.
INFRASTRUCTURE SEARCH
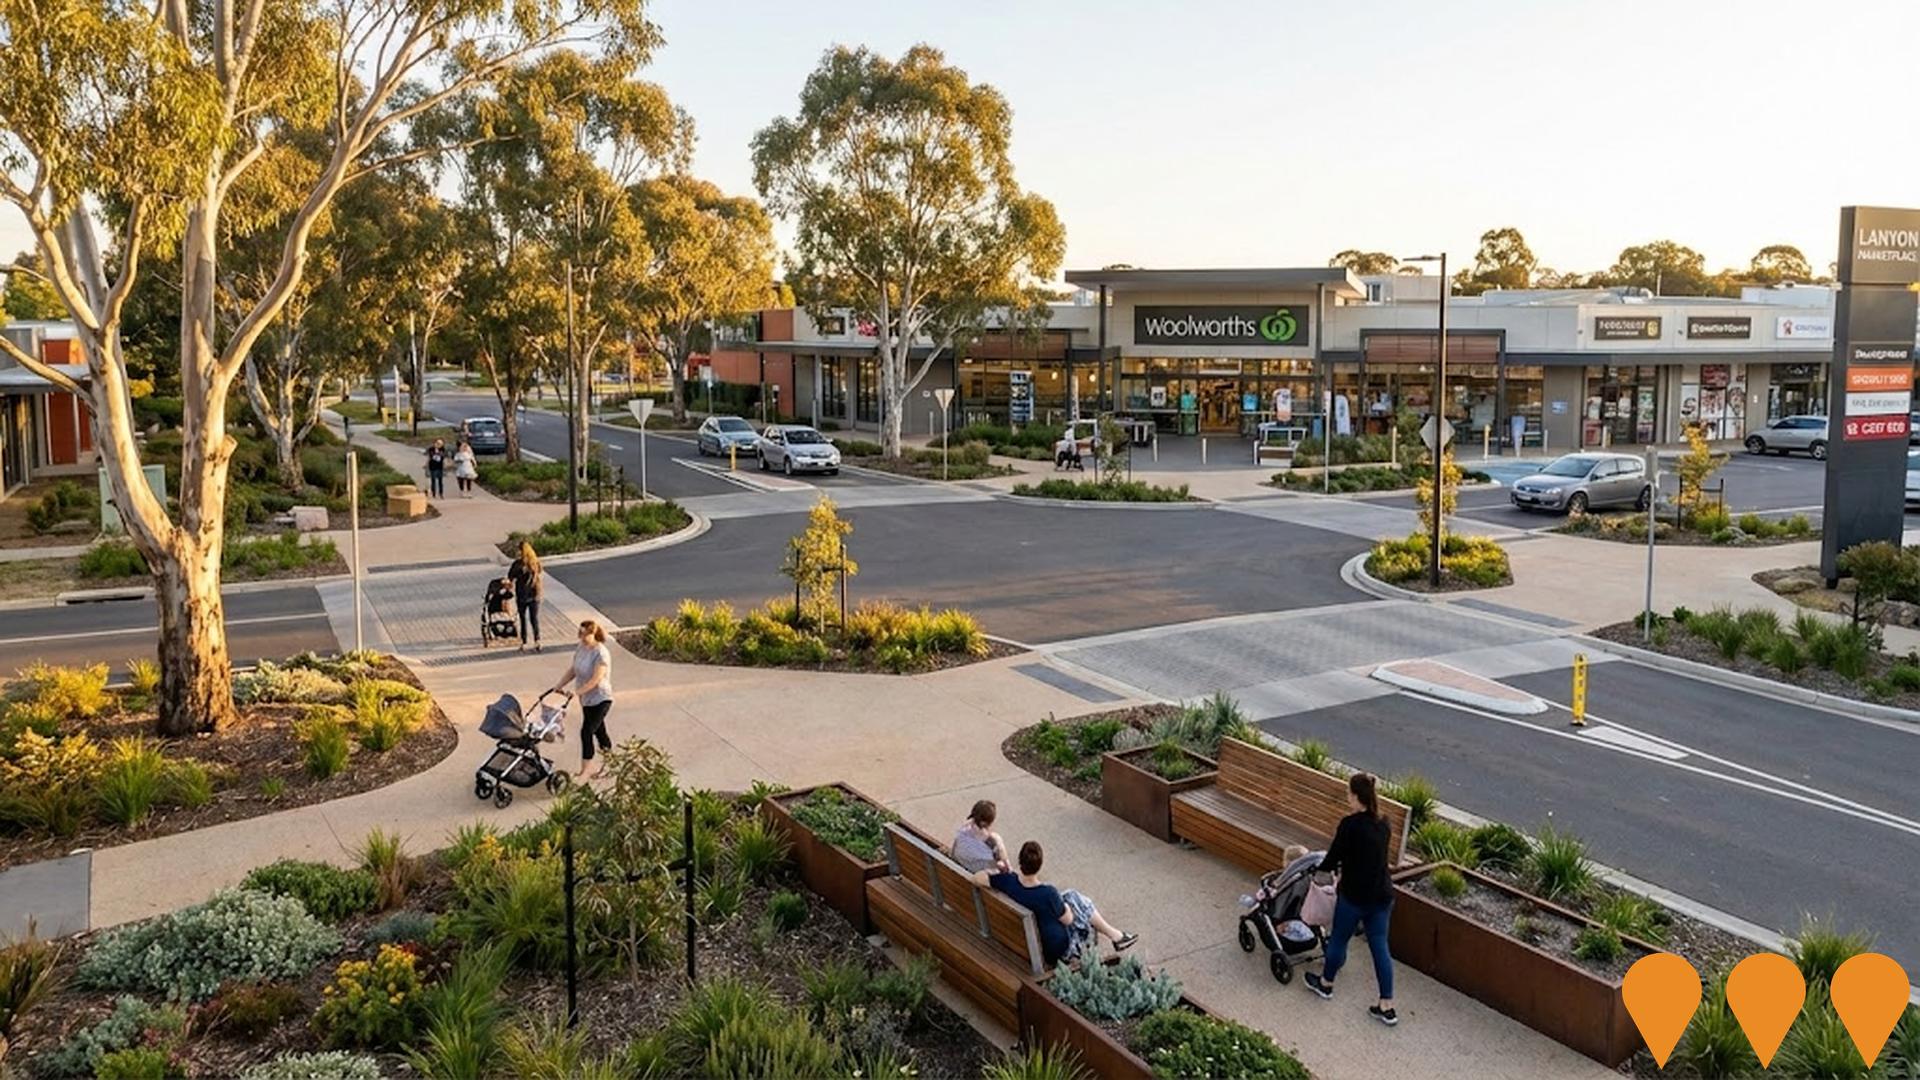
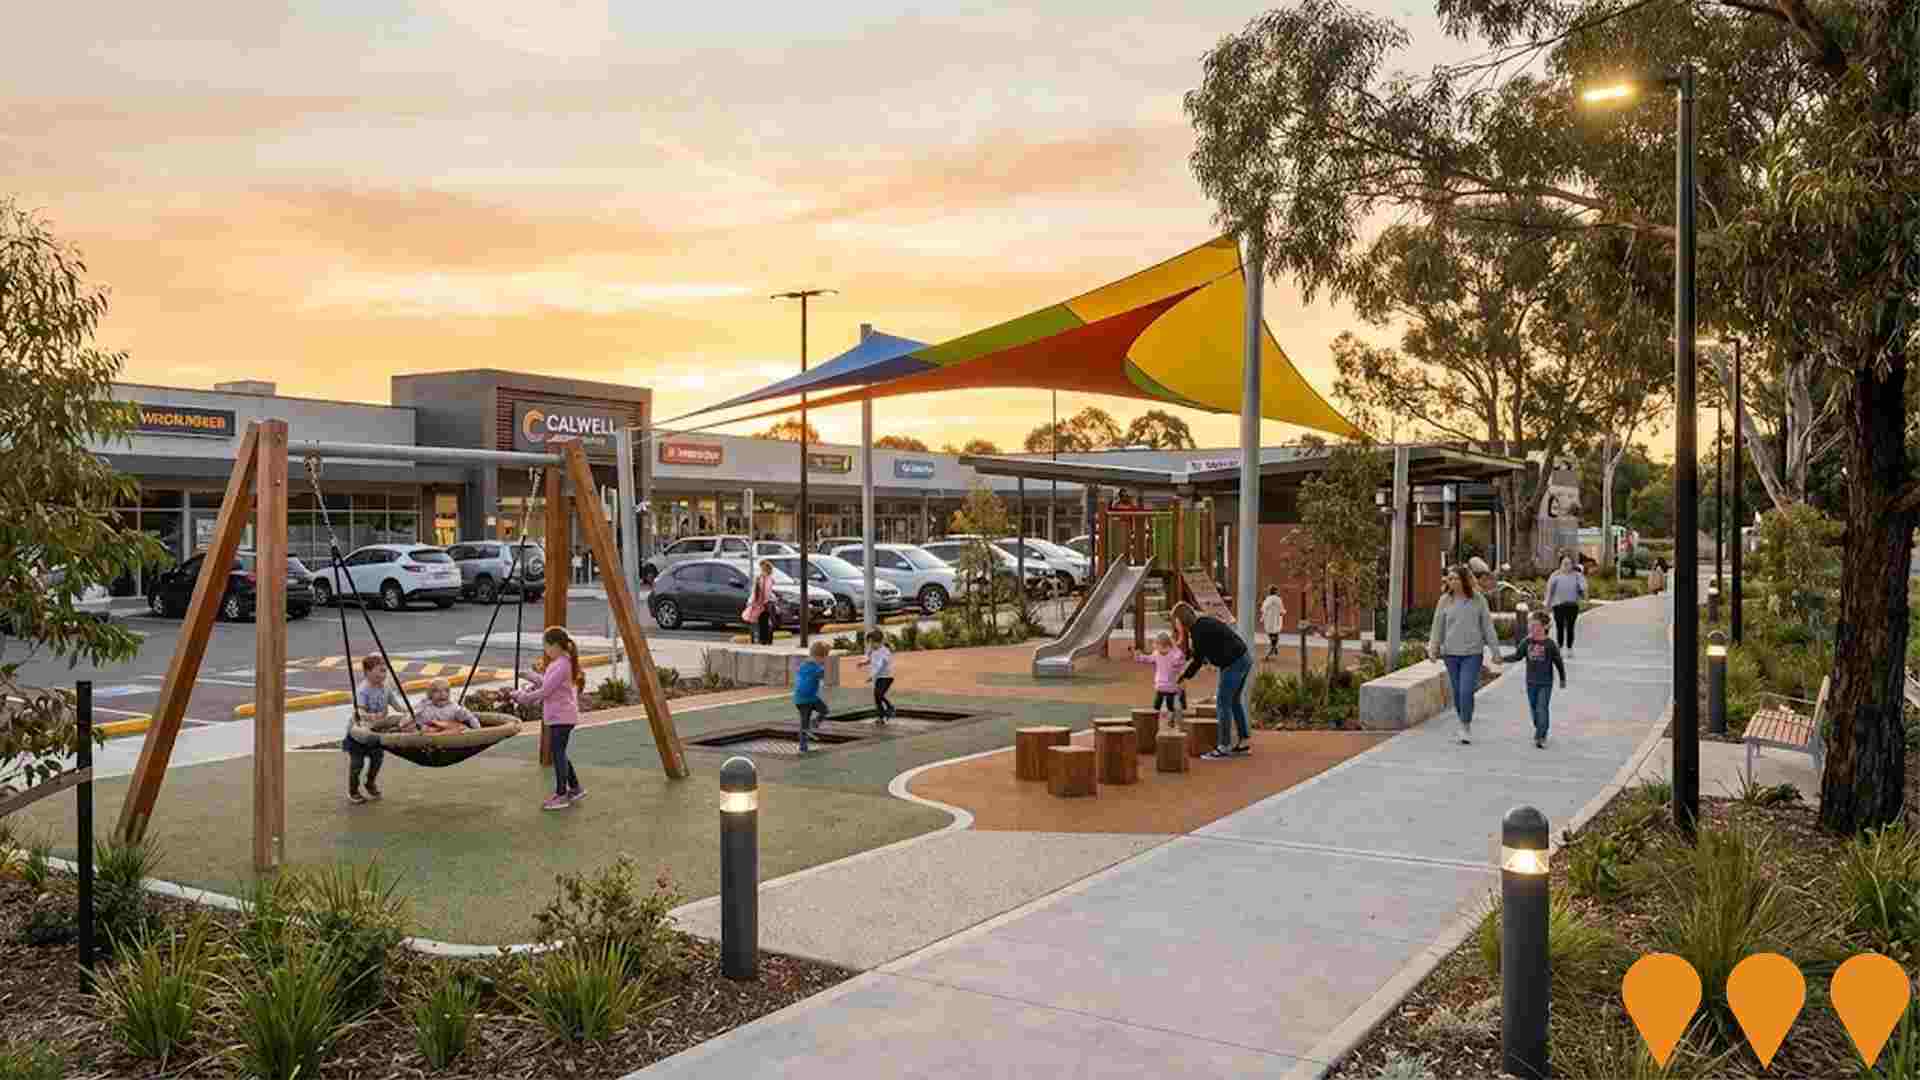
 Denotes AI-based impression for illustrative purposes only, not to be taken as definitive under any circumstances. Please follow links and conduct other investigations from the project's source for actual imagery. Developers and project owners wishing us to use original imagery please Contact Us and we will do so.
Frequently Asked Questions - Infrastructure
Banks Gateway Estate
New residential subdivision by the Suburban Land Agency delivering approximately 220 new homes in Banks, directly adjacent to northern Gordon and within the same primary school catchment. The project is focused on creating a thriving local community.

Tuggeranong Multi-Unit Development - Gordon
Multiple 24-unit developments and supportive housing projects including six single storey supportive housing dwellings with carports, and childcare centre construction for 90 places.
Lanyon Marketplace Improvements
Public space improvements completed in late 2023 at Lanyon Marketplace in Conder. The project, led by the ACT Government, included new seating and landscaping, improved pedestrian access (paths, pram ramps, safe crossings), a new raised intersection at Balcombe and Sidney Nolan Streets, and additional parking spaces on Sidney Nolan Street. The original record's mention of new Coles/Aldi/specialty stores appears to refer to an expected private sector expansion/refurbishment or is based on speculation, as the public works completed focused on the community space and access, with the Marketplace being anchored by Woolworths and 18 specialty shops.There is an ALDI store located at 9 Sidney Nolan Street nearby.
Calwell Retirement Living Precinct
A retirement living precinct proposal by KBDC, featuring 30 one-storey townhouses alongside the Calwell shopping strip.

Calwell Group Centre improvements
Public space upgrades at local shops including new seating, playground with nature play elements, accessible parking bays, improved pedestrian access, upgraded lighting, and enhanced landscaping. Features nest swing, trampolines, slide, steppers and new shade sail.
Calwell Public Housing Development
30 new public housing townhouses (2 and 3 bedroom) built to Class C Adaptable standards. Features evaporative heating/cooling, 6-star energy rating hot water systems, double-glazed windows, and sustainable design.
EV Fast Charging Infrastructure - Calwell (Calwell Shopping Centre)
Public DC fast EV charging delivered at Calwell Shopping Centre and operated by Evie Networks, supported by ACT Government grants and ARENA funding to expand Canberra's charging network.
Tuggeranong Public Housing Development
Major public housing development in Tuggeranong providing affordable housing options for low-income families and individuals. Includes multiple apartment complexes and townhouses with community facilities and support services.
3,020 residents of Banks are employed, from a labour force of 3,166. Unemployment sits at 4.6%, with participation at 78.3%. Weighted for its industry mix, the area's sectors are forecast to grow about 6.1% nationally over five years. That reflects industry composition only and makes no allowance for local population growth. The working-day population is estimated at 3,545, about 70% of the resident population, so more people leave the area for work than travel in. Unemployment and labour force come from ABS Small Area Labour Markets, updated quarterly; the industry and occupation profile is from the 2021 Census.
Detail
The workforce in Banks is characterized by strong skill levels and robust participation in essential services, alongside an unemployment rate of 4.6% and consistent job stability over the previous year. By March 2026, employed residents reached 3,020, while the local jobless rate stood 0.6% above the 4.1% recorded for Australian Capital Territory. Labor force engagement remains notably elevated at 78.3%, well above the 70.6% seen across Australian Capital Territory. According to Census data, only 8.0% of local workers operated from home, though prevailing Covid-19 restrictions at that time should be kept in mind.
The primary employment sectors for local residents include public administration & safety, health care & social assistance, and construction. Building and construction displays a pronounced local concentration, capturing a workforce share 1.5 times the regional norm. Conversely, professional & technical roles account for only 6.4% of resident workers, trailing the 11.1% benchmark for Australian Capital Territory. Being an overwhelmingly residential district, internal employment opportunities remain constrained, as evidenced by comparing the Census working population against resident worker totals. AreaSearch's evaluation of ABS and SALM figures indicates that over the 12-month period, local employment expanded by 0.4% while the labor pool grew by 1.1%, resulting in a 0.6 percentage point increase in the unemployment rate. Over the identical timeframe, Australian Capital Territory saw employment rise by 0.3%, the labor force increase by 1.1%, and joblessness rise by 0.7 percentage points. Projections issued by Jobs and Skills Australia as of Mar-26 provide an indicator of future labor requirements relevant to Banks. These five- and ten-year national estimates have been applied to the local workforce composition to evaluate prospective expansion patterns. Across the nation, overall employment is anticipated to grow by 6.6% over five years and 13.7% over ten years, though trajectories vary by industry. Mapping these sector-level expectations to the local workforce structure indicates Banks could see employment growth of 6.1% over five years and 12.6% over ten years (note that this reflects a weighted industry extrapolation for modeling purposes and omits specific local population shifts).
Frequently Asked Questions - Employment
Median household income in Banks is $2,419 a week (about $126,000 a year), with median personal income at $1,168 a week. ATO records put median taxable income at $72,291 a year against an average of $78,802. Household income is from the 2021 Census; taxable income is from ATO Taxation Statistics for the latest financial year available, indexed forward using the ABS Wage Price Index.
Detail
Taxation records aggregated by AreaSearch from the ATO for financial year 2023 place taxpayer earnings in the Banks SA2 well above countrywide standards. The median taxable income within the Banks SA2 reaches $72,291 with an average of $78,802, compared with Australian Capital Territory figures of $72,206 and $85,981 respectively. Factoring in a 10.44% rise in the Wage Price Index since financial year 2023, updated estimates reach approximately $79,838 for median earnings and $87,029 for average income as of March 2026. Figures from the 2021 Census position local personal, family, and household earnings within the 88th to 89th percentiles nationwide.
In terms of earnings distribution, 37.0% of individuals (1,865 individuals) fall into the $1,500 - 2,999 weekly bracket, closely aligning with the 34.3% regional metropolitan rate. Affluence is prominent, with 37.0% generating more than $3,000 per week, underpinning demand for upscale commercial and retail services. Housing costs absorb 14.6% of income, strong earnings place residents in the 88th percentile for disposable funds, and the SEIFA income measure places the suburb in the 6th decile.
Frequently Asked Questions - Income
Banks had 1,772 occupied dwellings at the 2021 Census, 79% detached houses and 4% apartments. 60% are owned with a mortgage, 18% rented and 22% owned outright. At that Census the median rent was $424 a week and the median mortgage repayment $2,000 a month, a total housing cost higher than 83% of areas nationally. Rent absorbs 17.5% of household income here and mortgage repayments 19.1%. Dwelling stock, tenure and housing costs are 2021 Census measures — the only source that counts dwellings at this boundary size.
Detail
According to findings from the most recent Census, the housing inventory in Banks was made up of 79.1% houses and 21.0% other dwellings (comprising semi-detached units, apartments, and alternative structures), contrasting with Australian Capital Territory proportions of 63.3% houses and 36.7% other dwellings. Outright home ownership in Banks trailed the wider territory at 21.9%, while the balance of homes were under a mortgage (60.0%) or occupied by tenants (18.1%). Monthly mortgage payments sat at a median of $2,000, under the Australian Capital Territory norm of $2,080, while median weekly rent was $424, below the territory figure of $450.
On a countrywide basis, monthly mortgage costs in Banks exceed the national average of $1,863, and weekly rents track substantially higher than the Australian standard of $375.
Frequently Asked Questions - Housing
Banks counted 1,772 households at the 2021 Census, averaging 2.8 people each. 41% are couples with children, more than in 81% of areas nationally, against 23% couples without children. 20% of households are people living alone, and families average 1.6 children. Household and family composition is measured only by the Census, so these are 2021 figures.
Detail
Families constitute the vast majority of local households at 78.8%, split between couples with children at 41.0%, couples without children at 23.4%, and single parent arrangements at 14.1%. Non-family living situations account for the other 21.2%, consisting of single-person households at 19.8% and group living arrangements at 1.4%. The median household occupancy of 2.8 people surpasses the Australian Capital Territory average of 2.5.
Frequently Asked Questions - Households
22.9% of adults in Banks hold a university qualification, including 15.3% with a bachelor degree and 4.5% with postgraduate qualifications. A further 26.5% hold a vocational qualification. Qualifications come from the 2021 Census.
Detail
Educational profiles indicate that university attainment in Banks (22.9%) sits well below the wider SA4 regional benchmark of 46.8%, presenting an opportunity for targeted learning programs. Higher education qualifications are led by bachelor degrees at 15.3%, followed by postgraduate degrees (4.5%) and graduate diplomas (3.1%). In contrast, vocational and trade capabilities are widespread, with 38.8% of individuals aged 15+ holding technical qualifications, including advanced diplomas (12.3%) and certificates (26.5%). Participation in study is substantial across the suburb, with 30.5% of the local population engaged in formal courses. This cohort encompasses 10.8% attending primary school, 8.8% in secondary education, and 3.6% enrolled in tertiary programs.
Frequently Asked Questions - Education
Schools Detail
Public transport in Banks reaches 25 stops on 55 routes, timetabled for about 3,600 services a week. The typical home sits about 160 m from its nearest stop. Buses carry the largest share of public transport commuters. Households keep an average of 1.8 vehicles. Stop and service counts are built from operators' published GTFS timetables and refresh with each timetable release; vehicle ownership is from the 2021 Census.
Detail
Public transit networks in Banks encompass 25 active transport stops featuring bus operations. Across these locations, 55 individual routes deliver 3,557 weekly passenger trips. Transit access is rated as excellent, with typical walking distances to the closest boarding point measuring 155 meters. As an established residential community, outward travel is common, with private cars serving as the principal transport choice for 93% of commuters. Household vehicle ownership stands at 1.8 per dwelling, exceeding regional levels. A modest 8.0% of workers conducted their jobs from home according to the 2021 Census, a figure that may reflect prevailing COVID-19 settings.
Across the entire route network, transit frequencies average 508 trips per day, providing roughly 142 weekly departures for each individual stop.
Frequently Asked Questions - Transport
Transport Stops Detail
68.7% of residents in Banks report no long-term health condition. 4.5% need daily assistance with core activities, and 58.4% hold private health cover. The standardised death rate runs at 5.9 per 1,000 residents. Health conditions, assistance needs and insurance are 2021 Census measures; the death rate comes from current ABS releases.
Detail
Health evaluations by AreaSearch indicate notable challenges in Banks regarding mortality rates and the prevalence of chronic health conditions across both younger and older demographics. At the same time, private healthcare enrollment is extensive, covering approximately 58% of all residents (~2,945 people), compared to 62.4% throughout Australian Capital Territory. Mental health conditions and asthma represent the most widespread diagnoses locally, affecting 10.3 and 8.7% of the populace, respectively, whereas 68.7% of community members reported no chronic ailments, against 70.2% across Australian Capital Territory. Working-age adults display higher-than-average rates of long-term medical conditions.
Residents aged 65 and over make up 11.3% of the community (569 people), below the 14.2% proportion across Australian Capital Territory. Overall health metrics for senior residents present some vulnerabilities, maintaining national rankings generally consistent with the wider population.
Frequently Asked Questions - Health
Banks is largely Australian-born, at 81.4% of residents, with 15.3% speaking a language other than English at home. The largest reported ancestries are Australian (28.0%) and English (26.1%). Ancestry, language and country of birth are counted only by the Census, so these are 2021 figures.
Detail
Banks exhibits above-average cultural variety, with 18.6% of residents born abroad and 15.3% communicating in a language other than English within their households. Christianity represents the leading religious affiliation, observed by 45.9% of the local populace. The most notable relative concentration occurs among those identifying with Judaism, accounting for 0.2% of the suburb, matching the 0.2% share seen across Australian Capital Territory. Examining parental country of birth, the primary ancestries in Banks are Australian at 28.0% (substantially above the 23.0% regional rate), English at 26.1%, and Other at 9.6%. Furthermore, several ethnic groups show notable local differences in representation, including Spanish at 1.1% (compared to 0.5% regionally), Polish at 1.1% (against 0.8%), and Croatian at 1.1% (relative to 0.9%).
Frequently Asked Questions - Diversity
The median resident of Banks is 35, younger than 79% of areas nationally. 27.4% of residents are aged 15 to 34. Age cohorts are not raw Census counts: the Census split is re-based to the latest ABS population estimates and state projections.
Detail
The age distribution in Banks closely mirrors broader Australian Capital Territory patterns, with the largest variance across the four broad cohorts measuring 4.7 percentage points. The median age is estimated at 35, matching the level reported in the 2021 Census and identical to the Australian Capital Territory median of 35 from that same Census. The most pronounced shift across these broad brackets since the Census has occurred within retiree and elderly cohorts (65+), rising from 8.4% to an estimated 11.3% of the community. Looking ahead to 2041, the largest population increase is projected for retiree and elderly cohorts, expanding by 112 residents (20%) to reach 682.
Over this identical timeframe, young to middle aged adults are expected to decrease, accompanied by contractions in children and young adults.
Frequently Asked Questions - Age
Data & MethodBoundaries, Sources & Method for Banks
9 of 14 data sections on this page were updated within the last 12 months — the newest current to Oct 2026.
Everything is aggregated to the SA2 boundary shown above, on a 2021 Census baseline. Only 3 sections — housing, households and cultural diversity — still wait on the 2026 Census.
The ledger — source, cycle and currency by section
| Section | Source & update cycle | Currency |
|---|---|---|
| Updated within the last 12 months 9 sections | ||
| Population | ABS, GNAF, Geoscience Australia Annual (ABS ERP) | Aug 2026 2 months ago headline measures · 2021 Census baseline |
| Re-based to the ABS Estimated Resident Population (June 2025 release) and updated with new dwellings from GNAF address data. Current to Aug 2026, with the 2021 Census supplying the small-area baseline. | ||
| Age profile | ABS, Geoscience Australia, State governments Annual | Aug 2026 2 months ago headline measures · 2021 Census baseline |
| Age cohorts are re-based to the latest ABS population estimates and state projections, current to Aug 2026. Each cohort is held as a Census baseline and a current estimate. | ||
| Development & approvals | ABS, GNAF Monthly (ABS approvals) | Aug 2026 2 months ago headline measures · Jul 2026 baseline |
| Property sales & rents | Valuer General, Rental Board, ABS Weekly sales, quarterly rents | Oct 2026 this month headline measures · Sep 2026 baseline |
| Sales from the state Valuer General register, refreshed weekly, and rents from quarterly rental bond lodgements. Both are read live each time this page loads, current to Oct 2026. | ||
| Infrastructure projects | Infrastructure Australia, State agencies, Local governments Daily | Aug 2026 2 months ago all 1 projects tracked here |
| Project pipeline maintained continuously from Infrastructure Australia, state agencies, local government and public announcements. Records are added and revised daily; this area was last updated Aug 2026. | ||
| Employment | ABS, DEWR, JSA Quarterly (ABS SALM) | Mar 2026 7 months ago headline measures · 2021 Census baseline |
| Unemployment and labour force from ABS Small Area Labour Markets, current to Mar 2026. The growth outlook applies Department of Employment (now Jobs and Skills Australia) forecasts for all 19 industry divisions to the local industry mix, so it measures sector composition rather than local expansion and makes no allowance for population growth. Job demand comes from the same agency via its Internet Vacancy Index; industry and occupation structure from the 2021 Census. | ||
| Education | ABS, ACARA Annual (ACARA) | Sep 2026 last month headline measures · 2021 Census baseline |
| Transport | ABS, State Transport Departments Each timetable release | Jul 2026 3 months ago headline measures · 2021 Census baseline |
| Services & amenities | Provider directories, ACECQA Continuous | Sep 2026 last month all 14 measures |
| Annual and financial-year sources 2 sections | ||
| Income | ABS, ATO Annual (ATO) | FY 2023 3 years ago headline measures · 2021 Census baseline |
| ATO taxable income statistics for FY 2023, indexed forward using the Wage Price Index. Census household income provides the distribution detail. | ||
| Health | ABS, ATO Annual | 2024 2 years ago headline measures · 2021 Census baseline |
| Census-measured — next update: 2026 Census 3 sections No more current small-area source exists for these, so they are labelled as Census-measured rather than implied to be current. | ||
| Housing | ABS 5-yearly (Census) | 2021 Census next update 2026 all 30 measures |
| Households | ABS 5-yearly (Census) | 2021 Census next update 2026 all 18 measures |
| Cultural diversity | ABS, Geoscience Australia 5-yearly (Census) | 2021 Census next update 2026 all 44 measures |
"Currency" is the most recent release feeding that section. Where the Census supplies the structural baseline underneath a current headline figure, the row says so.
How the numbers are built
Population
The Census provides the small-area baseline, aggregated from mesh blocks to this boundary. It is then re-based to the ABS Estimated Resident Population (June 2025 release), and new dwellings built since Census night are counted from address data — 3 validated new addresses here. The headline figure is therefore a current estimate for Aug 2026, not a 2021 count (5,100 at the 2021 Census → 5,043 now). Annual growth rates are compound (CAGR), not simple averages.
Age profile
Cohort shares are not raw Census counts. Every cohort is held as a pair — the Census baseline and a current estimate — and the split is re-based using ERP and state population projections, current to Aug 2026. Median age is the Census median plus modelled change since. Charts that show both are labelled "2021 Census vs Current Estimate".
Property sales
Sourced from the state valuation authority's sales register — current, not Census, and refreshed weekly. Medians are calculated from settled transactions in the period shown; periods with very low transaction counts are flagged or suppressed, because a handful of sales can move a median substantially.
Rents
Derived from state rental bond lodgement data, by dwelling type and bedroom count. Bonds are lodged at the start of a new tenancy, so this reflects new lettings, not the whole rented stock.
Development & infrastructure
Building approvals come from current ABS releases; development applications are collected from council and state planning portals; the infrastructure pipeline is compiled from Infrastructure Australia and local government sources. Applications are matched to this boundary by address or coordinates, so very recent lodgements may not yet appear.
Employment & income
Industry and occupation structure comes from the Census, but the headline labour-market indicators do not. Unemployment and labour force are derived from ABS Small Area Labour Markets (quarterly). The employment outlook applies Department of Employment forecasts for all 19 industry divisions to this area's own industry mix (the agency is now Jobs and Skills Australia), as does the Internet Vacancy Index used for job demand. Because it is weighted on industry composition alone, that outlook carries no allowance for local population growth — in fast-growing areas the real rise in local jobs will typically be higher. Income combines Census household income with ATO taxable-income statistics for FY 2023, indexed forward using the Wage Price Index.
Education, transport & amenities
School enrolments, ICSEA and performance come from ACARA's current release, not the Census. Public transport stops and service frequency are derived from GTFS timetable feeds published by state transport departments. Services and amenities are proximity and count scores built from provider directories, refreshed on their own cycle. The Census contributes only the travel-to-work and qualification measures.
Rankings and benchmarks. Where we rank this area, the comparison set is every area of the same boundary type — suburbs against suburbs, SA2s against SA2s. Benchmarks compare this area against its greater capital city region and the national figure for the same measure and period.
Limits worth knowing. Small areas carry larger error margins, and the ABS introduces small random adjustments to Census counts to protect confidentiality — so totals may not sum exactly. Estimates re-based from regional data describe the area's expected trajectory, not a direct count of it. Figures are indicative for research and are not financial, planning or valuation advice.
Cross-check us. The Census baseline for this boundary is at ABS 2021 Census QuickStats (801071071). QuickStats reports 2021 only — the figures on this page are more current wherever the ledger shows a later date.